5 Questions to Ask About AI Portfolio Recommendations
AI portfolio recommendations can turn a complicated investment decision into a confident-looking suggestion: buy this stock, reduce that position or follow a successful investor. But a clear answer is not necessarily a well-supported one. Before acting, you need to understand what the system knows, what it assumes and what could happen if its recommendation is wrong.
For retail investors, the goal is not to decide whether AI is universally good or bad at investing. It is to determine whether a particular recommendation deserves a place in your decision-making process. These five questions provide a practical way to assess it.
1. What data supports the recommendation, and how current is it?
Start with the evidence behind the output. A model drawing on verified brokerage holdings has a different foundation from one summarizing social posts, company filings or historical prices. None of those sources answers every investment question.
Verified holdings can establish that an investor owns a position. They do not, by themselves, establish why the investor bought it, whether it is profitable or whether other accounts contain offsetting positions.
Ask the provider to explain three things:
- Source: Does the recommendation use verified holdings, market data, public disclosures or unverified commentary?
- Timing: When were positions and prices last updated, and how are delayed or missing records handled?
- Coverage: Which investors, accounts and assets are included, and what is absent?
A stock-level view such as Visa’s community ownership information can help you investigate who holds a security within a platform’s community. It should not be interpreted as a representative survey of every investor in that stock.
AI portfolio recommendations based on community activity also need to distinguish ownership from action. A position can grow because its price increased, not because investors bought more shares. Likewise, rising ownership counts do not reveal how much money each investor committed.
Look for traceable evidence and visible timestamps. If the explanation stops at “our algorithm identified an opportunity,” you still lack the information needed to evaluate it.
2. Do the AI portfolio recommendations fit my goals and risk?
A recommendation can be reasonable for someone else and unsuitable for you. An investor saving for a home purchase next year faces different constraints from someone investing for retirement in three decades.
Useful personalization starts with your financial circumstances, not just the stocks you like. Relevant inputs include your time horizon, cash needs, ability to absorb losses, existing holdings and account type. Risk tolerance matters too, but willingness to take risk is different from having the financial capacity to take it.
Personalization is common outside finance. For example, AI-powered travel planning can match suggestions to a traveler’s preferences. Investment recommendations require a higher-stakes distinction: something that matches your interests may still expose money you cannot afford to lose.
Review the proposed portfolio after the change, rather than judging the suggested asset in isolation. A broad-market fund may already own the same company. Several funds with different names may also hold many of the same stocks.
Ask how the recommendation changes concentration, liquidity and exposure to common risk factors. Adding another technology company might increase an existing dependence on growth-stock valuations rather than provide meaningful diversification.
If the system does not know about assets held elsewhere, outstanding obligations or near-term spending, treat its output as incomplete research. You can still investigate the idea, but you should not mistake limited inputs for a complete assessment of your finances.
3. Is the performance evidence live, comparable and complete?
A strong historical return can make AI portfolio recommendations look persuasive. First establish whose return you are seeing: the model’s, a selected investor’s or a hypothetical portfolio assembled after the fact.
These are different forms of evidence:
| Evidence presented | What it can tell you | What it does not establish |
|---|---|---|
| Historical backtest | How a strategy would have behaved under stated assumptions | That it could have been implemented as modeled or will work in the future |
| Paper portfolio | How recorded simulated decisions performed | Actual execution prices, investor behavior or realized trading costs |
| Live account record | Results achieved in a particular account | That another investor could reproduce those results |
| Top-performer ranking | Which included accounts did best under the ranking method | How typical those results are across the full population |
Ask whether the record includes closed positions and unsuccessful accounts. Excluding investors who left or portfolios that failed can create survivorship bias. Backtests also need safeguards against using information that was unavailable at the time.
Then examine the comparison. Are dividends included? How are deposits and withdrawals handled? Are returns shown before or after fees? Does the benchmark have a similar risk profile?
Return and Sharpe metrics can add context, but neither settles the question. Compare Sharpe ratios only when time periods and calculation methods are consistent. A short, unusually calm period can make risk-adjusted performance look stronger than a longer record would suggest.
The most useful evidence includes drawdowns and losing periods, not just the best result. Past performance does not guarantee future returns.
4. What will implementation cost, and should I trade at all?
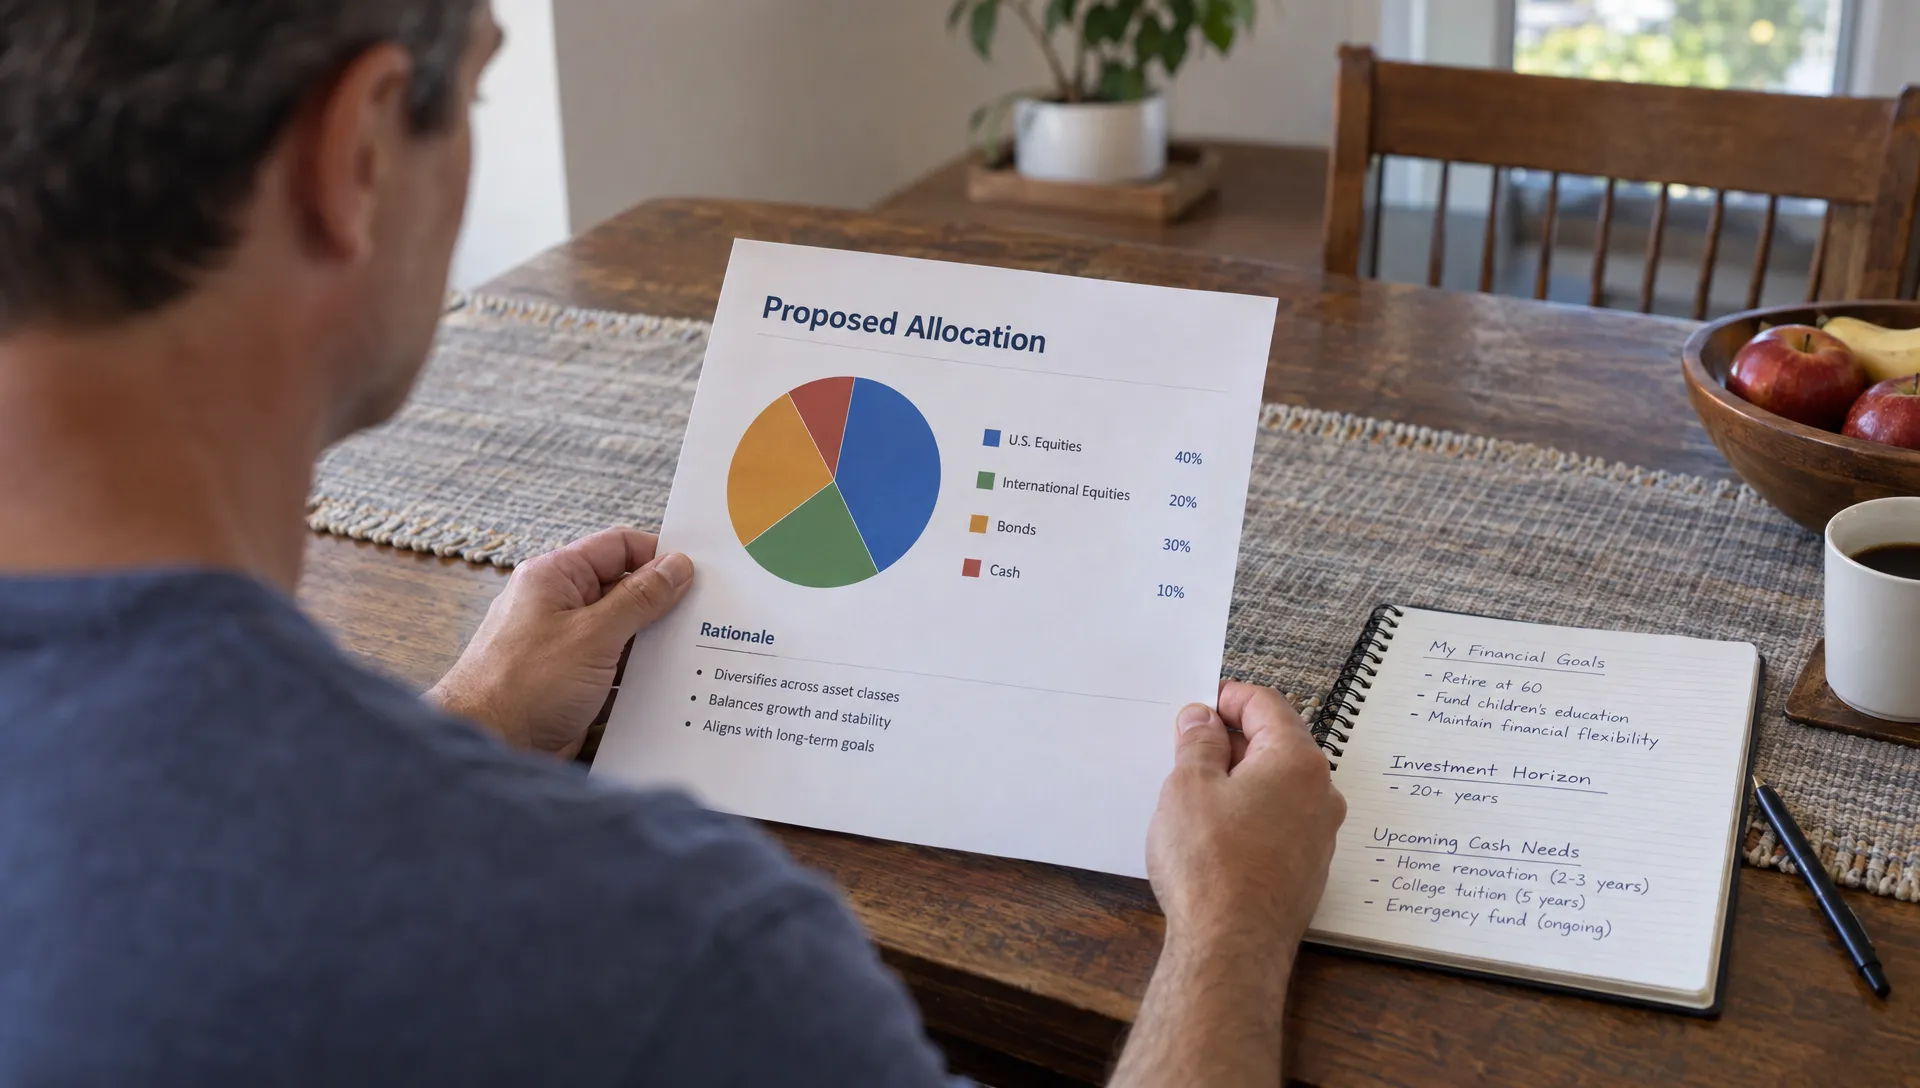
An appealing portfolio change can become less attractive after taxes, trading friction and the price you actually pay. Evaluate the benefit at the account level, not just the forecast for a single security.
Potential costs include advisory or subscription charges, fund expenses, bid-ask spreads, currency conversion and taxes from selling appreciated positions. Commission-free trading does not eliminate every implementation cost.
For example, replacing a broadly diversified fund with several individual stocks may create taxable gains and more positions to monitor. The proposed improvement needs to justify those consequences. Tax treatment depends on your jurisdiction, account and circumstances, so material changes may warrant professional tax advice.
Timing matters as well. A recommendation derived from another investor’s purchase may reach you after the price has moved. That investor may have entered gradually, hedged elsewhere or intended to hold through losses you would find unacceptable.
AI portfolio recommendations should also be evaluated against doing nothing. Ask what problem the trade solves, what happens if you delay it and whether directing future contributions differently could achieve a similar allocation without selling existing holdings.
Before placing an order, understand the proposed position size, the source of funds and the conditions that would justify reviewing the decision. A compelling stock thesis is not a complete portfolio implementation plan.
If a service enables copy trading or automated execution, inspect the authorization settings separately. Learning from someone’s holdings and giving a system permission to trade are materially different decisions.
5. Who is accountable, and what control do I retain?
A provider should explain what service it offers, who stands behind it and how it earns money. AI portfolio recommendations do not remove the need to examine incentives, disclosures and responsibility.
Ask whether the output is general investment research, personalized advice or part of a service that executes trades. The label “AI” does not determine the service’s legal obligations.
If a provider presents itself as an investment adviser, check its registration and disclosures through the SEC’s Investment Adviser Public Disclosure database. Registration is not SEC approval of a strategy or a guarantee of good performance.
Examine conflicts too. Does the provider receive compensation connected to particular products, referrals, trading activity or promoted placements? Understand whether those arrangements can influence what you see.
Privacy requires its own review, especially when account verification is involved. An anonymous public profile does not necessarily mean the provider holds no identifying information. Ask what data is collected, who can access it, how long it is retained and whether it is shared or used to train models.
Check account-connection permissions rather than assuming that every integration is read-only. Understand how to revoke access and what happens to previously collected records after deletion.
Finally, establish how you can question an output. You should be able to identify the recommendation’s date, supporting evidence and assumptions. If automation is available, confirm how to pause it and which actions require your approval. An explanation is useful only if it helps you retain informed control.
Put the answers beside your actual portfolio
Before acting, write down the suggested change, its evidence, its effect on your allocation and its likely costs. Record what would cause you to reconsider. That turns a persuasive suggestion into a decision you can review later.
Upside Invest combines verified investor holdings, portfolio comparison tools and AI portfolio recommendations with private anonymous profiles. Use those capabilities to investigate ownership patterns and compare allocations, while keeping the limits of community data in view. Other investors’ portfolios can inform your research, but your goals, constraints and capacity for loss should determine what you do next.