5 Stocks With Massive Upside Potential From Turnarounds
Finding stocks with massive upside potential takes more than sorting for the biggest share-price declines. A credible turnaround needs a repairable business, enough financial runway to complete the repair and a valuation that leaves room for shareholders to benefit. A company can recover operationally while its stock disappoints if investors already paid for that recovery.
PayPal, Nike, Estée Lauder, Boeing and Intel offer five different recovery frameworks to investigate. This is a conditional research watchlist, not a live screen of undervalued stocks. No current share prices, analyst targets or latest-quarter results are assumed; each thesis needs to be checked against current disclosures.
What makes a turnaround worth researching?
A falling stock becomes interesting when the underlying problem is identifiable and potentially reversible. Excess inventory can clear. An inefficient distribution strategy can change. Persistent loss of customer relevance is harder to fix.
The ranking below prioritizes the clarity of the operating repair and the capital required to achieve it, rather than predicted returns. Four tests matter:
- A repairable problem: Management has specific operational levers, not just an optimistic market forecast.
- Financial runway: Cash generation and available financing can support the recovery without unacceptable dilution.
- Observable milestones: Investors can test progress through margins, inventory, deliveries or customer economics.
- A sensible entry valuation: Conservative assumptions support the purchase price without requiring a perfect outcome.
Before researching stocks with massive upside potential, establish what would make you reject the thesis. Review the latest annual and quarterly reports through SEC EDGAR, particularly debt maturities, liquidity disclosures and changes in diluted shares outstanding.
Five turnaround candidates, ranked by the recovery framework
| Rank | Company | Recovery engine to investigate | Central failure risk |
|---|---|---|---|
| 1 | PayPal (PYPL) | Better checkout economics and profitable engagement | Payment growth without stronger profits |
| 2 | Nike (NKE) | Product demand and healthier distribution | Brand weakness mistaken for a temporary slowdown |
| 3 | Estée Lauder (EL) | Inventory normalization and margin recovery | Discounting or weak demand prevents repair |
| 4 | Boeing (BA) | Reliable production and aircraft deliveries | Quality problems prolong cash consumption |
| 5 | Intel (INTC) | Manufacturing execution and better capital returns | Spending needs outrun commercial progress |
1. PayPal: distinguish profitable engagement from payment volume
PayPal's turnaround framework centers on converting its customer relationships and checkout presence into durable per-share cash generation. Payment volume alone cannot establish that the business is becoming more valuable. Different transaction types carry different economics, so a shift in business mix can separate volume growth from profit growth.
The recovery case would strengthen if branded checkout becomes more competitive, customer engagement improves and monetization efforts generate profits rather than simply more activity. Cost discipline can help, but lasting improvement needs a product that merchants and consumers continue choosing.
Among stocks with massive upside potential, PayPal represents a thesis where better operating execution could matter more than a dramatic expansion into a new industry. That still requires evidence of differentiation in a competitive payments market.
What to monitor: Compare transaction-related profit measures with payment volume, track operating margins and examine free cash flow alongside stock-based compensation. Check whether repurchases actually reduce the diluted share count rather than largely offsetting employee share issuance.
Valuation discipline: Use a conservative range of sustainable cash generation per share. Do not assume that a former valuation multiple is an appropriate destination.
What breaks the thesis: Checkout loses relevance, growth increasingly comes from less profitable processing or reported cash generation fails to translate into better economics for each remaining share.
2. Nike: require evidence of consumer demand, not just cost savings
Nike's recovery framework combines product innovation, inventory management and distribution. Its direct-to-consumer and wholesale channels serve different purposes. Improving one channel at the expense of customer reach or retailer relationships may not improve the overall business.
A convincing turnaround would show products selling at healthy prices, inventories matching demand and distribution choices supporting profitable growth. Lower expenses can lift earnings temporarily, but they cannot substitute indefinitely for footwear and apparel that customers want.
Investors researching stocks with massive upside potential should distinguish renewed demand from easier comparisons against a weak period. Revenue growth becomes more convincing when it arrives without heavier promotions or a buildup of unsold goods.
What to monitor: Follow inventory relative to sales, gross margin, promotional activity and performance across product categories and geographies. Read management's explanation of channel changes rather than treating all direct or wholesale growth as equally valuable.
Valuation discipline: Estimate earnings under a reasonable margin recovery, then test a slower version. Avoid combining peak margins with an unusually generous earnings multiple. That effectively counts the same optimism twice.
What breaks the thesis: Market-share pressure persists, new products fail to gain traction or inventory repeatedly requires discounting. A brand's historical strength is useful evidence, but it is not proof that customer preferences will reverse.
3. Estée Lauder: separate inventory repair from genuine growth
Estée Lauder offers a different consumer turnaround framework: the interaction between prestige beauty demand, travel retail, geographic exposure and distribution inventory. These channels can amplify a slowdown when retailers reduce orders while also working through existing stock.
A recovery in shipments would not, by itself, prove that consumer demand has recovered. Where disclosed, sell-through to end customers provides a useful check on shipments into the channel. Sustainable improvement should eventually appear in cash generation, not just reported revenue.
The appeal of stocks with massive upside potential can be strongest when depressed earnings make the operating recovery look dramatic. For Estée Lauder, the key question is how much of that earnings rebound would come from healthier demand versus temporary inventory effects and expense reductions.
What to monitor: Examine organic sales, geographic trends, operating margins and inventory movements. Review debt maturities and interest expense alongside working-capital needs. A recovery that requires additional borrowing deserves a different valuation from one that funds itself.
Valuation discipline: Build normalized earnings from plausible sales and margins. A price-to-earnings ratio based on unusually weak earnings can look expensive, while one based on an aggressive recovery forecast can look misleadingly cheap.
What breaks the thesis: Brand demand remains weak, promotional pressure persists or channel replenishment fails to produce durable cash flow. Estée Lauder's Upside profile can add community ownership context to the fundamental research, but ownership alone does not validate the recovery.
4. Boeing: delivery reliability matters more than backlog headlines
Boeing's recovery framework is operational and financial. Aircraft orders indicate customer demand, but orders do not create the same financial outcome as producing, delivering and collecting payment for aircraft reliably.
A credible recovery requires manufacturing quality, supplier coordination and regulatory compliance to improve together. Faster production is not automatically positive if it creates additional rework or quality problems. Investors need evidence that deliveries can grow without undermining the process that supports them.
Boeing illustrates why stocks with massive upside potential can also carry substantial financing risk. Delayed deliveries can absorb cash while debt service, supplier obligations and other commitments continue. Customer advances support working capital, but they also accompany obligations to deliver aircraft.
What to monitor: Track deliveries, operating cash flow, production-related disclosures and liquidity. Read the explanations for cash-flow changes, especially movements in inventory and customer advances. One favorable quarter may reflect timing rather than a durable improvement.
Valuation discipline: Separate the value of the operating business from the value left for common shareholders after net debt and other relevant claims. Any new equity issuance also changes the recovery value per share.
What breaks the thesis: Recurring quality issues, prolonged regulatory constraints or financing needs prevent operating progress from reaching shareholders. Use Boeing's Upside profile to compare ownership context, then verify the operating case through company filings.
5. Intel: demand proof that investment can earn acceptable returns
Intel's turnaround framework combines product competitiveness with manufacturing execution. Semiconductor manufacturing requires substantial spending before the resulting capacity generates revenue. That makes timing, utilization and customer economics central to the investment case.
The relevant question is not simply whether Intel can produce more advanced chips. It is whether manufacturing progress, product demand and external customer business can eventually justify the capital committed. Technical milestones matter, but commercial returns determine shareholder value.
Among these stocks with massive upside potential, Intel presents a particularly capital-intensive recovery framework. Government support or strategic funding, where available, can affect financing needs, but neither establishes that a manufacturing investment will be profitable.
What to monitor: Examine capital expenditure, operating cash flow, segment disclosures and evidence of customer adoption. Distinguish announced capacity or customer interest from recognized revenue and an economically attractive production business.
Valuation discipline: Use scenarios that allow for delays, additional investment and changing share counts. A near-term earnings multiple can obscure both heavy spending requirements and the uncertainty around eventual returns. Check whether the recovery requires more financing before it becomes self-sustaining.
What breaks the thesis: Manufacturing milestones fail to translate into competitive economics, utilization disappoints or funding needs dilute shareholders faster than enterprise value grows. This framework calls for patience measured in years, but a long horizon should not become an excuse to ignore missed milestones.
How to value stocks with massive upside potential
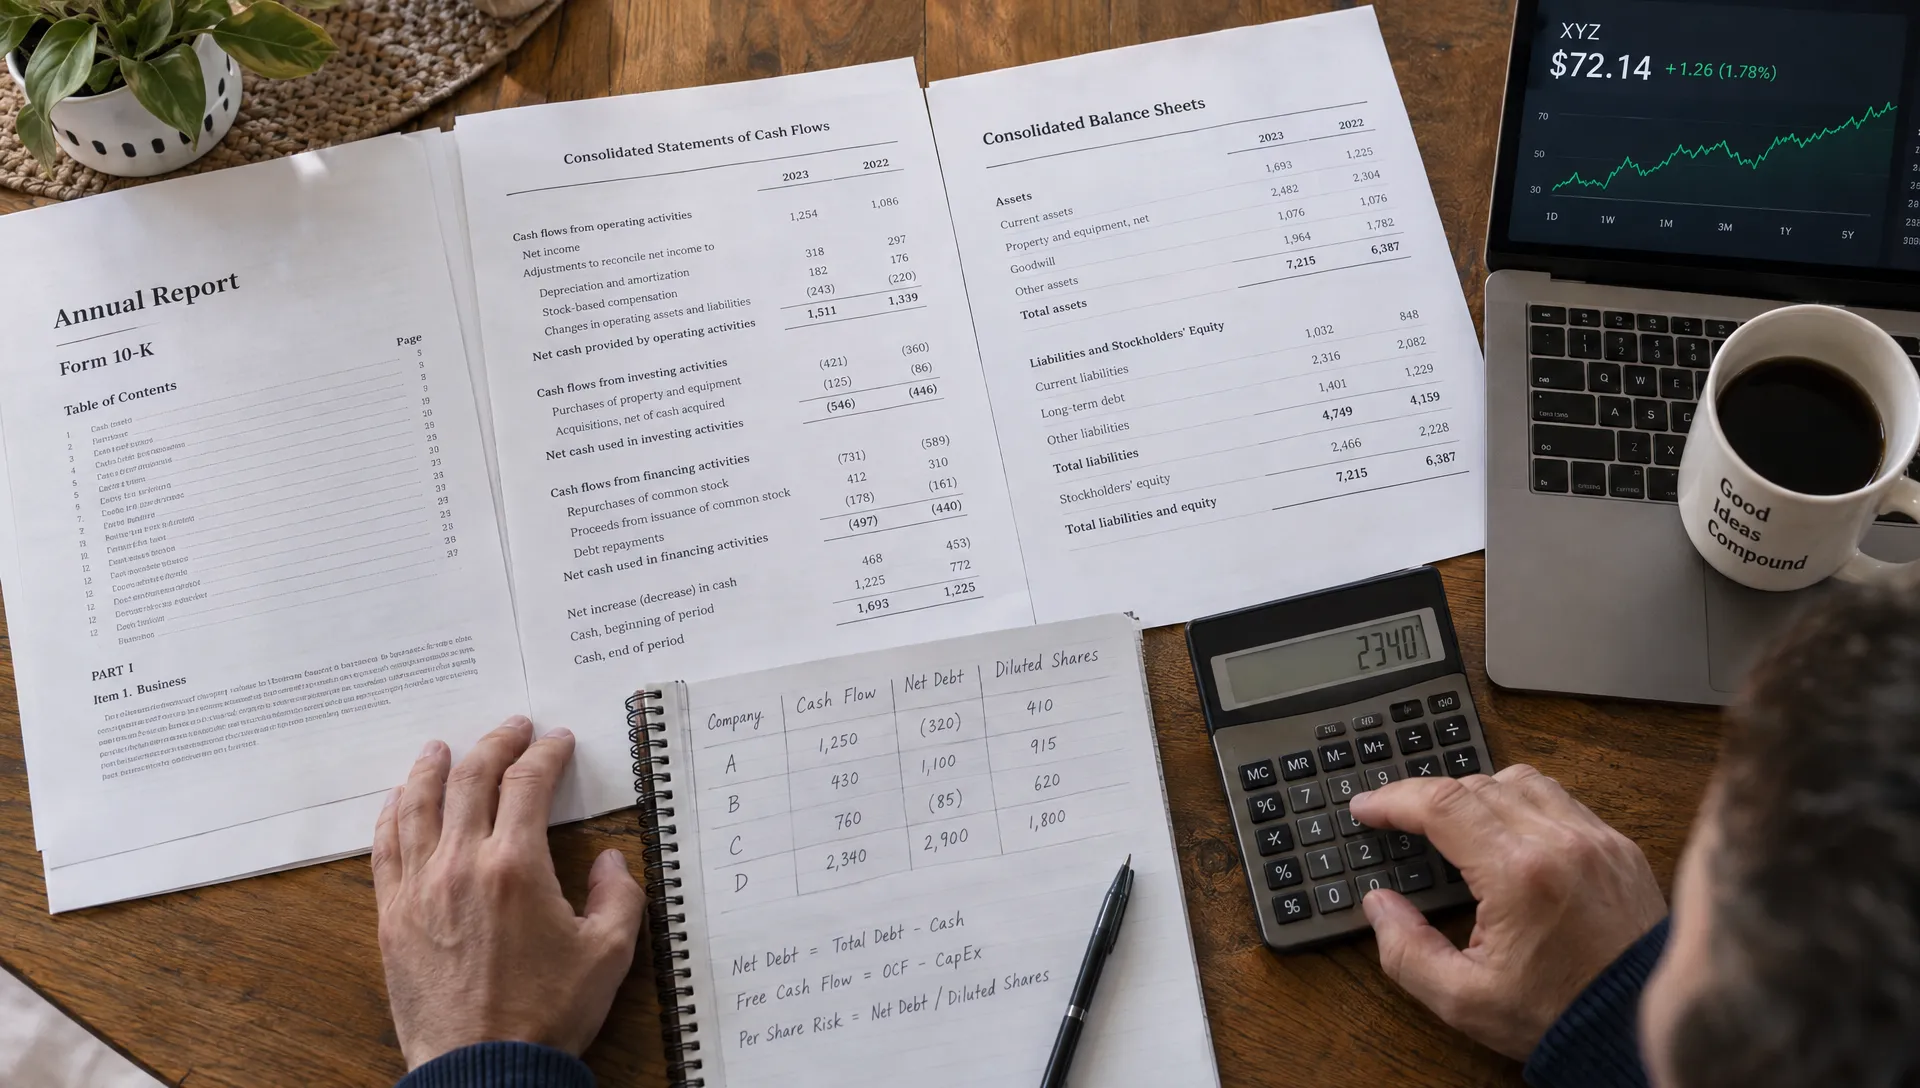
Translate the recovery story into per-share outcomes before estimating upside. A useful starting point is normalized earnings after interest and taxes, supported by a separate cash-flow check.
Consider a purely hypothetical company trading at $8 with 500 million diluted shares:
| Scenario | Normalized annual net income | Earnings multiple | Implied price per share | Change from $8 |
|---|---|---|---|---|
| Bear | $250 million | 8 times | $4 | -50% |
| Base | $500 million | 12 times | $12 | +50% |
| Bull | $750 million | 16 times | $24 | +200% |
These are illustrations, not targets for any company in this article. The spread shows how both operating assumptions and investor sentiment influence the outcome.
Next, challenge the model. Can the company reach those earnings without issuing more shares? Does cash generation support reported profit after necessary investment? Would refinancing raise interest costs? How long would the recovery take?
A 50% gain over five years is approximately an 8.4% annualized return before dividends, taxes and fees. That may be inadequate compensation for a substantial risk of permanent loss. Compare the opportunity with a diversified alternative rather than judging it only against the stock's previous high.
Why analyst price targets are not a substitute for this work
Analysts commonly derive targets from earnings or cash-flow multiples, discounted cash-flow models or separate valuations of business divisions. Each method depends on assumptions about growth, margins, financing and the valuation investors may accept.
For stocks with massive upside potential, small assumption changes can produce large target revisions. A delayed recovery can reduce expected cash generation, increase borrowing needs and lower the appropriate multiple simultaneously.
Price targets also have a time horizon, often around 12 months, that may not match a multiyear turnaround. A consensus average can conceal wide disagreement or estimates that have not yet incorporated new information.
Instead of asking only how far the target sits above the share price, identify the operating assumptions behind it. Then compare those assumptions with your bear and base cases. A target offers a useful research input only when you understand what must happen to justify it.
Manage the risks that a recovery story can hide
Debt and dilution deserve particular attention. Equity holders receive the residual value after other claims, so an improving business can still produce a poor shareholder outcome if expensive financing absorbs the benefit.
Correlated exposure is another trap. Owning several companies does not necessarily diversify a turnaround portfolio. Consumer weakness, tighter credit or rising financing costs could hurt multiple positions together.
When evaluating stocks with massive upside potential, set operating review triggers rather than relying exclusively on a price threshold. Examples include repeated margin deterioration, a worsening liquidity outlook or financing that materially changes the per-share valuation. A lower price does not automatically strengthen the thesis.
Keep household financial distress separate from speculative investing. If debt or foreclosure pressure is driving the search for a quick recovery trade, address those obligations first. For readers in New York or Connecticut, bankruptcy and consumer-debt counsel at Clair Gjertsen Weathers PLLC may be relevant to that separate legal problem; a turnaround stock is not a reliable rescue plan.
Frequently asked questions
Can a turnaround stock rise tenfold? It can, but that is an exceptional outcome, not a reasonable default assumption. A tenfold thesis needs a defensible path to dramatically greater per-share value after debt, reinvestment and possible dilution. A low share price alone provides no such path.
How long should a turnaround take? Use the company's operating milestones rather than a universal deadline. Inventory repair may become visible sooner than a manufacturing overhaul. Set review dates and distinguish ordinary quarterly volatility from repeated failures that undermine the original thesis.
How do you distinguish stocks with massive upside potential from value traps? Look for measurable operating improvement, sufficient financial runway and a purchase price supported by conservative assumptions. A value trap often requires repeated excuses, new financing or a return to historical profitability that customer demand no longer supports.
Should you buy because successful investors own the stock? No. Their entry price, position size, hedges and time horizon may differ from yours. Portfolio data can generate research questions, but another investor's ownership does not establish fair value or make a concentrated position appropriate.
Turn the watchlist into a repeatable research process
Choose the recovery thesis you can explain and measure most clearly. Write down its milestones, financing needs, valuation range and failure conditions before committing capital.
Use Upside's verified portfolio comparisons to examine how investors allocate around a candidate and assess your own concentration. Treat community holdings as additional context, then let current filings and conservative per-share economics determine whether the stock belongs in your portfolio.