5 Stocks With the Highest Upside Potential From Analyst Targets
A search for stocks with the highest upside potential often starts with a simple calculation: compare a share price with an analyst’s price target. But the biggest gap does not automatically identify the best investment. It can also reveal stale forecasts, financial stress or unusually optimistic assumptions about a business recovery.
Micron, Boeing, Estée Lauder, Dexcom and PayPal offer five different investment theses to test against analyst targets. These are research candidates, not a verified ranking of today’s five largest upside opportunities. Current quotes, consensus targets and analyst coverage counts have not been verified for this article, so no present-day upside percentages are claimed.
The useful question is whether each company’s operating performance can support the valuation analysts assign to it. That requires checking growth, cash generation, competitive advantages and downside risk, then deciding whether the potential reward fits your existing portfolio.
How to screen stocks with the highest upside potential
Calculate price-target upside consistently:
Implied upside (%) = (Analyst target ÷ Current share price − 1) × 100
For illustration only, a $140 target against a $100 share price implies 40% upside. It does not imply a 40% expected return or a 40% probability of success. Dividends, taxes and trading costs are also excluded from that calculation.
Before comparing companies, collect these inputs from a consistent source:
| Input | What to check | Why it matters |
|---|---|---|
| Share price | Same closing date for every stock | Different dates distort comparisons |
| Consensus target | Mean or median, clearly identified | One aggressive estimate can pull up the mean |
| Coverage | Number of contributing analysts | Thin coverage makes consensus less representative |
| Target range | Low, median and high estimates | Wide dispersion reveals disagreement |
| Report dates | Revisions following material news | Old targets may ignore changed conditions |
| Forecast horizon | Horizon stated in the research | A longer-term target is not directly comparable with a shorter-term one |
Analysts can also face conflicts involving their employers’ business relationships. The SEC’s discussion of analyst recommendations and potential conflicts explains why research should be evaluated rather than accepted at face value.
1. Micron Technology (NASDAQ: MU)
Micron is a candidate to examine when screening stocks with the highest upside potential because memory-industry earnings can change sharply across the cycle. Analyst valuations depend on assumptions about memory pricing, product mix and demand from data centers, PCs and mobile devices.
Growth, valuation and competitive position
High-bandwidth memory used in AI systems provides an important area to investigate. The investment case depends on whether higher-value products produce durable profits after accounting for manufacturing investment, depreciation and competitive supply additions.
Scale, technical expertise and customer qualification requirements create barriers to entry. They do not eliminate cyclicality. A low forward price-to-earnings ratio can be misleading if the denominator reflects earnings near a cyclical peak.
Use Micron’s security profile on Upside to add portfolio ownership context to your fundamental research, rather than treating other investors’ positions as confirmation of an analyst forecast.
What could support or break the thesis
Bull case: Favorable memory pricing and a richer product mix lift margins and cash generation. Base case: Demand grows, but capital spending absorbs a meaningful portion of operating cash flow. Bear case: Additional industry supply weakens pricing before investors recover the cost of expansion.
Reassess the thesis after earnings, especially when inventory levels, capital expenditure guidance or pricing commentary changes.
2. Boeing (NYSE: BA)
Boeing requires a different framework: production execution, aircraft deliveries and balance-sheet repair matter more than a simple revenue-growth forecast. Its backlog and position in commercial aerospace provide a business foundation, but orders do not become cash until contractual and delivery conditions are met.
A place among stocks with the highest upside potential would need support from credible cash-flow improvements, not merely a return to a historical share price.
Growth, valuation and competitive position
Aircraft manufacturing has substantial technical, certification and supply-chain barriers. Those advantages coexist with demanding safety obligations and significant execution risk.
Compare analyst targets with their underlying delivery assumptions, operating margins and debt forecasts. When earnings are depressed, a conventional earnings multiple can be unhelpful. Normalized free cash flow may offer a better lens, provided the normalization assumptions are realistic.
The ownership information on Boeing’s Upside profile can supplement that analysis without resolving the operating risks.
What could support or break the thesis
Bull case: More reliable production and deliveries improve cash conversion. Base case: Operations recover unevenly while debt reduction limits financial flexibility. Bear case: Quality problems, supplier constraints or regulatory restrictions delay recovery and increase financing needs.
Review the investment after material safety developments, production updates or changes to liquidity guidance. An unchanged price target is not reassuring if its operating assumptions have become outdated.
3. Estée Lauder (NYSE: EL)
Estée Lauder represents a branded-consumer recovery thesis. Its portfolio includes established beauty brands, but brand recognition alone does not establish that a depressed share price is undervalued.
For investors comparing stocks with the highest upside potential, the central distinction is between a temporary earnings setback and a lasting reduction in a company’s earning power.
Growth, valuation and competitive position
Investigate demand across key markets, travel retail exposure, inventory levels and the effectiveness of product launches. The quality of a recovery matters: sales supported by heavy promotions may contribute less to profits than the headline growth suggests.
Analyst targets may assume both an earnings recovery and a higher valuation multiple. Separate those assumptions. A stock can deliver improving profits yet disappoint investors if its multiple remains below the level used in optimistic models.
Brand equity, distribution and product development can support competitive advantages. Changing consumer preferences and strong competitors can weaken them.
What could support or break the thesis
Bull case: Stronger demand and operating leverage rebuild margins. Base case: Sales stabilize, but marketing investment and restructuring costs slow earnings improvement. Bear case: Market-share losses or persistent discounting suggest the former profitability level is no longer attainable.
Revisit the thesis when regional sales trends, gross margins or inventory figures diverge from the recovery assumptions behind analyst targets. Avoid treating a previous peak valuation as a default destination.
4. Dexcom (NASDAQ: DXCM)
Dexcom offers exposure to continuous glucose monitoring. Evaluating it alongside stocks with the highest upside potential requires separating the size of the healthcare opportunity from the returns shareholders can earn at a particular purchase price.
Growth, valuation and competitive position
The operating questions include patient adoption, reimbursement, product reliability and competitive positioning. Recurring sensor use is an important feature of the business model, but investors still need to examine customer retention, pricing and the cost of reaching additional users.
A growth-company valuation can be sensitive to small changes in long-term revenue or margin assumptions. Compare any analyst target with the sales growth, operating profitability and valuation multiple required to reach it.
International expansion also involves more than finding customers. OMC Medical’s overview of medical device regulatory support identifies relevant diligence topics, including registration, technical documentation and post-market vigilance. These obligations can affect commercialization costs and timing.
What could support or break the thesis
Bull case: Broader adoption combines with attractive unit economics. Base case: Growth continues, but competition and commercial investment restrain margin expansion. Bear case: Pricing pressure, reimbursement changes or product issues undermine the earnings trajectory.
Reassess following material product developments, reimbursement decisions or changes in growth guidance. Healthcare demand does not make an individual medical-device stock low risk.
5. PayPal (NASDAQ: PYPL)
PayPal is a candidate for examining whether a lower valuation reflects excessive pessimism or a genuine deterioration in competitive economics. Its payments activities must be assessed in a market containing card networks, digital wallets, merchant platforms and other checkout options.
A screen for stocks with the highest upside potential can misread this type of business if it focuses on an analyst target without examining the profitability of the transactions supporting it.
Growth, valuation and competitive position
Transaction volume is not interchangeable with shareholder value. Examine transaction profitability, branded checkout performance, operating expenses and free cash flow together.
Buybacks can improve per-share results, but their benefit depends on purchase prices and the extent to which repurchases offset stock-based compensation. A shrinking share count cannot indefinitely compensate for weakening business economics.
Analyst targets deserve particular scrutiny when they assume both stronger operating performance and renewed enthusiasm for the stock. Test whether the investment still works if the valuation multiple stays unchanged.
What could support or break the thesis
Bull case: Better transaction economics and disciplined spending drive durable per-share cash-flow growth. Base case: Cash generation remains useful, but competition limits valuation expansion. Bear case: Pressure on checkout economics and margins outweighs cost reductions or repurchases.
Review the thesis after earnings, focusing on the relationship between payment activity, transaction profitability and cash generation rather than any single headline metric.
Compare the downside before choosing a position
Ranking stocks with the highest upside potential by target gaps alone leaves out the cost of being wrong. A speculative recovery with substantial financing risk is not directly comparable with a profitable business facing a temporary slowdown.
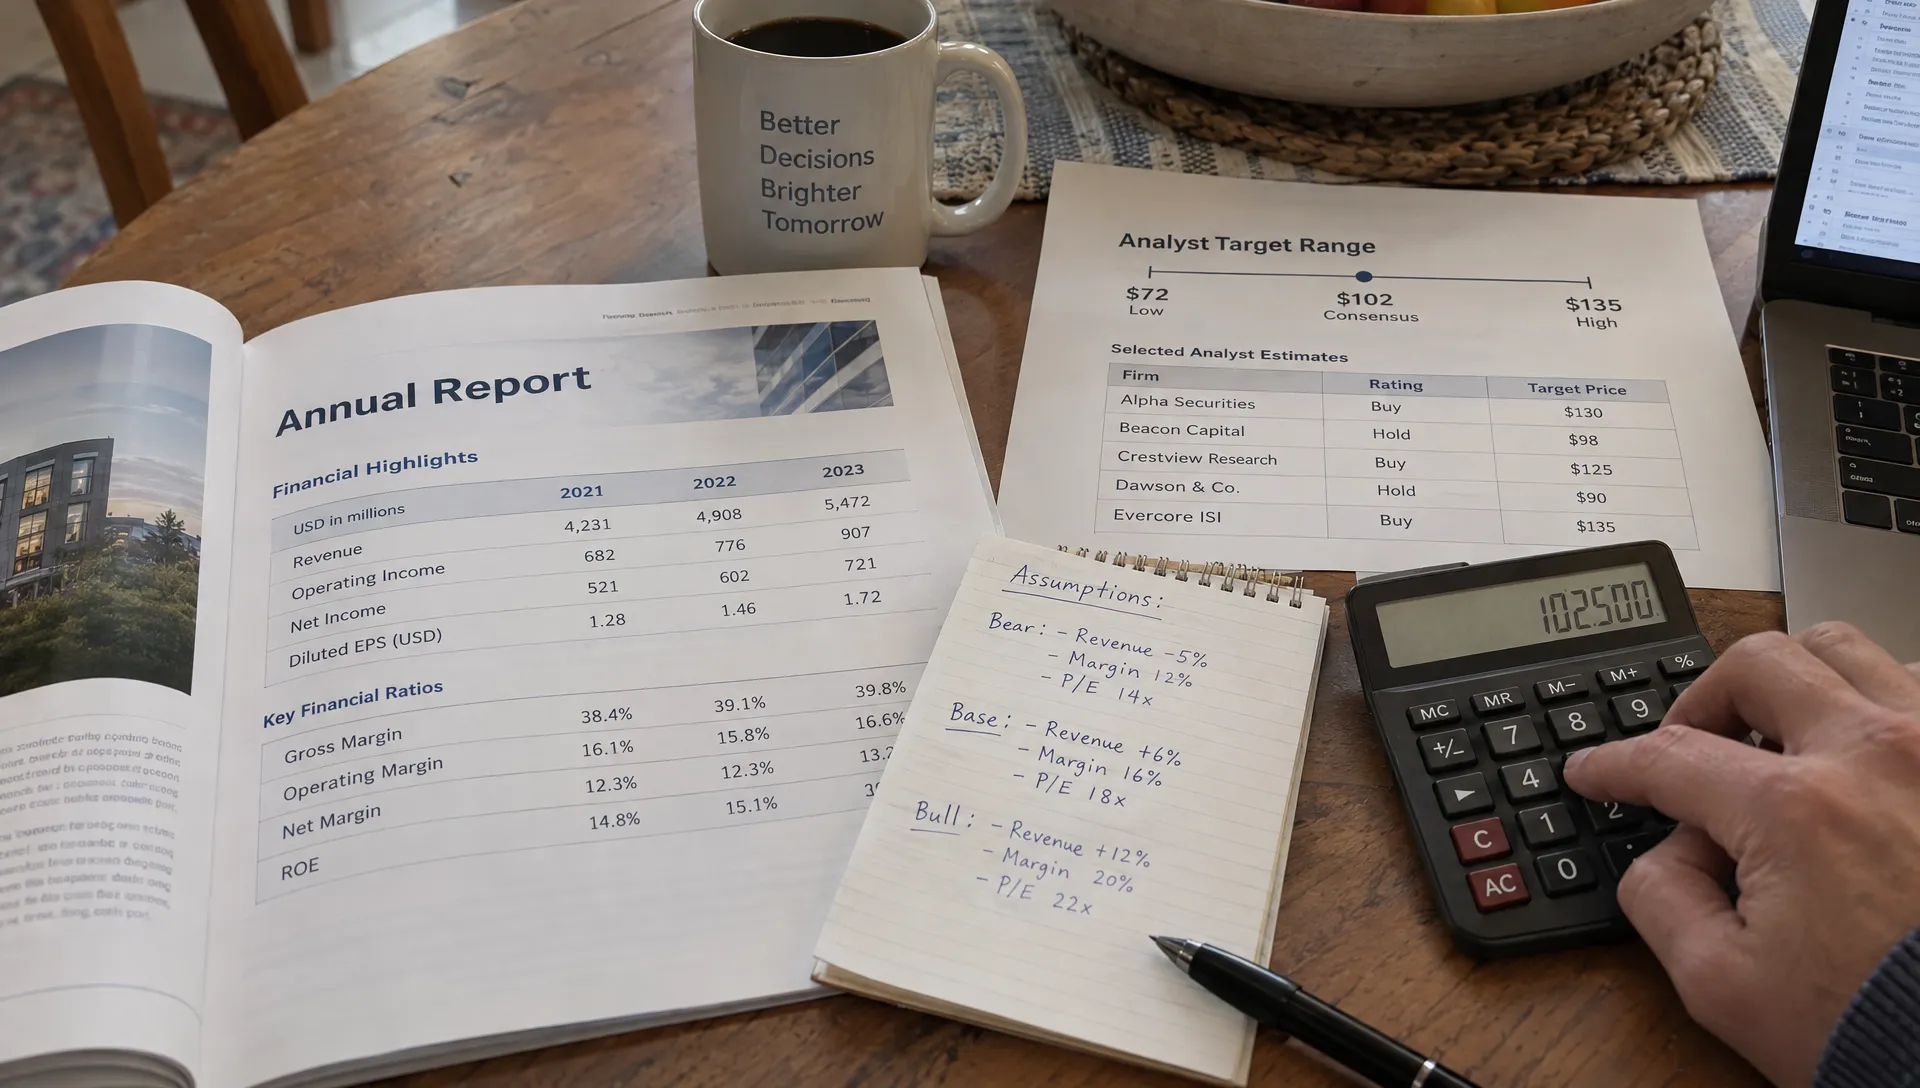
Build your own bear, base and bull valuations using explicit assumptions. Record the revenue outlook, sustainable margin, debt position and valuation multiple behind each scenario. Keep those scenarios separate from published analyst targets so you can distinguish your judgment from someone else’s forecast.
Consider portfolio overlap as well. Micron can increase semiconductor-cycle exposure, while Boeing adds manufacturing and execution risk. Estée Lauder introduces consumer-demand and brand-recovery assumptions. Dexcom adds medical-device growth and reimbursement considerations, while PayPal brings payments competition and margin sensitivity.
Different sectors do not guarantee independent returns. All five can be affected by changing interest rates, weaker growth or declining investor willingness to pay for uncertain future profits.
For investors who need money soon, an uncertain equity recovery may be unsuitable regardless of the target gap. A multiyear horizon offers more time for a thesis to develop, but it does not prevent permanent capital loss.
Keep a dated research record
Save the share price, target source, coverage count and report dates each time you run the screen. Document what must happen operationally for each target to make sense.
Refresh the analysis after earnings, major financing announcements, material regulatory decisions or significant target revisions. Also recalculate following a sharp price move: a strong company can become a less attractive investment when its share price rises faster than its expected earning power.
Frequently asked questions
Are stocks with the highest upside potential the best stocks to buy? Not necessarily. A large target gap can reflect an opportunity, but it can also reflect stale estimates, financial distress or unusually uncertain outcomes. Compare business quality and downside risk before considering a purchase.
Should I use the average target or the highest target? The median can reduce the influence of outliers, while the average remains useful when its methodology is clear. The highest target represents an optimistic view, not a consensus expectation. Examine all three alongside the low target and report dates.
How long should I wait for a target to be reached? Use the horizon stated in the research rather than assuming one. Review business progress along the way. A missed target date is less informative than evidence that the original earnings or valuation assumptions no longer hold.
Add portfolio context to the research
Use Upside’s portfolio comparison tools to compare your allocation with verified investor holdings while maintaining an anonymous profile. That context can help you examine concentration and discover ideas worth investigating, but community ownership and past performance do not validate a price target.
This article is educational, not personalized investment advice. Individual stocks can lose substantial value, including when analysts project significant upside.