Calendar vs. Threshold Rebalancing for DIY Investors
Calendar vs. threshold rebalancing comes down to what triggers a portfolio adjustment: a date or a meaningful change in your investment weights. Calendar rebalancing follows a schedule, such as once a year. Threshold rebalancing acts when an allocation moves outside a predefined range.
Neither method reliably produces higher returns in every market. Their main purpose is to keep your portfolio’s risk aligned with your plan. For DIY investors, the better choice depends on trading costs, taxes, new contributions and how much monitoring you can realistically maintain.
Calendar vs. threshold rebalancing: the practical differences
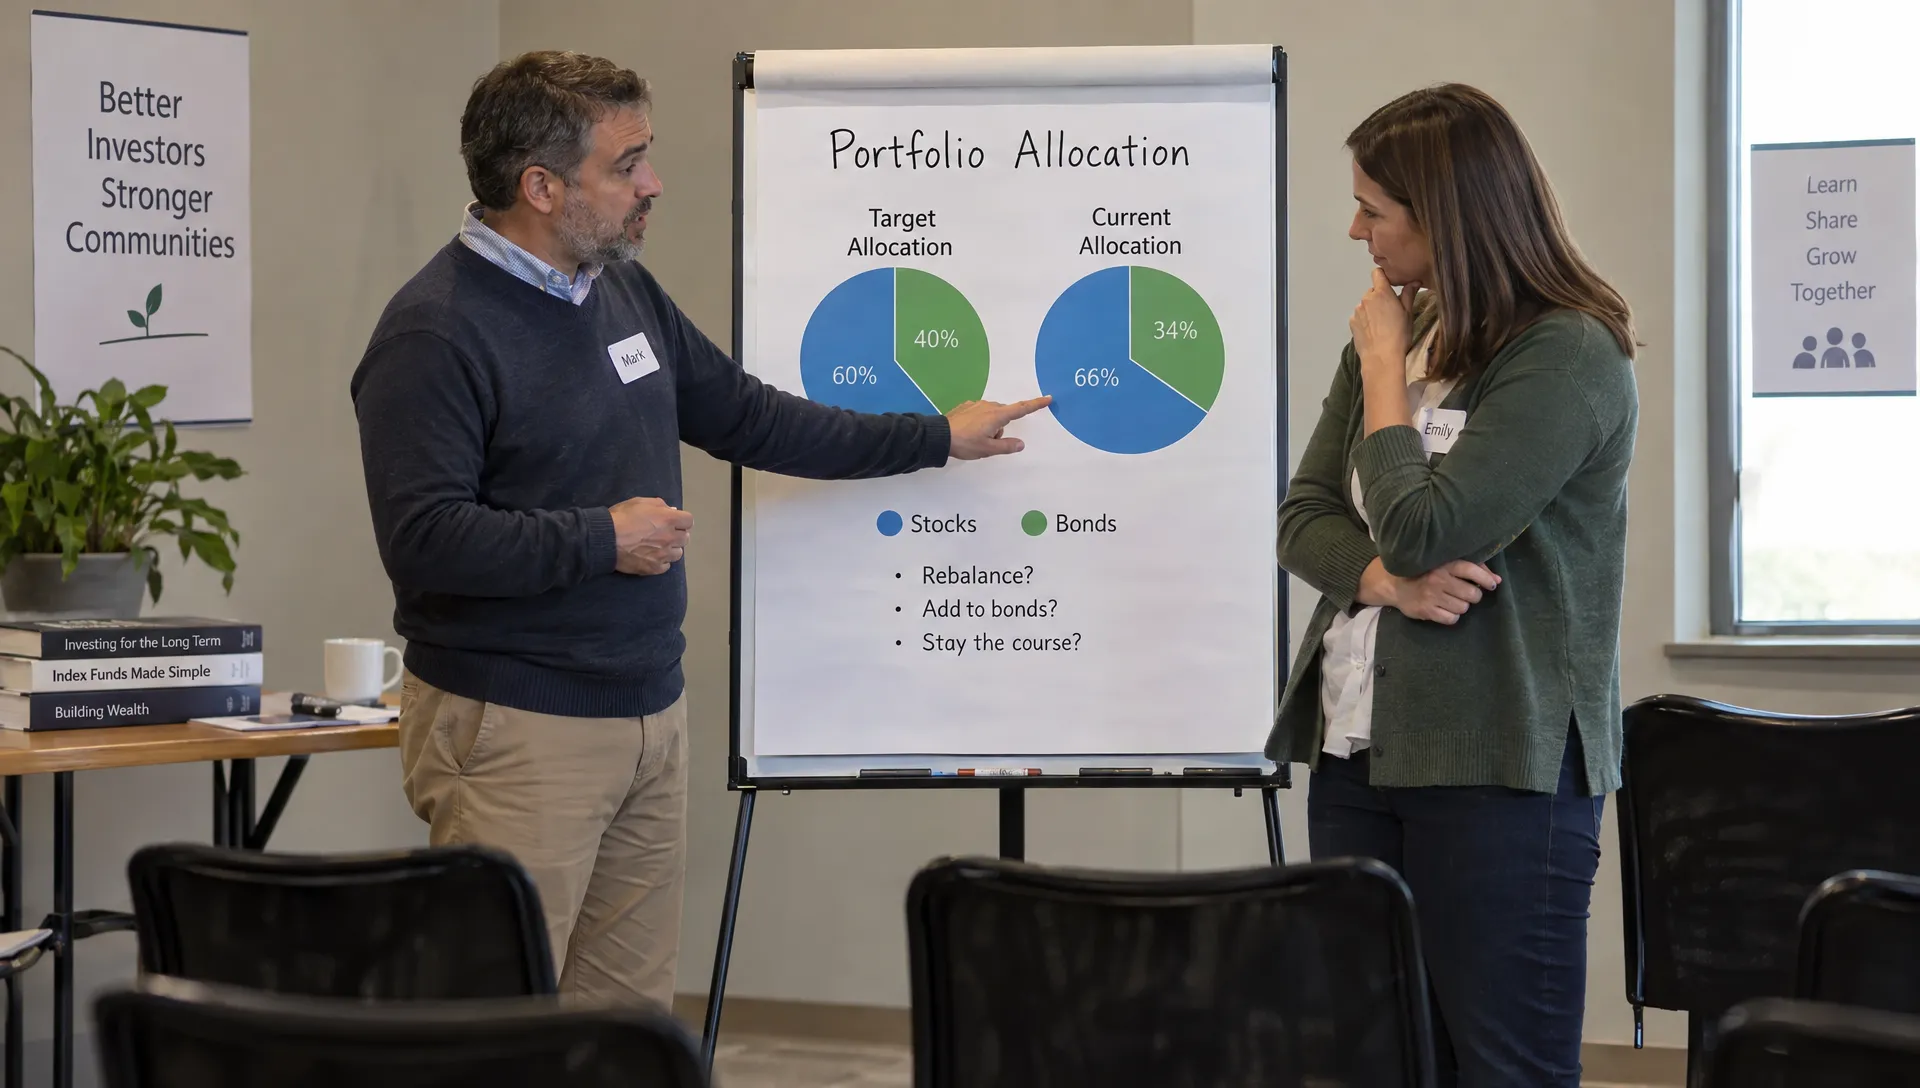
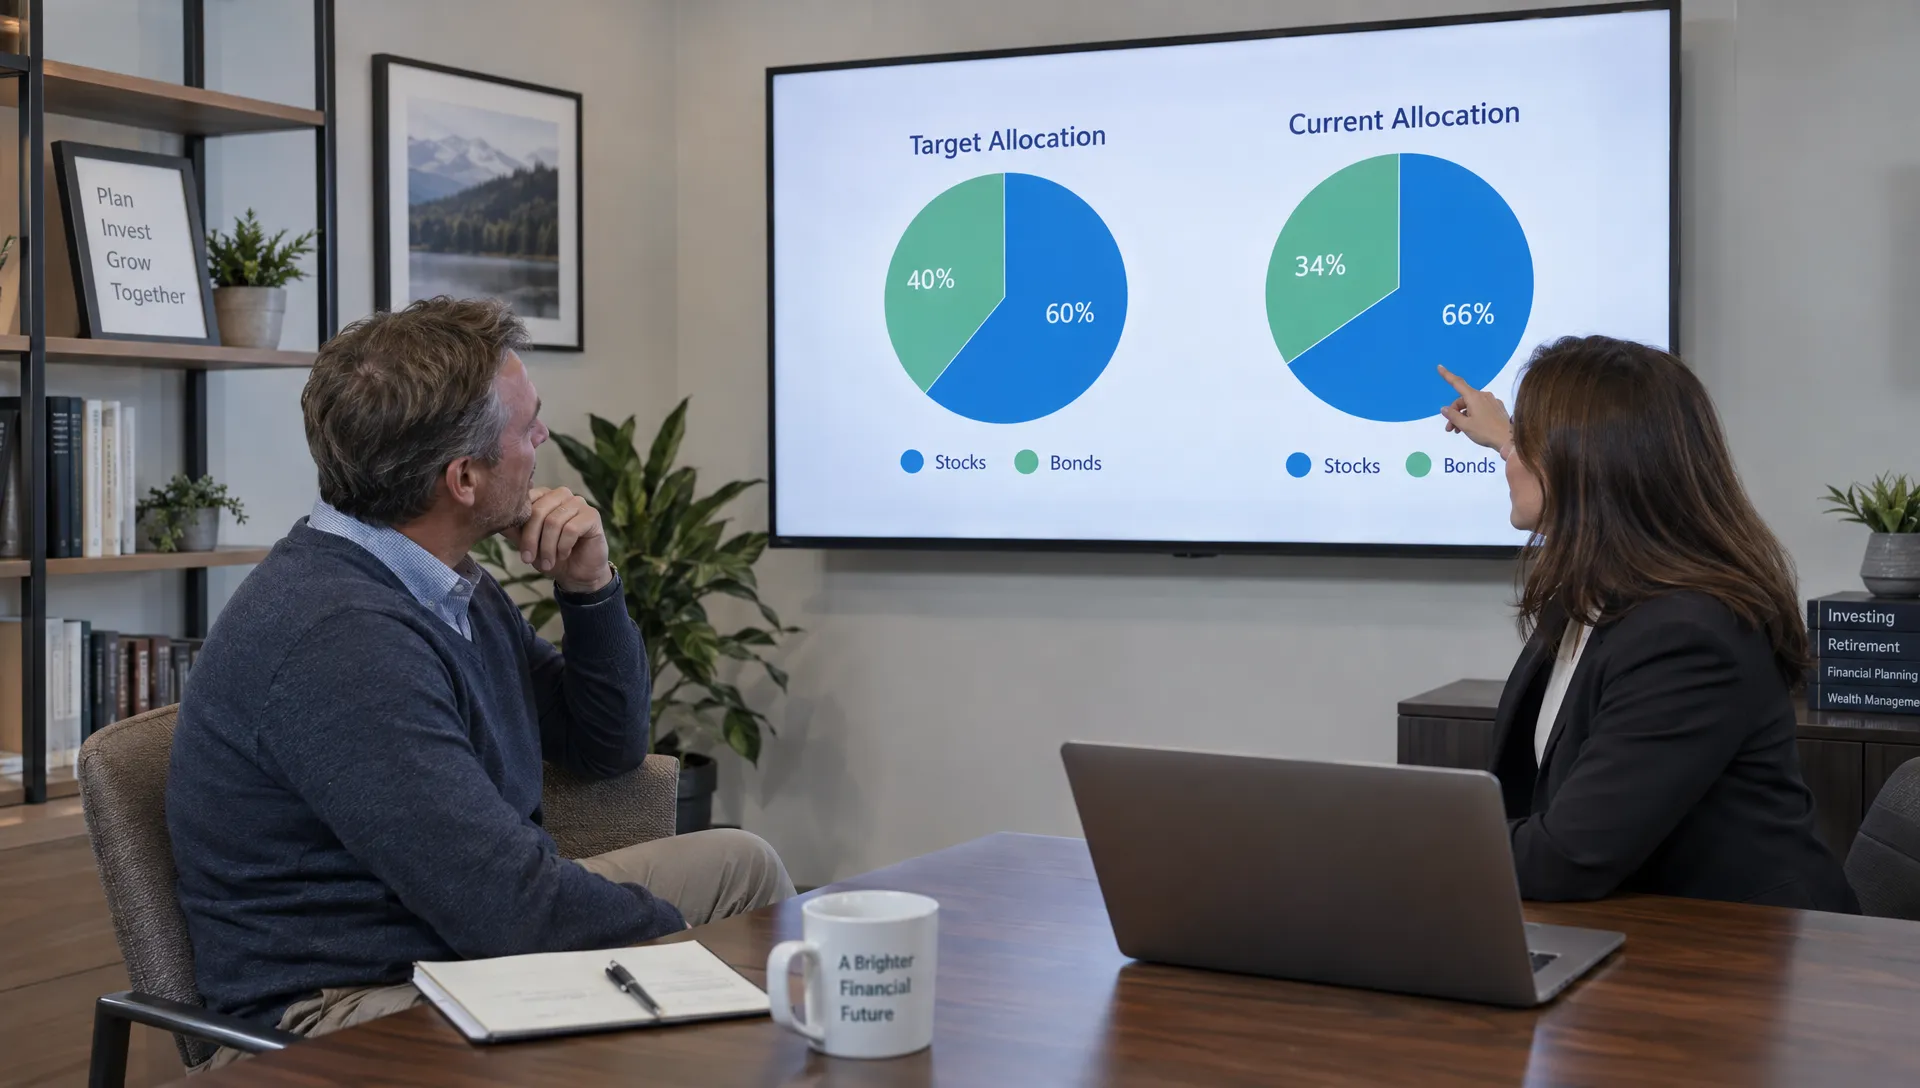
Rebalancing means moving an existing portfolio back toward its target allocation. If your plan calls for 60% stocks and 40% bonds, strong stock returns might push that mix to 66% stocks and 34% bonds. You now have more equity exposure than you intended.
The two methods differ primarily in when they address that drift.
| Decision | Calendar rebalancing | Threshold rebalancing |
|---|---|---|
| Trigger | A scheduled date | An allocation reaches a predefined boundary |
| Example rule | Rebalance every January | Rebalance when stocks reach 55% or 65% around a 60% target |
| Monitoring | Mainly at scheduled reviews | Frequent enough to detect breaches |
| Main advantage | Simple to maintain | Responds directly to allocation drift |
| Main limitation | Drift can grow between dates | Can trigger repeated trades in volatile markets |
| Trading frequency | Predictable opportunities, though trades may be unnecessary | Variable, depending on market movements and the bands chosen |
Both methods need a target allocation first. Neither can determine whether 60/40, 80/20 or another mix is appropriate for your goals.
How calendar rebalancing works
With calendar rebalancing, you select a recurring date, review your holdings and restore the target weights. Annual, semiannual and quarterly schedules are possible choices.
Suppose you rebalance every January. If stocks represent 63% of your portfolio on that date instead of the intended 60%, a strict calendar rule would shift three percentage points from stocks to bonds. If stocks reach 70% in July, however, the same rule would leave the portfolio alone until January.
That trade-off is central: calendar rebalancing prioritizes a repeatable process over a tight limit on allocation drift.
It can suit investors who want few decisions and a review date they can put on a calendar. But more frequent scheduled trading does not automatically improve the outcome. It may simply create more small transactions.
You can add a minimum trade size or tolerance to avoid immaterial adjustments. Once trading also depends on the size of the deviation, though, you have introduced a threshold component rather than following a purely calendar-based rule.
How threshold rebalancing works
Threshold rebalancing starts with an acceptable range around each target weight. You trade when an allocation reaches or passes a boundary, rather than because a particular month has arrived.
For a 60% stock allocation, an illustrative band of five percentage points creates boundaries at 55% and 65%. A move to 64% would not trigger a trade. A move to 66% would.
This connects the decision directly to portfolio drift. It also requires monitoring, whether through manual checks or suitable portfolio analytics. Checking quarterly will not detect every breach that happens between reviews.
Percentage points and relative percentages are different
Write your threshold precisely because a “5% band” is ambiguous.
Around a 60% target, a band of five percentage points creates a range from 55% to 65%. A 5% relative band creates a much narrower range from 57% to 63%, because 5% of 60% is three percentage points.
The distinction becomes especially important for small allocations. Applying a five-percentage-point band to a 5% position creates boundaries at 0% and 10%, allowing its weight to double before reaching the upper boundary.
Relative bands can better reflect proportional changes in smaller positions, but narrow limits can produce frequent triggers. There is no universal threshold that fits stocks, bonds, individual securities and crypto equally well.
Also specify where a trade should leave the allocation. Returning fully to target is simple. Moving only partway back may reduce turnover, but it requires another explicit rule.
A worked example: restoring a 60/40 portfolio
Assume your portfolio is worth $100,000, with a target of 60% stocks and 40% bonds. Market movements have produced the following allocation:
| Asset class | Current value | Current weight | Target value at today’s portfolio size |
|---|---|---|---|
| Stocks | $66,000 | 66% | $60,000 |
| Bonds | $34,000 | 34% | $40,000 |
Ignoring taxes, transaction costs and price changes during execution, you would sell $6,000 of stocks and buy $6,000 of bonds to restore the target.
A calendar policy makes that trade only when its scheduled date arrives. A threshold policy with five-percentage-point bands triggers when the stock allocation reaches 65%, assuming the breach is detected. At 66%, that boundary has already been exceeded.
New contributions can reduce the need to sell
If you have cash available, you may be able to rebalance without selling appreciated investments.
In this example, adding $10,000 entirely to bonds would produce $66,000 in stocks and $44,000 in bonds. The new $110,000 total would be exactly 60/40.
The required contribution is larger than the $6,000 transfer because adding money also increases the portfolio’s total value. A smaller contribution can still reduce the drift, even if it does not fully restore the target.
The same approach works with cash dividends or interest that have not been reinvested. Directing them toward underweight assets can reduce future selling, although those distributions may still have tax consequences.
Account for taxes, costs and trading restrictions
The most precise allocation rule is not necessarily the most practical after implementation costs.
For US investors, selling appreciated holdings in a taxable brokerage account can realize capital gains. The holding period matters for tax treatment, while selling at a loss requires attention to wash-sale rules. The IRS explains these issues in Publication 550, Investment Income and Expenses.
Trading within an IRA generally does not create an immediate capital-gains tax, but account and withdrawal rules still apply. Avoid treating taxable and retirement accounts as interchangeable.
Before selling, consider whether you can direct new money toward an underweight asset or make an offsetting adjustment inside a retirement account. If you manage several accounts as one portfolio, calculate the combined exposure first rather than forcing each account to hold the same mix.
Zero commissions also do not mean zero costs. Bid-ask spreads, currency conversion charges, redemption fees and limited liquidity may affect execution. A narrow threshold can repeatedly trigger trades whose costs outweigh the value of correcting small deviations.
Cross-border portfolios add questions about legal ownership and authority to trade. If Jamaican law is involved, consider discussing those issues with Jamaican law firm Henlin Gibson Henlin before implementing changes. Legal authorization and tax treatment are separate from the allocation calculation.
A practical hybrid policy for DIY investors
A hybrid approach separates when you check from when you trade. You review on scheduled dates but rebalance only when an allocation breaches its permitted range.
Here is an illustrative policy for a two-asset portfolio, not a recommendation that everyone use these targets or bands:
- Set the target: Maintain 60% stocks and 40% bonds across the accounts included in the plan.
- Schedule reviews: Check allocation on the first business day of January, April, July and October.
- Define the trigger: Rebalance if stocks are at or below 55% or at or above 65% during a review.
- Use cash first: Direct available contributions and uninvested distributions toward the underweight asset before selling.
- Define the destination: Return to 60/40, subject to documented tax, liquidity and trading constraints.
This is quarterly monitoring with threshold-triggered trading, not continuous threshold monitoring. Your portfolio can move outside its bands between review dates.
Keep a short record of each decision: observed weights, the trigger, trades made and any reason for a partial adjustment. Review the target allocation separately when your goals, withdrawal needs or capacity for losses change.
Changing a target because your circumstances changed is financial planning. Changing it because a recent winner looks irresistible is a different decision and should not be disguised as rebalancing.
Which method fits your investing habits?
Choose calendar reviews when simplicity matters most
A calendar-led process may fit if you hold a diversified portfolio, prefer limited maintenance and accept that allocation drift can persist between dates. It also creates a predictable opportunity to review contributions, beneficiaries and upcoming cash needs.
Do not assume an annual schedule guarantees low risk. A substantial market move early in the year can leave the portfolio far from target for months.
Choose thresholds when allocation limits matter more
Thresholds may fit if you can monitor consistently and want trading decisions tied to the size of the deviation. They can also support explicit limits on concentrated positions, though the limits should reflect the risks of those holdings.
A threshold is not a stop-loss order. An asset can remain within its allocation band while the entire portfolio loses value. Nor does a breach guarantee that you can trade immediately at the price used in your calculation.
Choose a hybrid when attention is limited
Scheduled checks with threshold-based execution can reduce unnecessary decisions. They provide a clear answer to both “When do I look?” and “What makes me act?” without requiring daily attention.
Keep portfolio comparison separate from your trading rule
Portfolio comparison can reveal differences in concentration, sector exposure or asset mix. It should not silently rewrite your investment policy.
A verified investor’s large allocation to a stock may reflect a different time horizon, tax basis or ability to absorb losses. Strong recent returns do not make that allocation suitable for you.
Use investing insights to identify questions worth researching. If several holdings expose you to the same industry, for example, you may have more concentration than the number of positions suggests. That finding can justify reviewing your policy, but another investor’s trade is not itself a rebalancing trigger.
Apply the same discipline to market momentum. Rebalancing trims relative winners and adds to relative laggards, so it can trail a drifting portfolio during a sustained trend. Its purpose is risk alignment, not consistently beating an unrebalanced portfolio.
Frequently asked questions
Is calendar or threshold rebalancing better? Neither is universally better. Calendar rules are easier to maintain, while thresholds respond to allocation drift. The better fit depends on your monitoring habits, taxes, trading costs and tolerance for deviations.
How often should I check a threshold-based portfolio? Choose a frequency you can sustain and recognize its limits. Monthly or quarterly checks detect breaches only at those times. More frequent monitoring can detect drift sooner but does not automatically justify more trading.
Does rebalancing guarantee higher returns? No. It restores a chosen allocation and may reduce unintended concentration. It can also lower returns relative to letting a strongly performing asset grow unchecked.
Can contributions replace rebalancing sales? Sometimes. Contributions directed to underweight assets may restore the target when cash flows are large enough. As a portfolio grows relative to contributions, sales may become necessary to correct substantial drift.
Write the rule before the next market move
Choose a target, define your review dates and state exactly what triggers a trade. Then test whether you can follow that policy after taxes and costs.
Use Upside’s portfolio comparison tools to put your exposures in context with verified investor holdings. Keep the final rebalancing decision anchored to your own goals and written rules, not someone else’s latest move.