Time-Weighted vs. Money-Weighted Returns for Retail Investors
Time-weighted vs. money-weighted returns answer two different questions: how did your investment strategy perform, and what return did your money experience? The distinction matters whenever you add savings, withdraw cash or compare your results with another investor’s portfolio.
Neither measure is universally better. Use time-weighted return to evaluate investment performance independently of external cash-flow timing. Use money-weighted return to understand your personal outcome, including when you contributed or withdrew money.
Here is how both work, why they can point in opposite directions and how to use them without making misleading comparisons.
Time-Weighted vs. Money-Weighted Returns: The Key Differences
| Feature | Time-weighted return (TWR) | Money-weighted return (MWR) |
|---|---|---|
| Main question | How did the portfolio’s investments perform? | What rate of return did my invested money earn? |
| Effect of external cash flows | Neutralizes their direct effect on the calculation | Reflects their size and timing |
| Typical calculation | Geometrically links returns between cash flows | Solves for an internal rate of return |
| Best use | Comparing strategies, managers or portfolios | Evaluating your personal investing outcome |
| Data needed | Portfolio valuations around external cash flows | Dated contributions, withdrawals and ending value |
| Reporting period | Can be cumulative or annualized | Commonly annualized when calculated using XIRR |
A return percentage is incomplete without its dates, calculation method and treatment of dividends and fees. A cumulative two-year TWR and an annualized MWR are not directly comparable until you put them on the same time basis.
How Time-Weighted Return Works
Time-weighted return breaks your investment history into subperiods separated by external cash flows. It calculates the return for each subperiod, then compounds those returns together.
For an exact calculation, each subperiod begins immediately after an external flow and ends immediately before the next one:
Subperiod return = ending value before the next flow / starting value after the previous flow - 1
The linked return is:
TWR = (1 + r₁) × (1 + r₂) × … × (1 + rₙ) - 1
The method prevents a deposit from looking like an investment gain or a withdrawal from looking like a loss. It also prevents periods with larger balances from dominating the result simply because more money was invested then.
That makes TWR useful for portfolio comparison. Two investors holding the same investments in the same proportions throughout a period can have the same TWR despite making different-sized contributions.
TWR does not ignore investment decisions. If a deposit sits in cash instead of being invested, the portfolio’s cash allocation can affect subsequent performance. The calculation neutralizes the external flow itself, not what happens to the money afterward.
For a professional reference, the Global Investment Performance Standards address calculation and presentation practices for both time-weighted and money-weighted returns.
How Money-Weighted Return Works
Money-weighted return accounts for how much money was invested and for how long. It is typically calculated as an internal rate of return, or IRR.
The calculation finds the rate that balances your contributions against your withdrawals and ending portfolio value. From your perspective, money invested is a negative cash flow. Money received is positive, and the ending account value is treated as a positive terminal amount even if you have not sold the investments.
This means a market decline can have a larger effect on your personal result if it happens after you make a substantial contribution. Conversely, a strong period can benefit you more if you had more money invested during it.
For irregularly dated cash flows, spreadsheet tools commonly use XIRR, which calculates an annualized internal rate of return using actual dates. Standard IRR assumes equally spaced cash flows.
MWR is useful for evaluating the combined effect of investment performance and your funding schedule. However, it is not a pure measure of stock-picking skill. Contributions may reflect payday schedules, a bonus or an inheritance rather than deliberate market timing.
A Worked Example: Positive TWR, Negative MWR
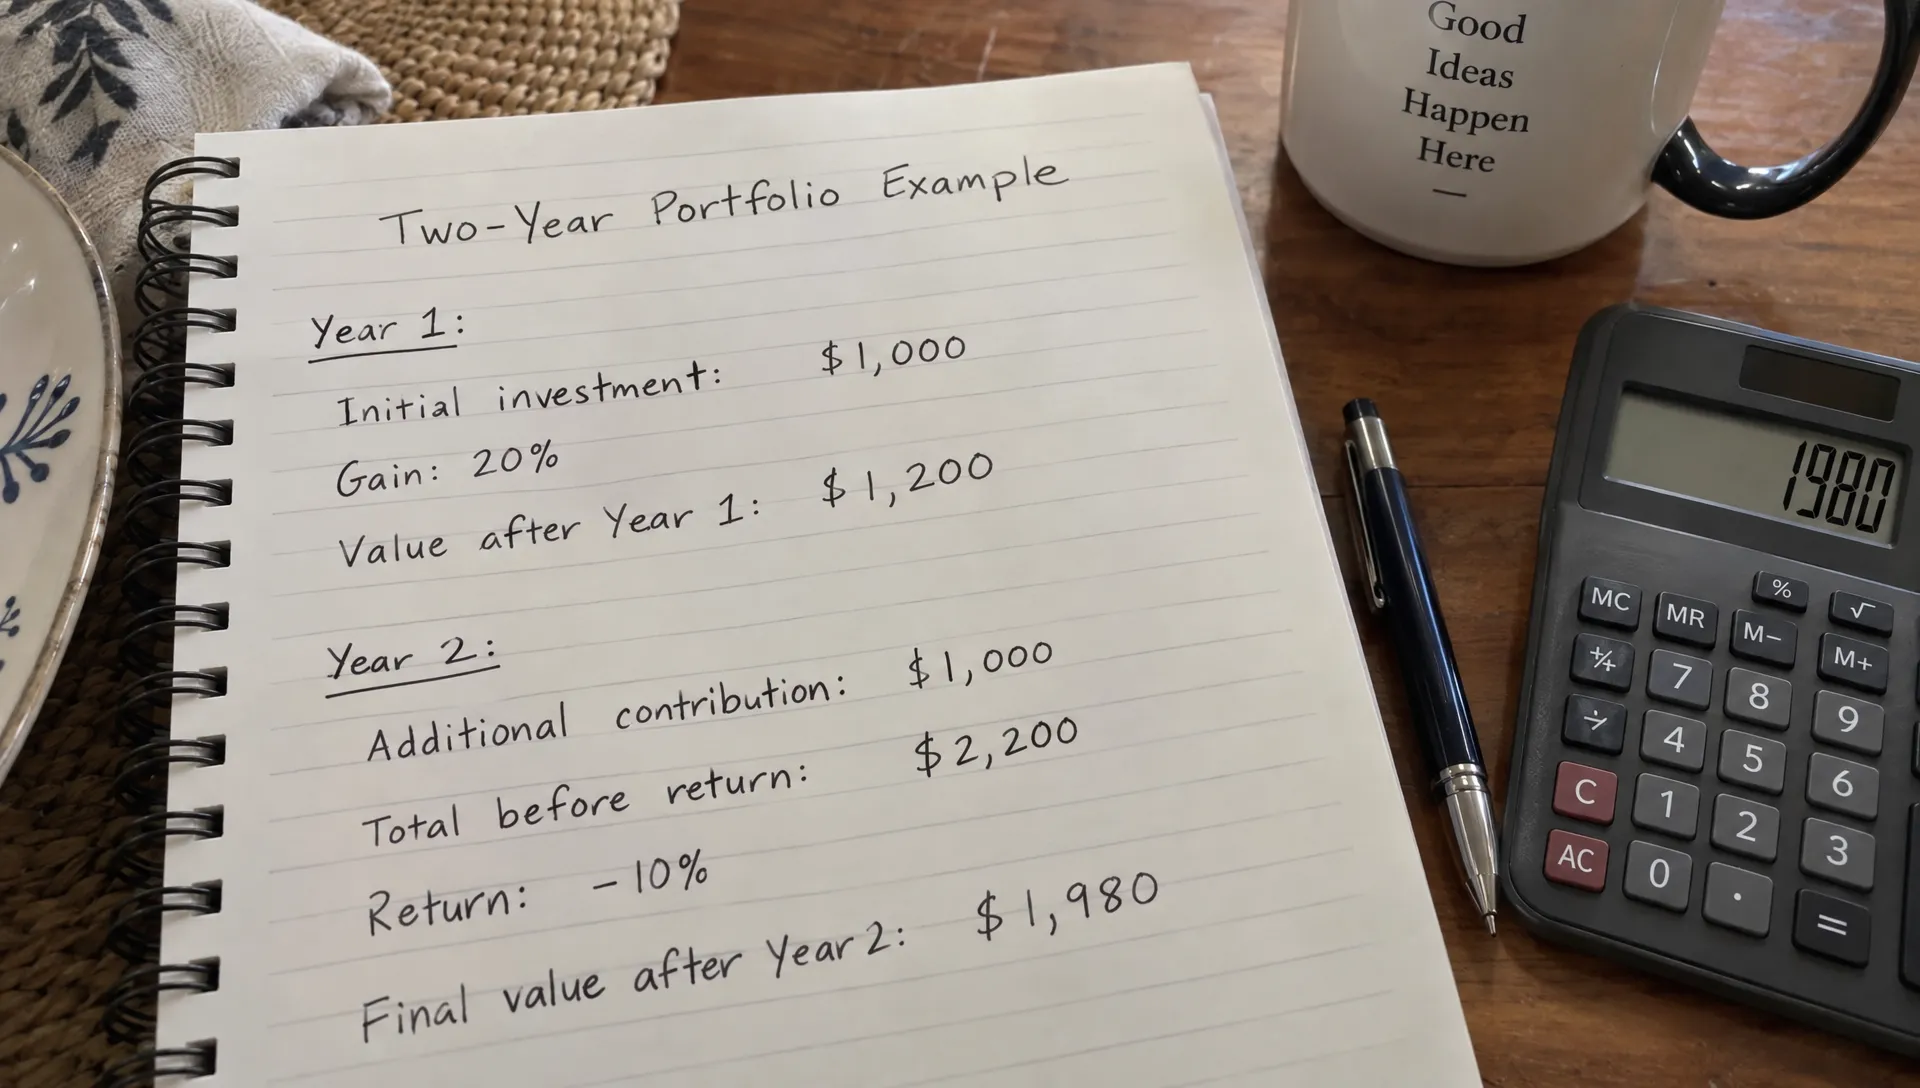
Consider a hypothetical portfolio over two equal one-year periods. Assume there are no fees, taxes or withdrawals.
| Point in time | Event | Portfolio value |
|---|---|---|
| Start of year one | You invest $1,000 | $1,000 |
| End of year one, before contribution | Investments gain 20% | $1,200 |
| Start of year two | You contribute another $1,000 | $2,200 |
| End of year two | Investments lose 10% | $1,980 |
You contributed $2,000 in total and finished with $1,980. Your dollar loss is $20. Yet the portfolio’s linked investment return is positive.
Calculate the Time-Weighted Return
The contribution separates the two annual subperiods:
TWR = (1.20 × 0.90) - 1 = 8%
That is an 8% cumulative return over two years, not 8% per year. Annualizing it gives:
Annualized TWR = 1.08^(1/2) - 1 ≈ 3.92%
The portfolio gained 20% and then lost 10%. Geometrically linking those returns produces a positive result regardless of the contribution’s size.
Calculate the Money-Weighted Return
The investor’s cash flows are $1,000 invested initially, another $1,000 invested one year later and a terminal value of $1,980 after two years.
The annual MWR solves:
0 = -1,000 - 1,000/(1 + r) + 1,980/(1 + r)²
The result is approximately -0.67% per year.
More money was exposed to the second year’s decline than to the first year’s gain. That explains why the annualized TWR is positive while the annual MWR is negative.
Dividing the $20 loss by $2,000 gives -1%, but that simple calculation ignores how long each contribution was invested. It is not the same as an annualized money-weighted return.
How to Calculate Your Own Returns
Start With a Reliable Cash-Flow Record
For MWR, collect every external contribution and withdrawal, each transaction’s date and the portfolio’s ending value on the measurement date. Include the opening portfolio value as an initial negative amount if you are measuring a period that starts after the account was opened.
In a spreadsheet, put dates in column A and investor-perspective cash flows in column B. Contributions should be negative, withdrawals positive and the ending valuation positive on the final date. If you withdraw money on the final date, include that withdrawal as well as any remaining account value.
Then use:
=XIRR(B2:B10,A2:A10)
Adjust the ranges to match your records and format the result as a percentage. Microsoft’s XIRR documentation explains the function’s date and sign requirements.
With unusual cash-flow patterns, an IRR calculation can have multiple solutions or fail to converge. Treat an implausible result as a reason to review the inputs, not as a reliable performance figure.
Use Valuation History for TWR
Exact TWR requires portfolio valuations at external cash-flow boundaries. Contributions and withdrawals alone are not enough.
If your brokerage provides a time-weighted performance report, check its methodology. Without valuations around cash flows, some systems use approximations such as Modified Dietz. Those estimates can differ from exact TWR when flows are large or markets move sharply.
What Counts as an External Cash Flow?
First define the boundary of the portfolio you are measuring. For a single brokerage account, a bank transfer into that account is an external contribution. Selling a stock and leaving the proceeds inside the account is not.
The same distinction applies to withdrawals. For example, a new parent might sell investments to cover childcare or a wearable breast pump. The sale stays inside the portfolio until the money leaves; the withdrawal is the external cash flow.
| Transaction | Typical treatment |
|---|---|
| Bank deposit into the measured account | External contribution |
| Cash withdrawal to a bank account | External withdrawal |
| Stock sale with proceeds kept in the account | Internal transaction |
| Dividend retained or reinvested in the account | Part of investment return |
| Transfer between two accounts measured together | Internal transfer |
| Securities transferred into the measured portfolio | External contribution valued at the transfer date |
Dividends paid out of the account need consistent treatment: recognize the investment income and record the outgoing payment so it is not mistaken for a loss.
Fees also require care. For net-of-fee performance, account-paid investment fees should reduce returns, not be reclassified as ordinary withdrawals that remove their impact. Tax treatment depends on whether you are reporting before-tax or after-tax results.
Which Return Should You Use for Portfolio Comparison?
Compare Strategies With TWR
TWR is generally the more useful starting point when comparing investors whose deposits and withdrawals differ. Align the measurement dates, annualization method and treatment of fees and dividends before comparing percentages.
Also compare risk and allocation. A concentrated stock portfolio and a diversified stock-and-bond portfolio do not represent equivalent risks just because their returns cover the same period.
Verified holdings can help establish what someone owns, but they do not explain every performance calculation. Current holdings alone cannot reveal a complete history of trading, cash flows or prior allocations.
Assess Your Own Experience With MWR
MWR helps you understand the outcome of your actual funding schedule. A gap between your MWR and TWR can highlight the influence of contribution timing, but it does not automatically prove poor decisions.
To compare your MWR with a benchmark fairly, simulate investing the same amounts on the same dates in an appropriate total-return benchmark. Then calculate that hypothetical investment’s MWR. Comparing your MWR directly with an index’s published TWR mixes two different measures.
Finally, distinguish price performance from total return. When assessing an income-focused holding such as AGNC Investment Corp., a share-price change alone does not capture dividend income. Your portfolio calculation must also reflect distributions, cash balances and other holdings.
Frequently Asked Questions
Is money-weighted return more accurate than time-weighted return? Neither is inherently more accurate. MWR measures your cash-flow-dependent investing outcome, while TWR measures portfolio performance after neutralizing external cash flows. Accuracy depends on the inputs and calculation method.
Can TWR be positive when I have lost money? Yes. If you invested relatively little before gains and substantially more before losses, TWR can be positive even though your ending balance is below your total contributions, after accounting for withdrawals.
Does XIRR calculate time-weighted return? No. XIRR calculates an annualized money-weighted return using dated cash flows. Exact TWR requires subperiod returns based on portfolio valuations around external flows.
Which metric is better for retirement savings? Use both alongside your balance and contribution history. MWR describes your personal investing outcome, while TWR helps assess the underlying strategy. Neither measure alone tells you whether you are saving enough to meet your retirement goal.
Make Portfolio Comparisons More Meaningful
Before acting on a performance ranking, check the return method, dates, cash-flow treatment and risk exposure. A strong percentage without that context can lead to the wrong conclusion.
Upside Invest provides verified investor holdings, anonymous profiles and portfolio comparison tools to help you explore allocations and investing behavior. Use those insights alongside clearly defined return measures: TWR for comparing strategies, MWR for understanding your own investing experience.