What Employee Stock Benefits Mean Before You Join
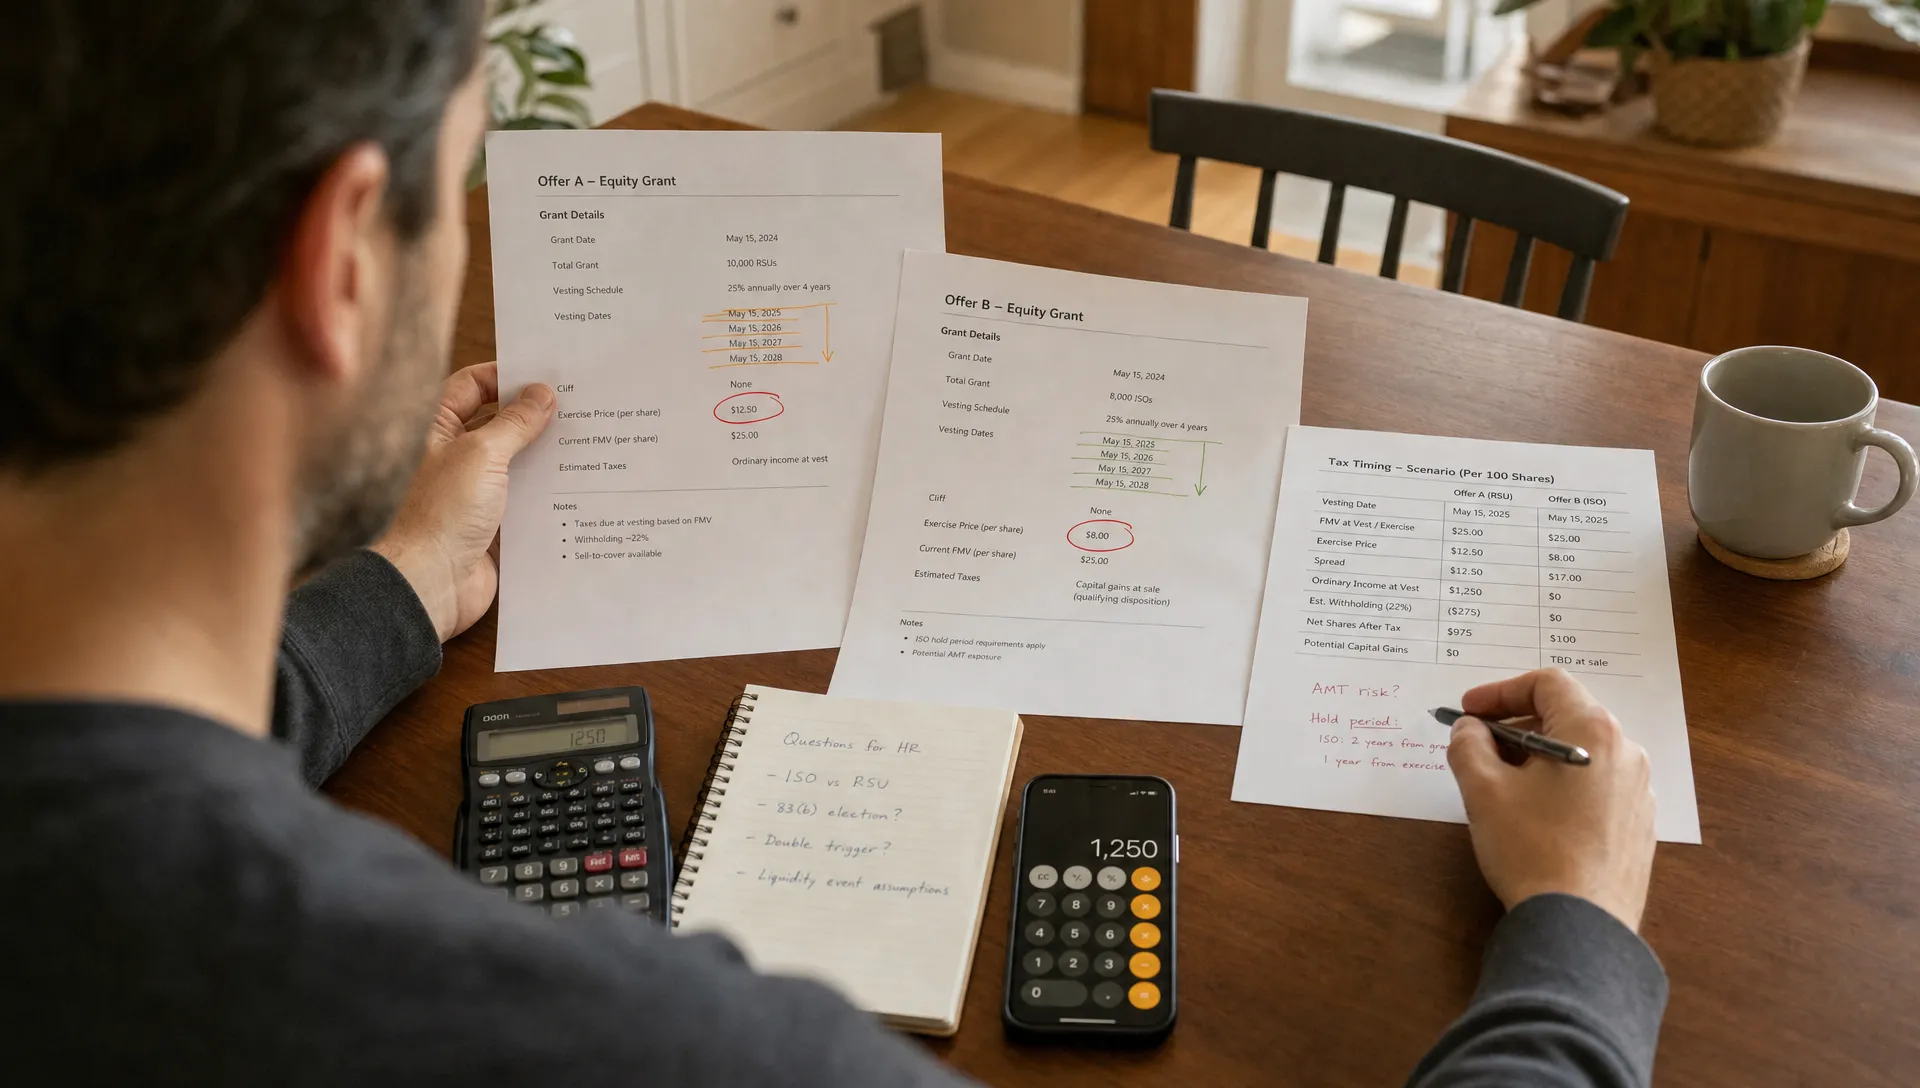
A stock employee benefit can make a job offer look much richer than salary alone, but it can also hide costs, delays and risk. Before you join, your goal is not to predict the company perfectly. Your goal is to understand what you are being offered, when it can become yours, what it might cost to keep and how it fits with your broader financial life.
Equity is usually presented in optimistic language during recruiting. You may hear about upside, ownership culture, future liquidity or alignment with shareholders. Those can be real benefits, but the details in the grant agreement matter more than the headline number. The phrase stock employee benefit can refer to very different arrangements, from RSUs at a public company to options in a venture-backed startup or shares inside an ESOP.
What equity benefits really mean in an offer
Employee stock benefits are compensation tied to a company’s shares or share value. They are not all the same. Some give you actual shares after vesting. Some give you the right to buy shares later. Some sit inside a retirement plan. Some are easy to value because the stock trades publicly, while others depend on private valuations and future liquidity events.
A stock employee benefit should be read as a contract, not a promise of wealth. The offer letter may show a large grant value, but the real economic value depends on vesting, taxes, share price movement, dilution, exercise costs and whether you can sell.
If you want a broader primer on the mechanics across plan types, Upside Invest has a detailed guide on how employee stock ownership really works. For the purposes of deciding whether to join, focus less on labels and more on the practical questions below.
How to evaluate a stock employee benefit before you join
The cleanest way to evaluate equity is to separate it into four parts: what you receive, when you receive it, what it costs and how you can turn it into usable value. Recruiters often emphasize the first part. Candidates need all four.
Start by asking for the plan documents, grant agreement or at least a written summary of terms before you accept. A verbal explanation is helpful, but the documents control what happens if you leave, the company sells, the share price falls or the board changes future grants.
Here is a simplified comparison of common employee equity structures:
| Benefit type | What you receive | Main value driver | Key question before joining |
|---|---|---|---|
| RSUs | Shares after vesting and settlement | Public or future share price | When do they vest and when are they taxed? |
| Stock options | Right to buy shares at a set strike price | Share price above strike price | What is the strike price and exercise window? |
| ESPP | Ability to buy shares, often at a discount | Discount and market price | What discount, lookback and holding rules apply? |
| ESOP | Shares or value inside a retirement-style plan | Company valuation and plan rules | When do you vest and receive distributions? |
| Direct share grant | Shares transferred to you | Current and future share value | Are there restrictions, taxes or repurchase rights? |
The grant value is not the same as take-home pay
Many candidates compare a $50,000 salary difference with a $50,000 equity grant as if both are equally spendable. They are not. Cash arrives on a predictable payroll schedule. Equity may vest over years, fluctuate in value and create taxes before you have cash from a sale.
For a private-company stock employee package, the reported value often comes from a board-approved valuation, recent funding round or internal formula. That value may be reasonable, but it is not the same as a public market price. You might not be able to sell shares even if the paper value rises.
Public company equity is easier to track, but it is still volatile. A grant that looks generous at signing can lose value before the first vesting date. This does not make equity bad. It means you should discount uncertain equity when comparing offers, especially if the cash salary is below your market rate or your personal expenses require stability.
Vesting rules decide what you actually keep
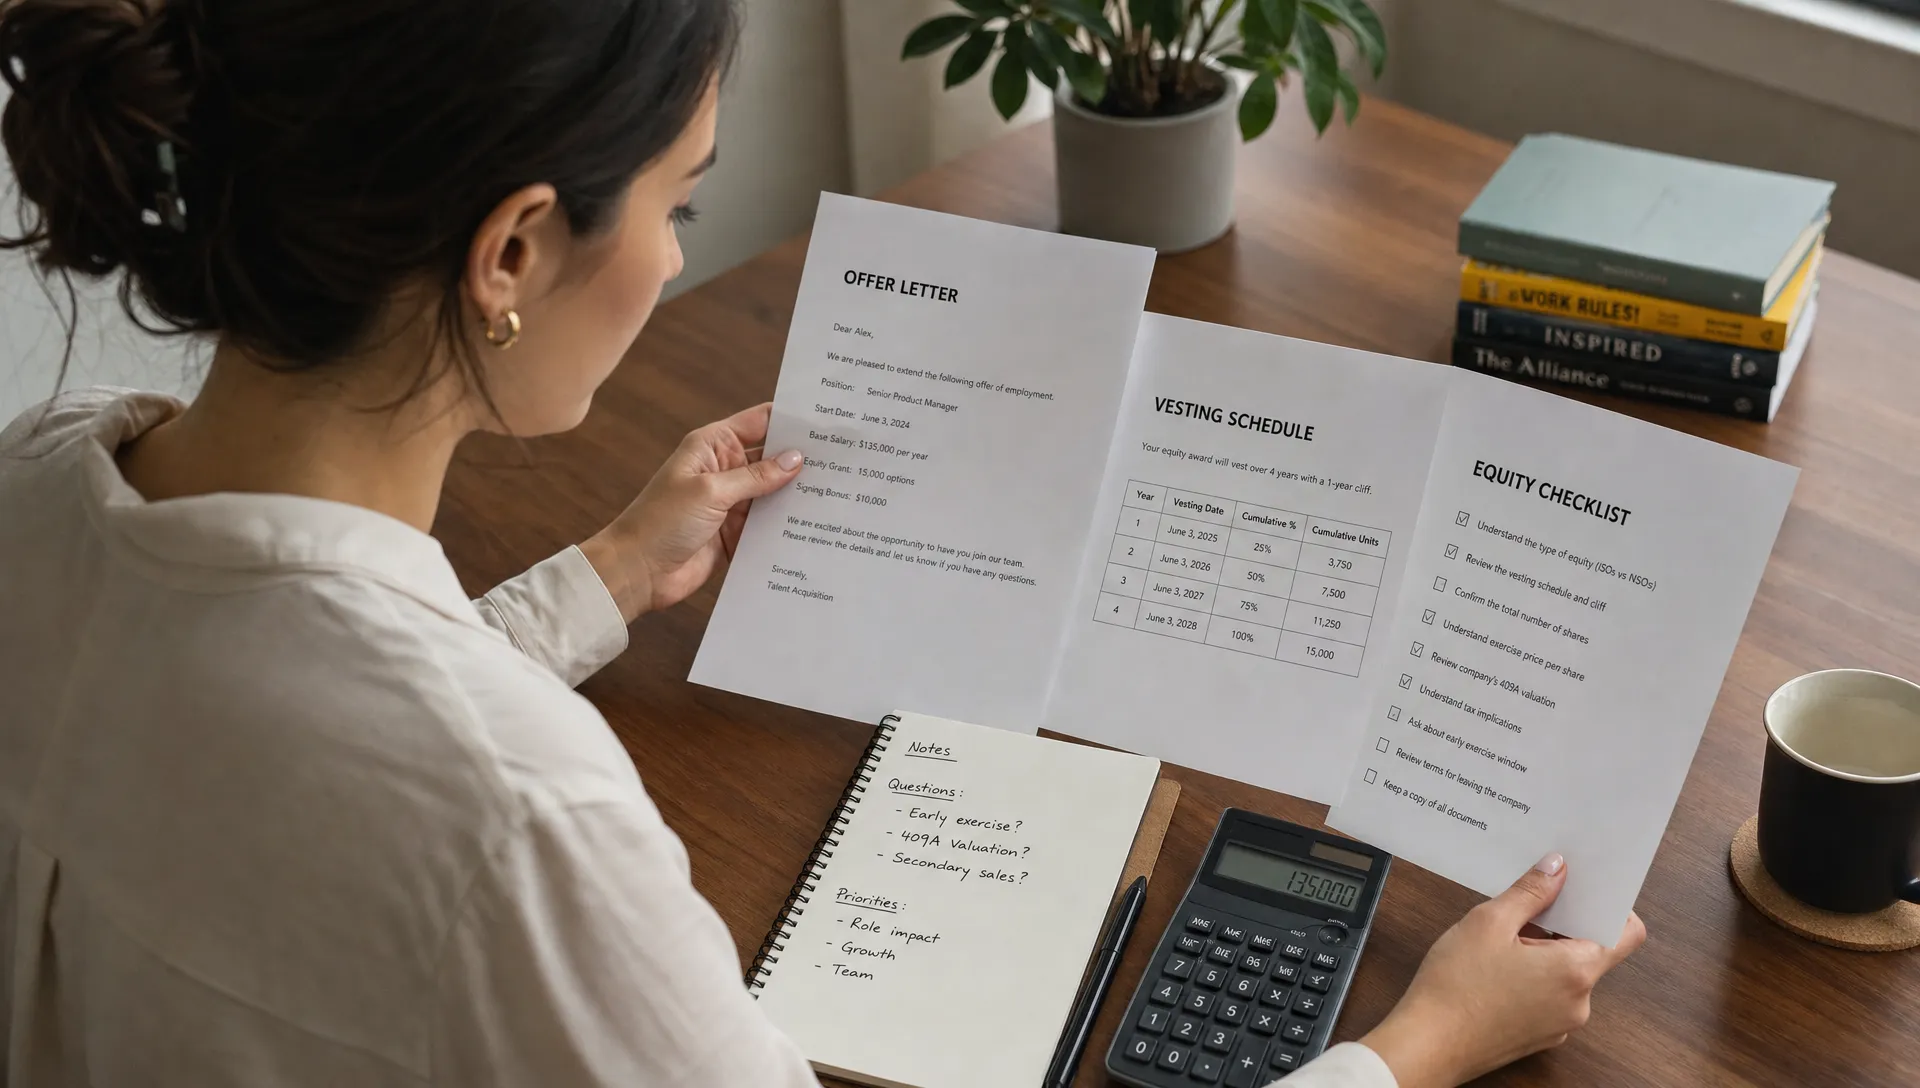
Vesting is the schedule that determines when equity becomes yours. A common structure is four-year vesting with a one-year cliff, meaning you receive nothing if you leave before the first anniversary and then vest gradually after that. Other plans use quarterly, monthly or milestone-based vesting.
The fine print matters. Ask what happens if you resign, are laid off, become disabled or the company is acquired. Some agreements include acceleration if the company is sold. Others provide no acceleration at all. A generous grant with weak vesting protection may be less valuable than a smaller grant with clearer terms.
A stock employee benefit can also be affected by refresh grants. If your initial grant vests over four years, will the company offer additional equity in year two or three? Public technology companies often use refreshers to retain employees, but practices vary. Get the company’s approach in writing if equity is a major reason you are accepting.
Options require special attention to exercise costs
Stock options are not shares. They are the right to buy shares at a predetermined strike price. If the company’s value rises above that strike price, the option may have value. If it does not, the option may expire worthless.
The cost of exercising options can surprise candidates. You may need to pay the strike price, cover taxes and decide whether to hold illiquid shares. In a startup, exercising can mean putting real cash into an asset you cannot sell. If you leave the company, your post-termination exercise window may be short, often measured in months unless the plan offers an extended window.
Ask these questions before joining:
- What is the strike price?
- How many fully diluted shares exist?
- What percentage of the company does the grant represent today?
- What is the post-termination exercise window?
- Can the company repurchase shares if you leave?
- Are there transfer restrictions or secondary sale rules?
Taxes can change the outcome
Equity compensation can create ordinary income, capital gains, alternative minimum tax exposure or retirement-plan taxation depending on the structure. RSUs are generally taxed when they vest or settle. Nonqualified stock options usually create ordinary income on the spread when exercised. Incentive stock options can raise alternative minimum tax issues. ESPPs have their own holding-period rules. ESOP distributions are usually handled under retirement-plan rules.
The tax side of a stock employee benefit is where a strong offer can become complicated. You may owe taxes before you have sold shares, especially with private company equity. That does not mean you should reject equity, but you should model the cash you may need to cover tax bills.
Keep the categories straight. Employee equity tax reporting is different from other business tax obligations, such as federal excise tax filings handled through IRS-authorized Form 720 e-filing. If your offer includes material equity, speak with a qualified tax professional who understands compensation plans before making an exercise or sale decision.
Liquidity is the missing variable in private company offers
Liquidity means your ability to sell shares for cash. Public company shares usually have a clear market, subject to insider trading rules, trading windows and company policies. Private company shares may have no practical market at all.
A high-growth startup can offer life-changing upside, but employees often underestimate how long liquidity can take. An IPO, acquisition or tender offer may happen later than expected or not happen at all. Secondary sales may be restricted, limited to certain investors or subject to company approval.
A generous stock employee package should therefore be tested against your time horizon. If you might need cash in the next one to three years, private shares are not a substitute for salary, emergency savings or liquid investments. If you can afford illiquidity and understand the risk, equity can be a meaningful part of the offer.
Ownership is also a signal about culture and incentives
Equity can tell you something about how a company thinks. Broad-based grants may suggest the company wants employees to share in long-term value creation. An ESPP can make public-company ownership accessible. An ESOP may reflect a more formal employee-ownership culture.
That said, ownership language can be overstated. Owning shares usually means you have an economic claim, not direct control over company assets or strategy. Upside Invest explains this distinction in its guide to what a share in company ownership really means.
Use equity as one signal among many. Ask whether the company shares financial updates with employees, explains valuation changes, educates employees on tax basics and treats departing employees fairly. The way leadership communicates about equity can reveal more than the grant size itself.
Compare the offer against your personal risk
A stock employee benefit is most valuable when it matches your financial situation, risk tolerance and career plan. A 24-year-old with low expenses may rationally accept more equity risk for startup upside. A parent with a mortgage and limited savings may need more cash certainty, even if the equity story is compelling.
Avoid letting employer equity become your entire investment thesis. Your paycheck, career prospects and benefits already depend on the company. Holding a large amount of its stock adds concentration risk. If the company struggles, your job and equity value may decline at the same time.
For publicly traded shares, portfolio comparison tools can help you see whether your employer stock is making you overexposed to one company, sector or theme. Upside Invest lets investors compare allocations and learn from verified investor holdings through anonymous portfolio benchmarking, which can be useful once employer shares become part of your broader portfolio.
Questions to ask before you accept
Before joining, ask direct questions and listen for clarity. A company with a serious equity program should be able to explain the basics without making you feel difficult for asking.
Use this checklist during negotiation:
- What type of equity is this?
- What is the vesting schedule and cliff?
- What is the current share price or valuation basis?
- What percentage ownership does the grant represent on a fully diluted basis?
- What happens if I leave before full vesting?
- Are there refresh grants or promotion grants?
- What taxes might apply at vesting, exercise or sale?
- Are shares liquid today, and if not, what liquidity paths have occurred historically?
- Does the company provide equity education or planning resources?
A stock employee benefit that cannot be explained clearly deserves extra caution. The issue may not be bad intent. It may be complexity, immaturity or inconsistent internal communication. Either way, you should understand the tradeoff before accepting less cash in exchange for uncertain upside.
How to negotiate when equity matters
Negotiating equity is not rude. It is part of evaluating total compensation. If the salary is below market, ask whether the company can improve cash compensation, increase the grant, shorten the cliff or clarify future refresh policies. If the company cannot move, you can still decide whether the mission, role and upside justify the tradeoff.
Be specific rather than emotional. Instead of saying the offer feels low, say you are comparing total annual compensation, vesting risk and liquidity. If you have competing offers, separate guaranteed cash from uncertain equity so the comparison is fair.
You can also negotiate for information. In private companies, candidates may not receive every financial detail, but they can often receive the fully diluted share count, latest valuation basis, strike price, vesting terms and exercise window. If a company refuses to share basic equity terms before you join, treat that as a meaningful signal.
Frequently Asked Questions
Is equity better than a higher salary? Not automatically. Salary is predictable and liquid. Equity can create more upside, but it depends on vesting, taxes, share price performance and liquidity. The right mix depends on your savings, risk tolerance and career goals.
How do I compare a stock employee benefit across two offers? Convert each offer into guaranteed cash, likely equity value and speculative upside. Then discount equity for vesting risk, tax costs and liquidity. Public company RSUs are usually easier to compare than private options.
Should I accept lower pay for startup stock options? Only if you can afford the lower cash income and understand that options may be worth little or nothing. Ask for the strike price, fully diluted ownership percentage, exercise window and recent valuation basis.
What happens to employee stock if I leave? It depends on the plan. Unvested equity is usually forfeited. Vested options may need to be exercised within a set window. Vested shares may remain yours, but private company shares can still be subject to transfer limits or repurchase rights.
Do employee stock benefits always create taxes? Many do, but the timing varies. RSUs, options, ESPPs and ESOPs follow different tax rules. Large grants or private-company options are worth reviewing with a tax professional before you exercise, sell or make major career decisions.
The bottom line before you join
Employee equity can be a powerful wealth-building benefit, but only when you understand the structure. Do not stop at the headline grant value. Read the documents, model the vesting timeline, ask about liquidity, estimate taxes and compare the offer against your real-life need for cash and diversification.
A strong stock employee package should make the opportunity clearer, not more confusing. If the company explains the terms well and the risk fits your finances, equity can strengthen the offer. If the terms are vague, illiquid or costly to maintain, negotiate before you sign or price the uncertainty into your decision.