Why Investor Leaderboards Can Hide Survivorship Bias
A leaderboard can show real returns from real accounts and still give you a distorted picture of investing success. Survivorship bias arises when investors who remain visible receive attention while those who disappear are excluded from the evidence. If unsuccessful accounts disconnect, close or stop qualifying, the remaining records can make strong performance look more common than it was.
For retail investors, the useful question is not just who ranks first. It is who entered the comparison, who left it and whether the missing accounts would change your interpretation. Verified data improves confidence in what you can see. It does not automatically explain what you cannot.
What Survivorship Bias Hides in Investor Leaderboards
An investor leaderboard ranks a defined group of accounts using a measure such as total return or Sharpe ratio. The ranking may be accurate for that group. The problem starts when readers treat the visible group as representative of everyone who attempted the strategy.
Imagine a platform that displays only currently connected accounts. Investors who suffer large losses might disconnect, abandon their accounts or withdraw from public sharing. If their histories also disappear from comparisons, the remaining population becomes selectively stronger.
The missing denominator matters: ten impressive winners mean something different among 100 original participants than among 100,000.
Not every eligibility rule creates a misleading leaderboard. Minimum account ages and data-quality requirements can improve comparisons. But the rules should be visible, consistently applied and accompanied by an explanation of what happens to accounts that leave.
A top-performer list does not need to represent the average investor to be useful. It does need to avoid suggesting that exceptional outcomes are typical or readily repeatable.
A Simple Example: The Same Investors, Two Different Stories
Consider a hypothetical group of 100 investors. Each starts the year with $10,000, makes no deposits or withdrawals and has the following full-year return:
| Group | Number of investors | Return per investor | Combined ending value |
|---|---|---|---|
| Strong performers | 20 | +40% | $280,000 |
| Modest gainers | 60 | +5% | $630,000 |
| Large-loss accounts | 20 | -60% | $80,000 |
| Full starting group | 100 | -1% average | $990,000 |
The original group begins with $1 million and finishes with $990,000. Because starting balances are equal, its average investor return is also -1%.
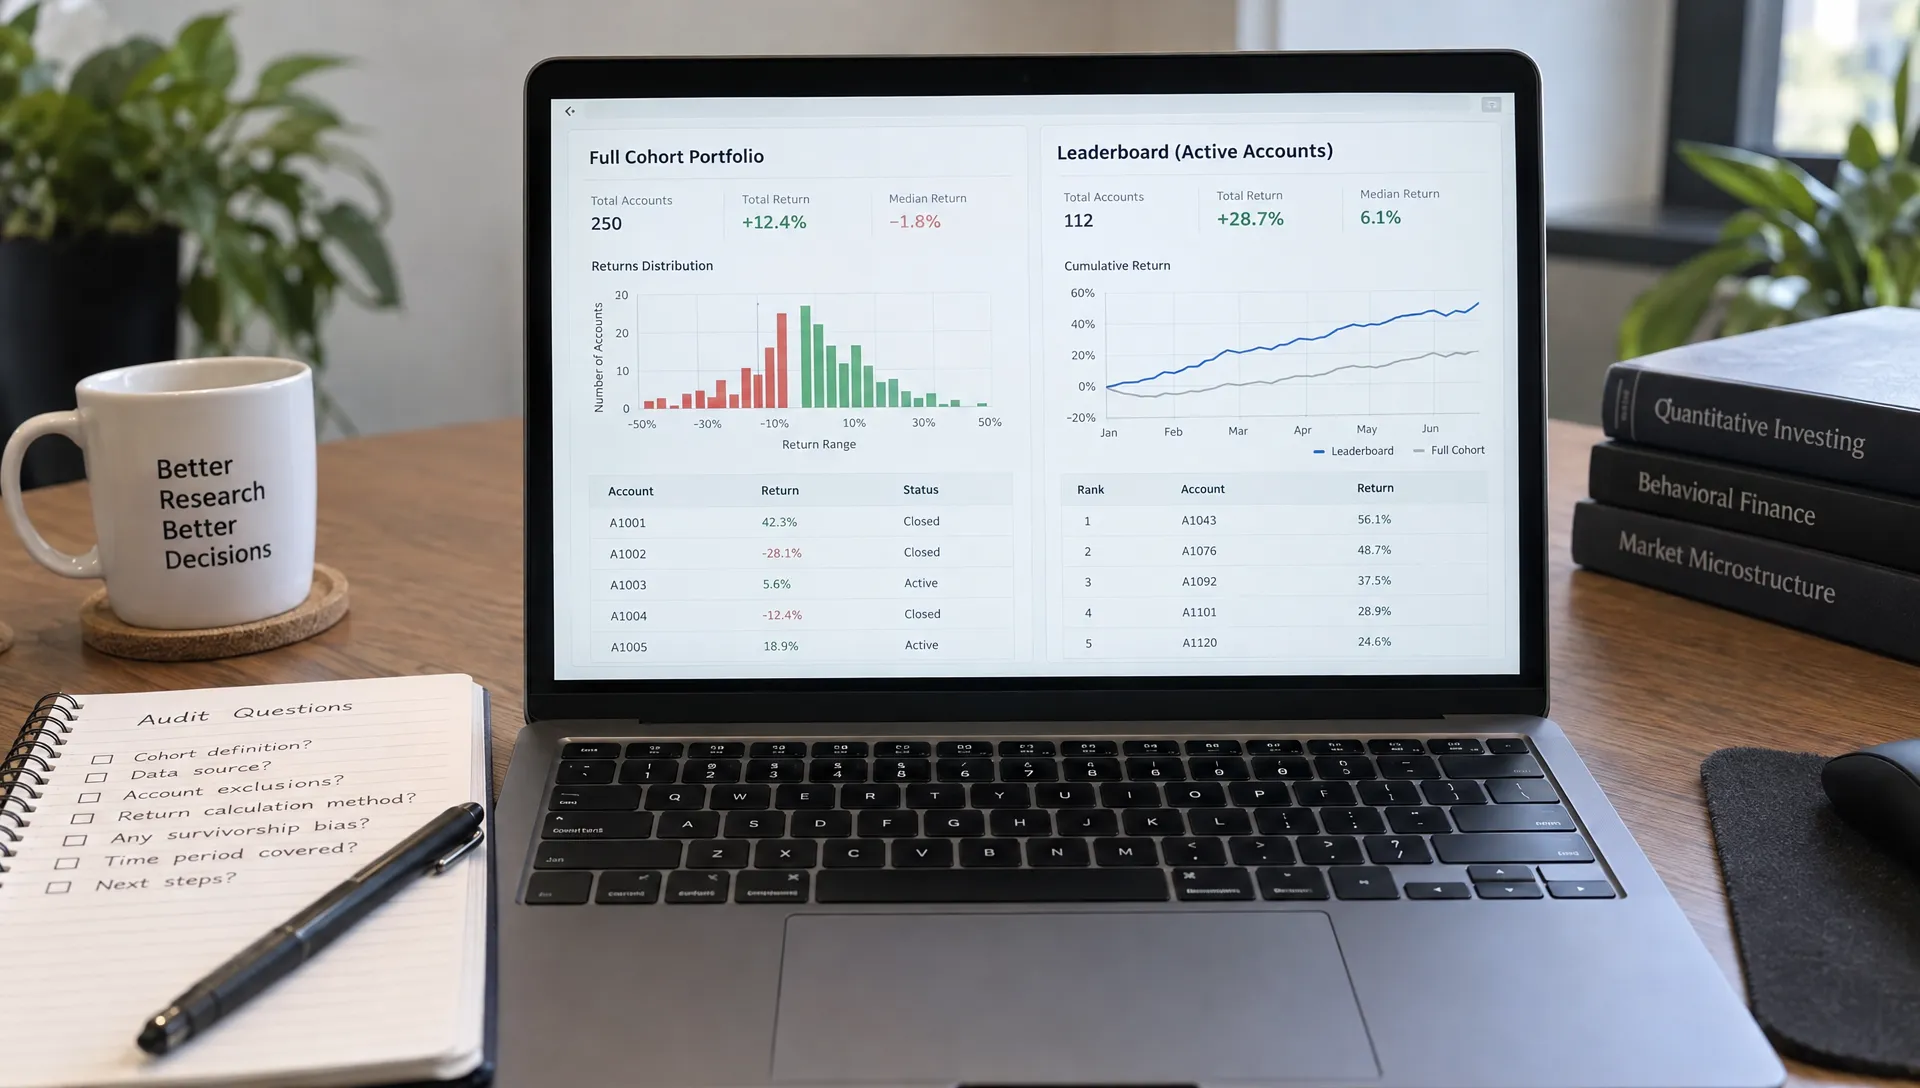
Now suppose the 20 large-loss accounts disconnect after year-end, before the leaderboard is published, and the platform excludes their histories. The remaining 80 accounts started with $800,000 and finished with $910,000. Their average return is 13.75%.
No surviving account’s return has changed. The population being summarized has.
The highest-ranked investors still earned 40% in this example. Survivorship bias does not make those returns fictitious. It makes conclusions about the wider group unreliable if readers see only the survivors.
These figures are illustrative, not observations about Upside or any other platform. Real-world analysis also needs consistent treatment of cash flows, fees and account coverage.
Verified Holdings Are Not the Same as a Representative Sample
Verification and representativeness answer different questions.
Verification can strengthen confidence that a displayed holding or account record is genuine. Representativeness concerns whether the accounts being analyzed fairly reflect the population you want to understand.
A dataset may contain authentic accounts yet still overrepresent investors who volunteered after a successful year. It may also exclude people who stopped sharing, omit assets held elsewhere or begin tracking only after a strategy became popular.
This distinction has a long history in investment research. Mark Carhart’s 1997 paper, “On Persistence in Mutual Fund Performance,” used a survivor-bias-free mutual fund database to study performance persistence. The setting differs from retail investor leaderboards, but the methodological lesson transfers: the dataset’s construction affects the conclusions.
For any investment research platform, ask two separate questions: Is the visible information reliable, and what information is absent?
Other Ranking Problems That Look Like Survivorship Bias
Several biases can coexist, but distinguishing them helps you ask better questions.
Winner selection occurs when you examine only the highest returns. Even with every account retained, a large population can produce spectacular winners by chance. A complete leaderboard does not prove that its leaders have repeatable skill.
Backfill bias can arise when investors join after strong performance and contribute earlier records. Those histories may be accurate, but the decision to submit them was influenced by results already achieved. Separating live-tracked performance from imported history makes that distinction clearer.
Look-ahead bias appears when an analysis uses information that was unavailable at the decision date. Studying today’s winners and assuming you could have identified them a year ago is one example.
Current-holdings bias is a related reconstruction problem. Today’s positions do not necessarily explain past returns. Sold winners, realized losses, hedges and changes in position size may be missing from the snapshot.
Survivorship bias specifically concerns the selective disappearance or exclusion of observations. Fixing it does not automatically solve these other problems.
How to Audit a Leaderboard Before Acting on It
Check Who Enters, Leaves and Remains Counted
Start with the population rather than the first-ranked account. Look for disclosure of the original eligible group, the current group and the treatment of disconnected accounts.
The strongest comparison follows a defined starting cohort through time. If an account stops reporting, that missing information should remain visible as a limitation rather than silently disappearing from the story. Historical observations should be retained only where consent and applicable privacy requirements allow.
A useful methodological checklist is:
- Eligibility: What account age, balance or activity requirements apply?
- Departures: Are closed, disconnected and inactive accounts excluded from historical summaries?
- History: Which results were tracked live and which were imported later?
- Coverage: Does the record represent one account or the investor’s broader portfolio?
- Completeness: How many accounts lack data for the full comparison period?
Missing returns cannot simply be assumed to be losses. Departing investors may have many reasons for leaving. The correct response is to disclose the uncertainty, not invent outcomes for them.
Check Whether Returns Are Comparable
A twelve-month return should not be ranked against a three-month gain without a clear adjustment and explanation. Short-period annualization can make an unusually good stretch look more durable than it is.
Cash flows matter too. Deposits are not investment profits. Time-weighted returns aim to separate investment performance from the timing of external cash flows, while money-weighted returns reflect the investor’s cash-flow experience. Both can be useful, but they answer different questions.
Then examine the risk behind the result. A concentrated portfolio using leverage is not directly comparable to an unleveraged diversified portfolio merely because both have a percentage return.
Drawdown, volatility and Sharpe ratio add context. None proves skill, and a Sharpe ratio estimated from a short or unusual period can be unstable. Benchmark choice matters as well: a sector-heavy portfolio may mostly reflect that sector’s strong run rather than successful security selection.
Look for Performance Beyond the Winning Window
A ranking describes a particular period. To assess whether it offers useful investing insights, examine what happened before and after that period where records are available.
Did the investor maintain a similar process? Did returns depend on one oversized position? Did a change in market conditions expose risks that were not apparent during the winning stretch?
Repeated appearances across overlapping periods are not independent evidence. A strong twelve-month result and a strong thirteen-month result may largely reflect the same trades. A longer record across different market conditions is more informative, though it still cannot guarantee future performance.
The practical test is whether you can explain the portfolio’s exposures and risks without relying on its rank.
Use Rankings to Generate Research Questions, Not Copy Instructions
Leaderboards are useful discovery tools. They can surface unfamiliar securities, recurring sector exposures or investors whose decision-making deserves closer examination. That is different from treating a ranking as a buy signal.
Move from the account level to the holding level. For example, Visa’s community ownership profile provides a place to investigate ownership information around a specific security. Community ownership can prompt further research, but it does not establish valuation, suitability or the reasons behind another investor’s allocation.
Before copying a position, distinguish the investor’s historical entry price from the price available to you. Your time horizon, tax situation and existing exposures may also differ substantially.
Match Portfolio Risk to Your Household Finances
A visible portfolio does not reveal its owner’s full financial circumstances. Someone holding a concentrated account may also have substantial savings, other investments or reliable income outside the displayed record.
Your capacity to absorb losses depends partly on those household details. Review emergency savings, debt payments and essential expenses before adopting more risk. If healthcare premiums are a significant budget item, comparing health insurance options can help clarify that recurring cost as part of the same financial review.
The point is not to reproduce a stranger’s risk exposure. It is to determine whether an investment fits the money you can afford to keep invested through a difficult period.
Frequently Asked Questions
Are investor leaderboards inherently misleading? No. A leaderboard can accurately rank its stated population. Problems arise when eligibility, missing accounts or measurement methods are unclear, or when readers interpret exceptional results as typical outcomes.
Does anonymous verification eliminate survivorship bias? No. Verification addresses authenticity while anonymity protects identity. Neither automatically ensures that departed accounts remain represented or that the sample reflects all investors.
Does ranking by Sharpe ratio solve the problem? No. Risk-adjusted measures can improve context, but they cannot restore missing observations. Their usefulness also depends on the calculation method, observation period and quality of the underlying returns.
Can I identify skill from one year at the top? One year is limited evidence. Investigate concentration, leverage, benchmark exposure and the investor’s longer record. Strong performance can reflect skill, favorable conditions, luck or a combination of all three.
Make Portfolio Comparisons With the Missing Data in Mind
Use Upside’s verified investor holdings and portfolio comparison tools to explore allocations and develop research questions. Keep a separate standard for evaluating performance claims: a clear population, comparable measurement periods and transparent treatment of missing records.
A high rank can tell you where to look. Understanding who is absent helps you decide how much weight to give what you find.