7 Best Stocks With Upside Potential From Recurring Revenue
The best stocks with upside potential are not always businesses waiting for a dramatic turnaround. Some already collect revenue through subscriptions, renewable contracts or essential services. Their opportunity comes from retaining customers, expanding spending and turning that revenue into more cash per share.
Adobe, Salesforce, ServiceNow, ADP, Waste Management, Verisign and Roper Technologies offer seven different ways to research that opportunity. This is a business-model shortlist, not a live valuation ranking: no real-time prices or analyst targets are used, and none of these stocks is attractive at every price.
What recurring revenue actually tells you
Recurring revenue gives a business an established customer base from which to generate future sales. It can reduce dependence on winning new customers every quarter, but it does not eliminate cancellations, competition or pricing pressure.
Repeat purchases are different. A shopper might use Expressluv’s international gift delivery for several celebrations each year, but those separate orders are discretionary repeat spending, not contracted revenue. Software subscriptions and renewable service agreements provide different levels of visibility.
Even contracted revenue needs scrutiny. A customer may renew while buying fewer seats, reducing usage or negotiating a discount. Annual recurring revenue, or ARR, is also a company-defined operating metric, not a substitute for recognized revenue or cash flow.
The investment question is whether the existing customer base can produce growing cash flow without excessive selling costs, capital spending or shareholder dilution.
How we selected the best stocks with upside potential
These seven companies have identifiable recurring or renewable revenue streams, established customer relationships and plausible paths to higher cash generation. They are not ordered by expected return, and their recurring-revenue exposure is not identical.
| Company | Ticker | Recurring-revenue foundation | Potential upside driver | Main risk to investigate |
|---|---|---|---|---|
| Adobe | ADBE | Creative and document subscriptions | Successful monetization of new tools | AI competition and weaker pricing power |
| Salesforce | CRM | Enterprise software subscriptions and support | Higher customer spending and cash margins | Seat pressure and dilution |
| ServiceNow | NOW | Enterprise workflow subscriptions | Expansion into additional workflows | Valuation and longer sales cycles |
| Automatic Data Processing | ADP | Payroll and human resources services | Client retention and product expansion | Employment sensitivity and competition |
| Waste Management | WM | Recurring collection and disposal services | Pricing, route efficiency and asset utilization | Capital intensity and operating costs |
| Verisign | VRSN | Domain registry renewals | Renewal activity and permitted pricing | Domain demand and contractual restrictions |
| Roper Technologies | ROP | Specialized software and service relationships | Organic growth and disciplined acquisitions | Acquisition pricing and leverage |
The distinctions matter: subscription software, payroll processing and waste collection do not have the same margins, capital requirements or economic sensitivity.
1. Adobe: subscription economics facing an AI test
Adobe’s investment case rests on creative and document workflows that customers use repeatedly. Its subscription model creates an established revenue base, while integration across products can make replacement inconvenient for professional users.
The upside case depends on Adobe making new capabilities valuable enough to support customer retention, additional purchases and pricing. Generative AI could strengthen its products, but competing tools could also reduce customers’ willingness to pay for existing workflows.
For anyone researching the best stocks with upside potential, Adobe illustrates why recurring revenue must be evaluated alongside competitive durability. A subscription is valuable only while customers continue to need the product.
Review Adobe’s investor disclosures for Digital Media ARR trends, subscription revenue, operating cash flow and share count. Compare management’s discussion of AI adoption with evidence of monetization rather than assuming usage automatically creates incremental profit.
What would weaken the thesis: Persistent deterioration in subscription growth combined with evidence that customers are replacing core Adobe workflows, rather than merely experimenting with alternatives.
2. Salesforce: customer expansion must reach shareholders
Salesforce sells software supporting customer-facing functions such as sales and service. Its products can become embedded in business processes, creating recurring subscription and support revenue.
A credible upside case combines continued customer spending with operating discipline. Existing customers might adopt additional products, but bundled offerings and AI features must generate incremental value rather than simply change how revenue is packaged.
The crucial distinction is between company-level cash generation and cash generation per share. Stock-based compensation can dilute shareholders, while some repurchases merely offset that dilution. Assess both together instead of treating every buyback dollar as an additional shareholder benefit.
When comparing the best stocks with upside potential, Salesforce deserves scrutiny on retention quality, not just the size of its installed customer base.
Use Salesforce’s financial disclosures to examine subscription and support revenue, remaining performance obligations, operating cash flow and diluted shares. Remaining performance obligations represent contracted revenue not yet recognized, but their timing and composition matter.
What would weaken the thesis: Sluggish customer expansion alongside continued dilution or spending that fails to produce durable revenue growth.
3. ServiceNow: expansion within enterprise workflows
ServiceNow provides software that helps organizations manage workflows, including IT service management. Its expansion opportunity comes from adding workflows and products within existing enterprise relationships as well as winning new customers.
That creates a potentially attractive recurring-revenue model: an initial deployment can become the starting point for a broader relationship. However, implementation effort, procurement scrutiny and competition can slow expansion.
Review subscription revenue, renewals, large-customer development and current remaining performance obligations in ServiceNow’s investor materials. Current remaining performance obligations, often called cRPO, generally cover contracted revenue expected to be recognized within the next 12 months. Acquisition effects and currency movements can complicate comparisons.
The best stocks with upside potential still need a reasonable starting valuation. Strong customer retention cannot protect an investor who pays a price requiring years of near-perfect execution.
What would weaken the thesis: Slowing expansion across several reporting periods without an offsetting improvement in profitability or an identifiable temporary explanation.
4. ADP: essential payroll with economic sensitivity
Automatic Data Processing offers payroll and human resources services that businesses need repeatedly. Processing employee pay is an operational necessity, which supports ongoing customer relationships.
ADP offers a different research angle from enterprise software. Potential upside can come from retaining clients, winning additional employers, expanding services and improving operating efficiency. However, its revenue base is not insulated from the labor market: employment levels and payroll activity influence parts of the business.
Another consideration is interest earned on funds held for clients. Changes in interest rates can affect earnings without indicating a corresponding improvement or deterioration in the underlying service franchise.
In ADP’s investor reports, examine client retention where disclosed, new business bookings, payroll-related activity, segment margins and the contribution from client funds interest. Separate recurring service performance from benefits that depend on the rate environment.
What would weaken the thesis: A sustained decline in client retention or competitive pricing pressure that persists beyond a normal employment slowdown. Reliable demand does not necessarily mean strong incremental returns at an expensive purchase price.
5. Waste Management: recurring service backed by physical assets
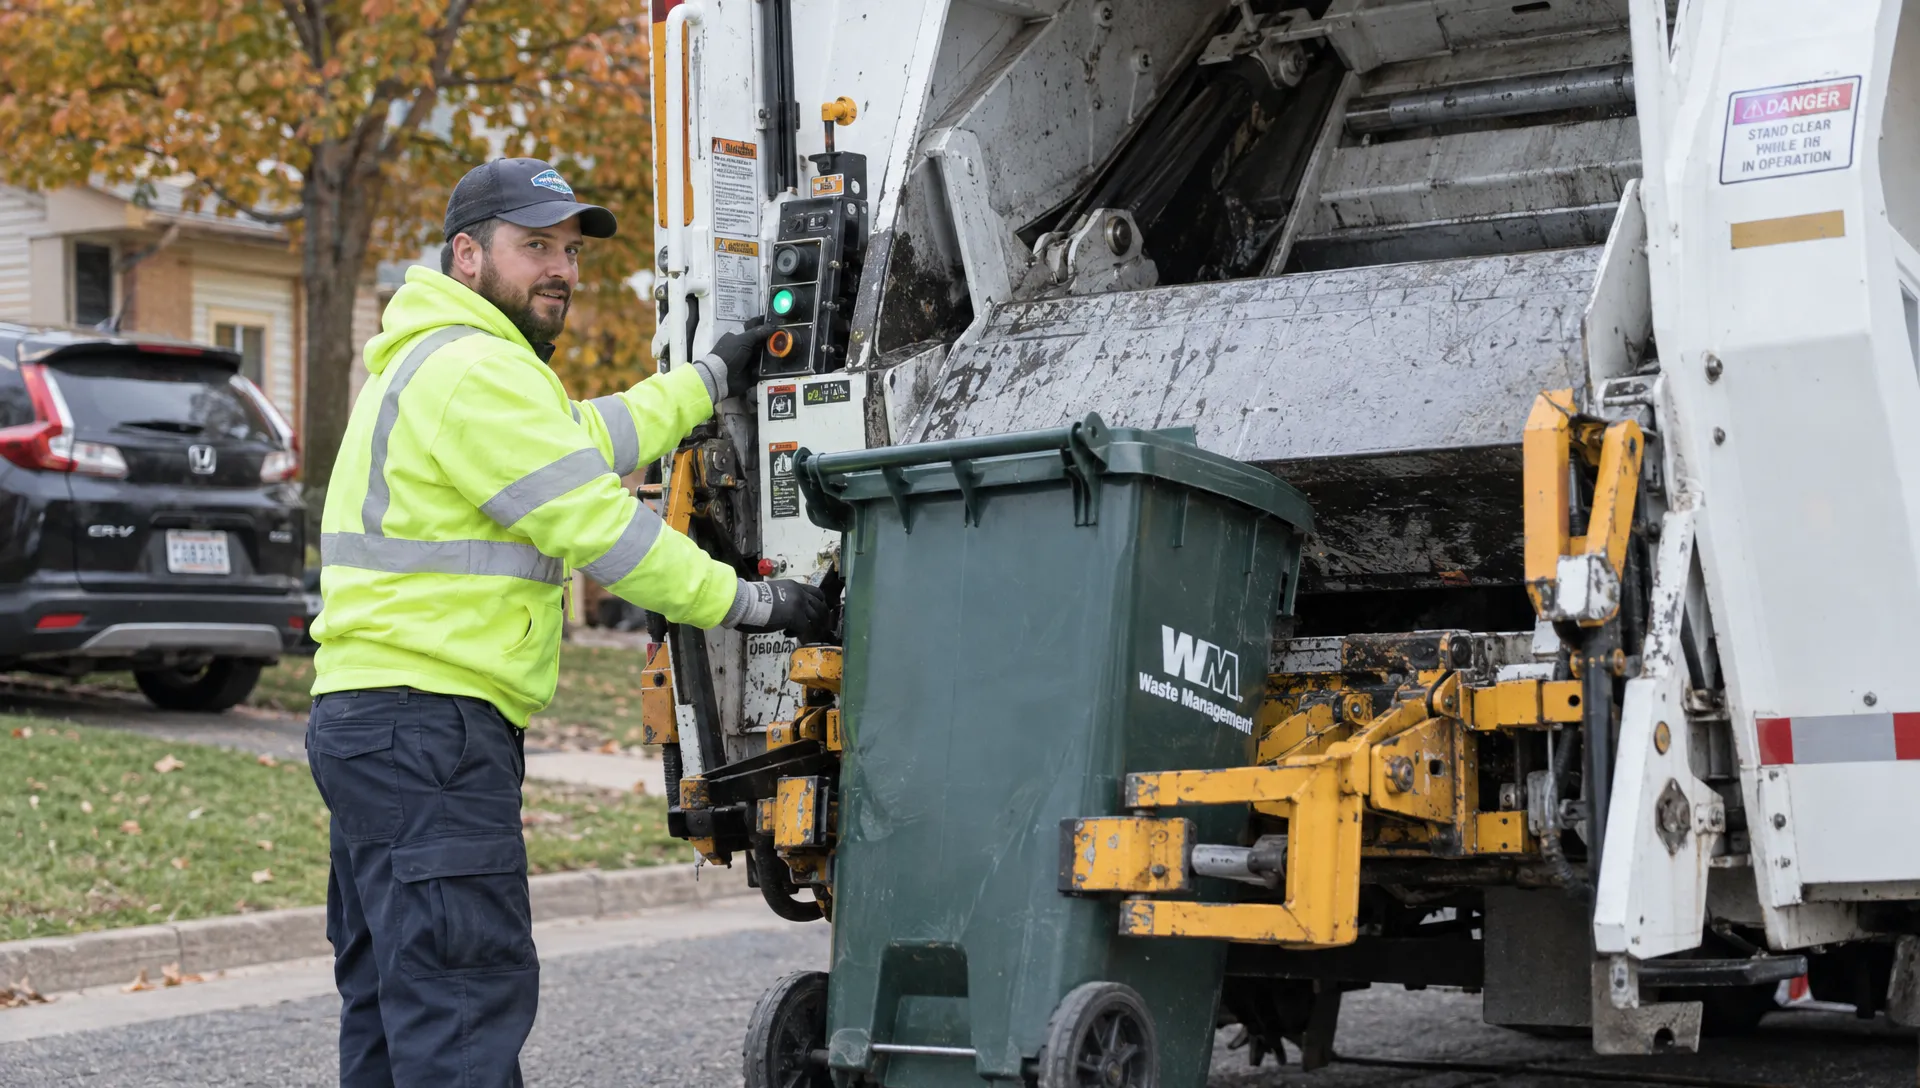
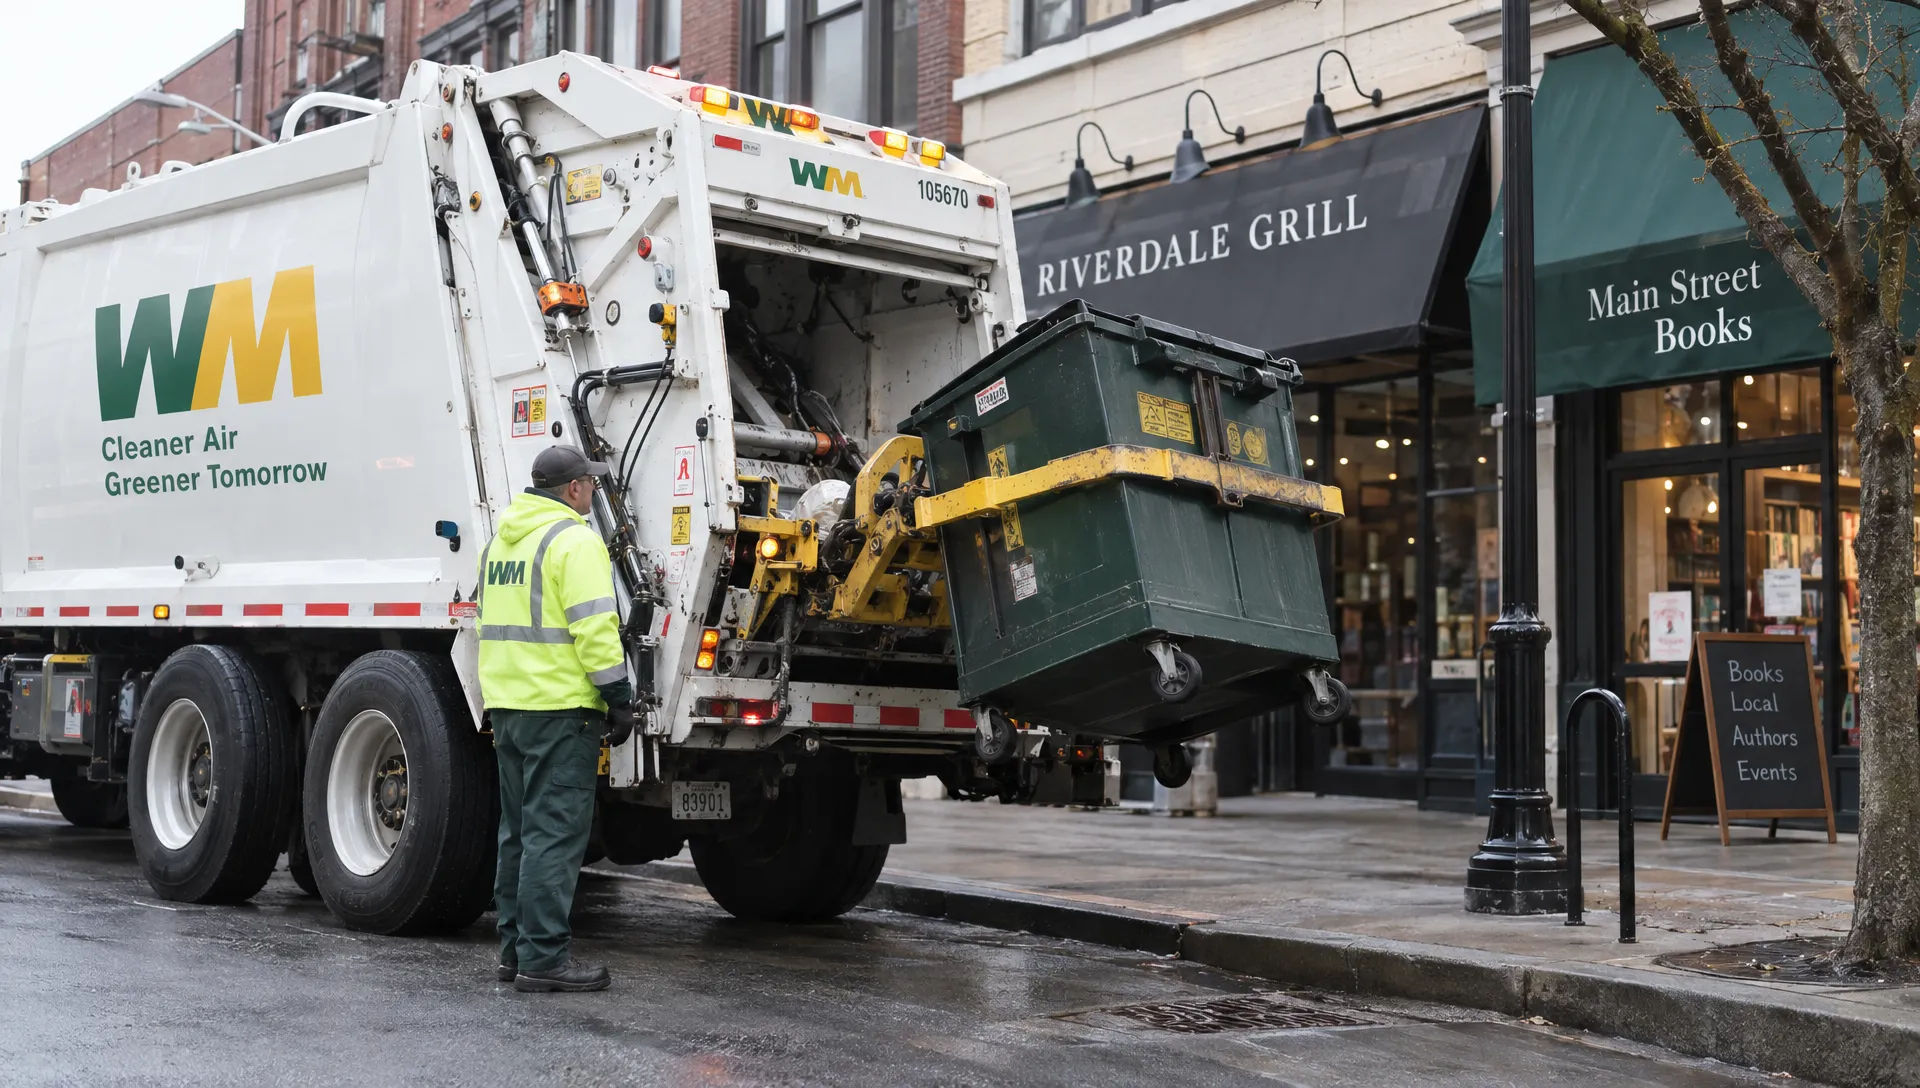
Waste Management belongs in a discussion of the best stocks with upside potential because recurring revenue extends beyond software. Homes and businesses need regular waste collection, while disposal infrastructure supports an essential service network.
Potential upside can come from pricing, efficient collection routes, better asset utilization and disciplined capital allocation. Local operating density can improve economics when vehicles serve more customers within a practical area.
The qualification is capital intensity. Trucks, facilities and environmental obligations require real spending. Recurring customer payments should not be confused with subscription-like incremental margins, and recycling-related revenue can introduce commodity exposure.
Review Waste Management’s financial reports for collection and disposal pricing, volumes, operating costs, capital expenditures and free cash flow. Separate organic improvements from acquisition-driven growth, and examine the debt required to fund expansion.
What would weaken the thesis: Pricing that repeatedly fails to cover operating-cost increases, or capital requirements that prevent operating improvements from translating into cash available to shareholders.
6. Verisign: domain renewals with contractual boundaries
Verisign operates registry infrastructure for .com and .net domain names. Registrars sell domain registrations to end customers, while Verisign earns registry fees under its agreements.
The recurring element comes from domain renewals. Established domains can be important business assets, but customers can still abandon them, and new registrations can fluctuate. A technically important service does not automatically produce fast growth.
The upside case depends on the interaction between the domain base, renewal activity, permitted pricing and capital allocation. Pricing rights and operating agreements are central to the analysis, not minor legal details.
Use Verisign’s investor disclosures to examine domain trends, renewal data, cash generation and contractual risks. Evaluate pricing assumptions against the applicable agreements rather than extrapolating historical increases indefinitely.
For this candidate, the most useful question is whether modest operating growth and per-share cash generation justify the market price.
What would weaken the thesis: Persistent contraction in the domain base that permitted pricing cannot offset, or unfavorable changes to the agreements governing the business.
7. Roper Technologies: specialized software plus acquisition discipline
Roper acquires and operates businesses serving specialized customer needs, including vertical-market software. Products embedded in industry-specific workflows can support long customer relationships and recurring revenue.
Its upside case has two components: organic improvement within existing businesses and sensible reinvestment through acquisitions. Those components deserve separate analysis. Buying another company increases reported revenue, but it creates shareholder value only if the acquired cash flows justify the purchase price and financing costs.
Roper shows why the best stocks with upside potential cannot be selected using recurring-revenue percentages alone. Management’s capital allocation can matter as much as customer retention.
Review Roper’s business and investor information for organic growth, cash conversion, acquisition spending, debt and the mix of recurring revenue. Examine adjustments to reported earnings rather than assuming every acquisition-related expense lacks economic significance.
What would weaken the thesis: Repeatedly paying high acquisition prices while organic growth slows, leverage rises or cash returns fail to support the acquisition strategy.
Turn revenue durability into a valuation test
A recurring-revenue business can grow while its stock delivers a disappointing return. The missing variable is often the valuation investors were willing to pay at the start.
Consider this simplified, hypothetical example. It is not a forecast for any company above.
| Assumption | Starting point | Three years later |
|---|---|---|
| Normalized annual free cash flow per share | $5.00 | $6.50 |
| Price-to-free-cash-flow multiple | 30 | 24 |
| Implied share price | $150 | $156 |
Free cash flow per share grows 30%, but the implied share price rises only 4% because the valuation multiple contracts. Dividends, taxes and trading costs are excluded.
A useful search for the best stocks with upside potential therefore needs three separate judgments: how durable revenue is, how much cash reaches each share and what multiple that cash deserves.
Build a cautious, central and optimistic case using customer retention, organic growth, margins, reinvestment needs and diluted shares. Avoid comparing these businesses solely on price-to-sales ratios, since their capital requirements differ substantially.
Upside Invest’s guide to testing a stock’s upside case before buying can help turn those assumptions into a thesis with measurable failure conditions.
Check whether the shortlist adds diversification
Owning several recurring-revenue companies does not necessarily diversify a portfolio. Adobe, Salesforce, ServiceNow and parts of Roper can share exposure to software spending, corporate technology budgets and valuation changes affecting growth stocks.
ADP and Waste Management add different operating drivers, but they still face economic and company-specific risks. Verisign introduces another business model rather than removing risk altogether.
Before buying, compare your existing holdings with the new candidate. Consider indirect exposure through funds, concentration in shared economic drivers and how much downside a position could contribute.
The best stocks with upside potential for a watchlist may still be poor additions to an already concentrated portfolio. This guide to evaluating whether an upside stock fits your portfolio addresses position sizing and overlapping risks in more detail.
Frequently asked questions
Which recurring-revenue stock has the most upside? That cannot be established from the business model alone. The answer depends on the current share price, future cash flow, dilution and the assumptions used to value the business. This shortlist is not a forecast ranking.
Are subscription stocks safer than other stocks? Subscription revenue can improve visibility, but customers can cancel, reduce spending or switch providers. High valuations, debt and competitive disruption can still create substantial investment risk.
Which metrics matter most for recurring-revenue businesses? Start with retention, organic revenue growth and free cash flow per share. Then use model-specific measures, such as ARR for some software businesses, payroll activity for ADP or collection pricing and volumes for Waste Management. Company definitions may differ.
Can these companies realistically deliver 1,000x returns? A 1,000x outcome should not be a reasonable base-case expectation for these established businesses. Researching the best stocks with upside potential is more useful when focused on plausible cash-flow growth and valuation rather than extraordinary return promises.
Compare the businesses with your actual portfolio
Use Upside Invest to compare allocations with verified investor portfolios through private, anonymous profiles and review return and Sharpe metrics. Community holdings can provide research ideas, but they do not establish fair value or guarantee future performance.
Choose a candidate, review its latest filings and write down the valuation and operating conditions that would justify buying. This article is educational, not personalized investment advice.