How to Screen Best Upside Penny Stocks for Risk
Searching for the best upside penny stocks should start with a rejection process, not a price target. A low share price can hide a cash shortage, repeated dilution or a market so thin that selling becomes expensive. Before estimating potential returns, check whether you can verify the business, understand its financing needs and exit a position under unfavorable conditions. The goal is a defensible research shortlist, not a prediction of which stock will multiply in value.
Separate a low price from a low valuation
Investors commonly use “penny stock” to describe shares trading below $5, although the regulatory definition has exceptions. That price tells you little about whether a company is cheap. Market capitalization, debt, cash and the number of shares outstanding matter more.
A $0.50 stock with 500 million shares outstanding has a $250 million market capitalization. A $4 stock with 10 million shares has a $40 million market capitalization. Neither is necessarily the better investment.
Trading venue also changes your research burden. Exchange-listed companies face listing requirements, but those requirements do not eliminate business failure or dilution. Over-the-counter securities can have very different disclosure arrangements. The SEC’s guidance on microcap stocks explains why limited information and manipulation deserve particular attention.
Screen best upside penny stocks for risks that block further research
Start with evidence you can verify independently. Missing information should not become an invitation to make optimistic assumptions.
| Risk gate | What to inspect | Reason to pause or reject |
|---|---|---|
| Disclosure | Latest required filings and financial statements | Missing, stale or inconsistent information |
| Liquidity | Bid-ask quotes, dollar volume and trading frequency | Your intended position could be difficult to unwind |
| Funding | Available cash, cash consumption and debt maturities | Financing is needed before a credible milestone |
| Dilution | Share-count changes, warrants and financing terms | Future ownership cannot be estimated reasonably |
| Promotion | Paid coverage, conflicts and unsupported claims | The investment case depends on publicity rather than evidence |
A failed gate does not always prove fraud or inevitable failure. It means the stock has not earned a place on your research shortlist. A strong story should not compensate for an unresolved financing obligation or unavailable financial statements.
Keep separate categories for rejected candidates, unresolved questions and stocks worth deeper analysis. This prevents an unanswered question from quietly becoming an accepted assumption.
Test whether you could actually exit
Measure trading capacity in dollars
Share volume can look impressive when each share costs only a few cents. Calculate approximate daily dollar volume by multiplying shares traded by their price, or use reported dollar-volume data when available.
Review a representative period rather than one promotional spike. Compare average and median activity, look for days with little trading and inspect current quotes. Historical volume does not guarantee that buyers will remain available.
For example, a hypothetical $2,000 position represents 10% of a stock’s $20,000 daily dollar volume. That does not make the trade impossible, but it should prompt closer inspection of market depth and realistic exit capacity. There is no universal participation threshold that makes a penny stock safe.
Include the spread in your downside estimate
Suppose the bid is $0.47 and the ask is $0.50. Buying at the ask and immediately selling at the unchanged bid would lose 6%, before fees or additional slippage.
The best upside penny stocks still need a workable exit plan; a quoted gain has limited value if selling consumes much of it. Limit orders can control the price you accept, but they cannot guarantee execution. A stop order also does not guarantee your intended exit price during a gap or disorderly market.
Read the financing history before the growth story
For US SEC-reporting issuers, use SEC EDGAR to find annual reports, quarterly reports and material-event filings. Foreign issuers may use different forms, while some OTC issuers have different reporting arrangements. Identify the applicable disclosure system first.
Reconcile the latest financial statements with subsequent announcements. A quarter-end cash balance may already be outdated after an acquisition, debt payment or financing.
Focus on operating cash flow, debt obligations, related-party transactions and changes in shares outstanding. Read any going-concern discussion and the auditor’s opinion. These are more useful starting points than adjusted earnings presented without a reconciliation.
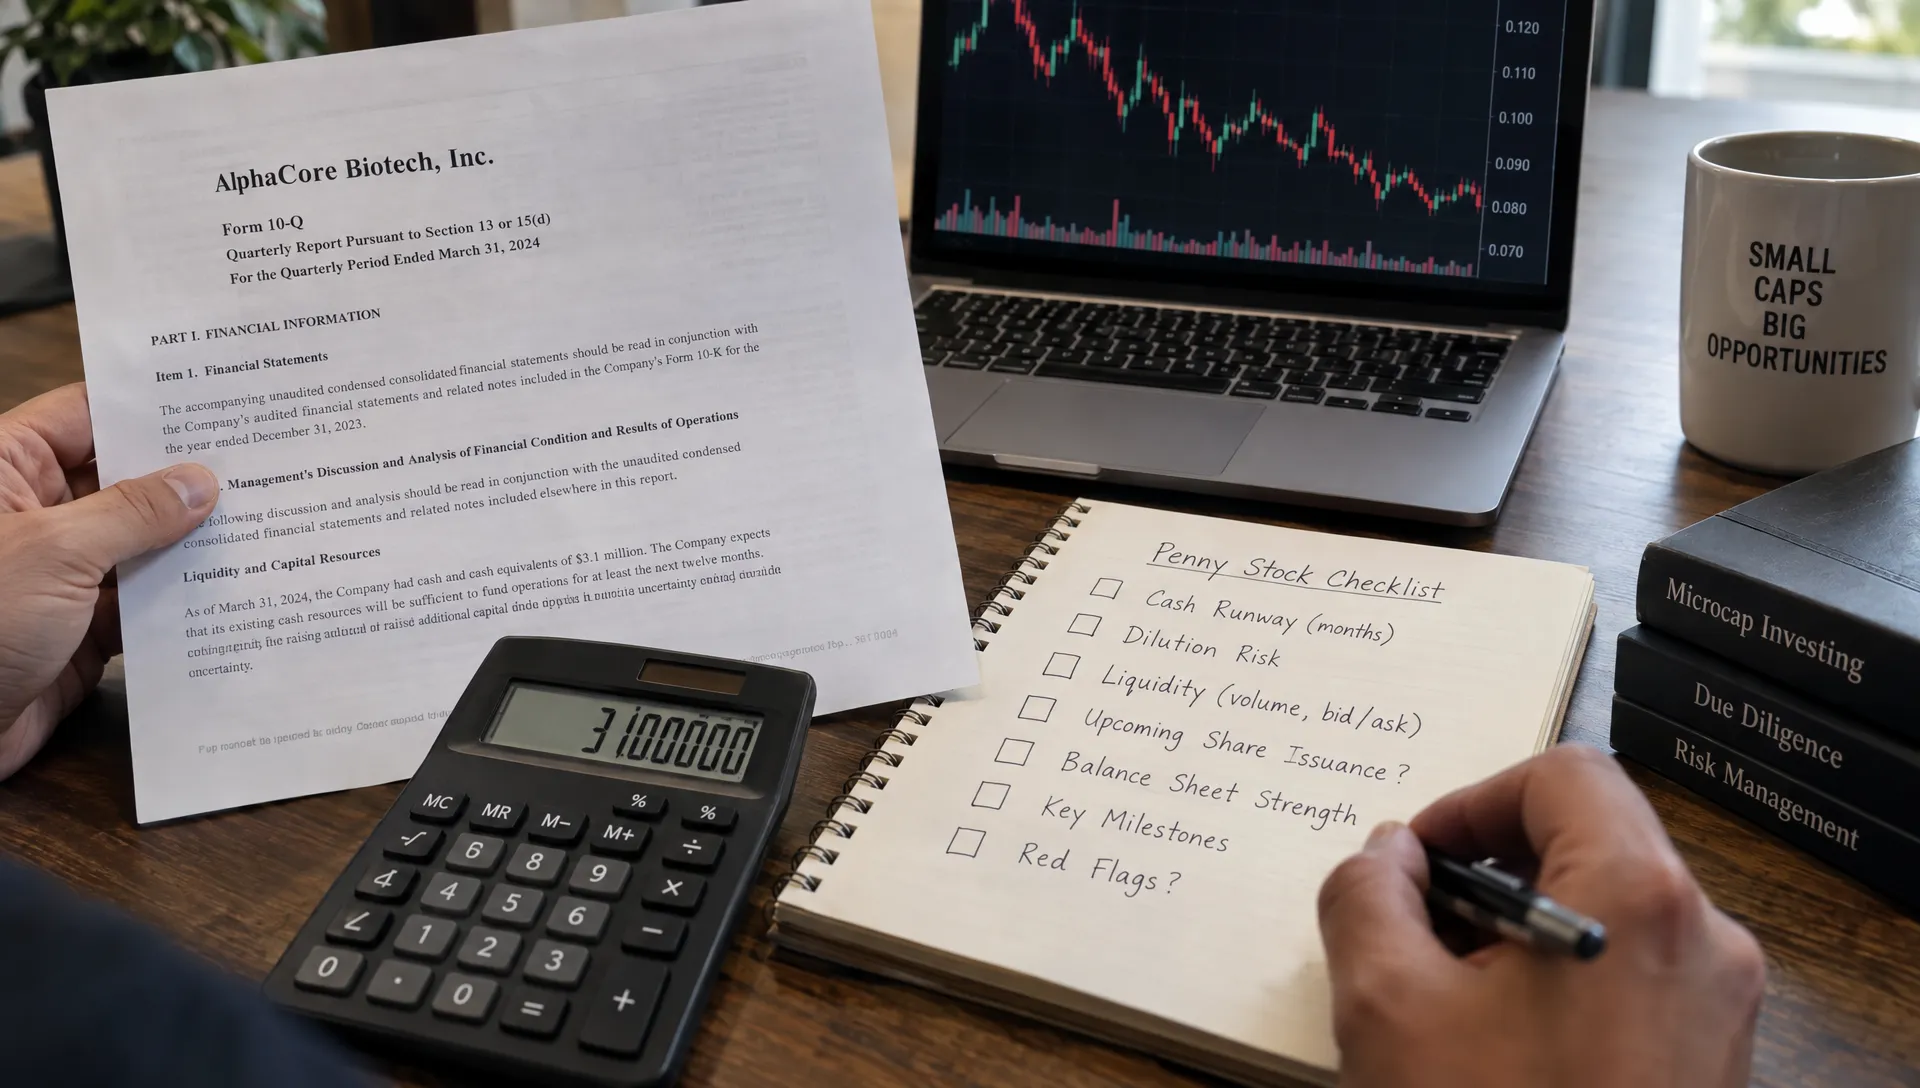
When reviewing the best upside penny stocks, trace how the company has funded itself over several reporting periods. Recurring share issuance can reveal a business model that depends on investors supplying cash rather than customers generating it.
Calculate cash runway through the next milestone
A rough runway estimate divides available cash by average monthly cash consumption. It is a starting point, not a forecast.
Consider a hypothetical company with $6 million of unrestricted cash and monthly cash consumption of $1.2 million. Its simple runway is five months. If management expects a commercially meaningful milestone in nine months, the funding gap deserves attention before you value that milestone.
Adjust the calculation for debt payments, necessary capital expenditures and other committed outflows, without counting expenses twice. Restricted cash may not be available for ordinary operations. An undrawn credit facility is useful only to the extent that its conditions permit access.
Use several quarters to understand seasonality and changes in spending. A single quarter can misrepresent cash needs, especially when customer payments or development expenses are uneven.
For the best upside penny stocks, the relevant question is whether existing funding can carry the business to evidence that changes its prospects. Management’s expectation of future financing is not the same as committed capital.
Model dilution before calculating a target price
Read the terms of outstanding warrants, options, convertible securities and preferred stock. A basic share count may omit claims that materially change future ownership. Accounting diluted earnings-per-share figures can also exclude instruments that are antidilutive for that calculation.
Here is an illustrative financing scenario: a company has 20 million shares and raises $5 million by issuing 10 million new shares at $0.50 each. An existing shareholder’s ownership percentage falls by one-third, assuming no participation in the offering and no other share changes.
If your modeled future equity value is $40 million, including the financing’s effects and planned spending, that value divided by 30 million shares implies about $1.33 per share. Using the old 20 million share count would incorrectly imply $2.
This is not a claim that financing always destroys value. New capital can keep a business operating or fund productive investment. It is a reminder to model both the use of proceeds and the resulting ownership.
The best upside penny stocks should be evaluated using a plausible future share count, not whichever denominator produces the largest target. Variable-price conversion provisions, exercise conditions and repeated reverse splits warrant additional scrutiny.
Verify business activity independently of promotion
Compare investor presentations with reported revenue, customer concentration, receivables and cash collection. A press release about an agreement is not necessarily evidence of recognized revenue. Determine whether a contract is binding, conditional, cancellable or still awaiting implementation.
For small businesses pitching a digital customer-acquisition strategy, services such as website optimization and local SEO can support legitimate marketing efforts. A redesigned website or better search visibility, however, does not establish recurring revenue or solvency. Look for financial evidence that the strategy is producing paying customers.
Examine promotional disclosures, including who paid for coverage and whether the publisher holds shares. Paid promotion does not automatically make every claim false, but it creates an incentive you need to understand.
Apply the same discipline to analyst targets and social-media forecasts. Upside Invest’s guide to evaluating huge-upside claims provides a complementary framework for checking assumptions and conflicts.
A shortlist of the best upside penny stocks should survive without anonymous posts, promotional price targets or a polished presentation. If removing those materials leaves no verifiable investment case, stop the analysis.
Write downside triggers before choosing a position size
Describe the conditions that would invalidate your thesis. Use observable events, such as a financing on materially worse terms than modeled, a missed debt payment or a commercial milestone that fails to occur within the assumed window.
Separate a price decline from a business deterioration. Either can matter, but they require different responses. A falling quote does not prove your analysis is wrong, and a rising quote does not repair a funding deficit.
Position sizing should reflect the possibility of losing the entire amount invested. As an illustration, if an investor chooses a maximum complete-loss budget of 0.5% of a portfolio, a $100,000 portfolio would permit $500 under that rule. This is an example of a sizing method, not a recommended allocation.
For the best upside penny stocks, sizing should also account for overlap with other speculative holdings. Several companies dependent on the same financing conditions or market theme may fail together, even when their businesses appear different.
Do not treat a stop-loss as a substitute for controlling exposure. Trading halts, gaps and disappearing liquidity can prevent the planned exit. Money needed for near-term obligations should not depend on successfully selling a speculative position.
Use verified portfolios as context, not clearance
Upside Invest provides verified investor holdings, portfolio comparisons and return and Sharpe metrics. Those features can help you examine how a speculative stock fits alongside other allocations rather than judging it in isolation.
A verified holding confirms portfolio information within the platform’s verification process. It does not verify the issuer’s financial health, guarantee a profitable trade or establish that the position suits your circumstances.
The best upside penny stocks cannot be identified simply by copying a top-ranked investor. You may have a different purchase price, holding period, liquidity requirement or tolerance for loss. Historical rankings can also emphasize successful outcomes while making unsuccessful strategies less visible.
Use portfolio benchmarking against verified investors to investigate concentration and allocation differences. Ask whether a holding is a small speculative position or a major portfolio commitment, when that context is available.
Return and Sharpe comparisons also need care. Thin trading and stale prices can understate observed volatility, so attractive historical risk-adjusted metrics do not replace a liquidity review.
Keep a short, dated decision record
Before advancing a candidate, record the evidence supporting each gate. Your research note should distinguish confirmed facts from estimates and unresolved questions.
- Identify the latest applicable filings and any material events after the reporting date.
- Estimate runway, including debt obligations and necessary spending.
- Build a share-count scenario reflecting likely financing and relevant securities.
- Compare position size with ordinary trading activity and current bid-ask quotes.
- Record promotional conflicts, thesis-breaking events and a complete-loss budget.
Revisit the note after earnings, financing announcements or material changes in trading conditions. A screen is only useful if its inputs remain current.
Screening the best upside penny stocks should produce a documented decision to reject, monitor or investigate further. It should not create pressure to buy something merely because it passed an initial filter. Passing means fewer unanswered questions, not low risk.
Frequently asked questions
Does an exchange listing make a penny stock safe? No. Listing requirements provide a baseline, but an exchange-listed company can still suffer severe dilution, financial distress or delisting. Review the issuer’s finances and current compliance disclosures.
Is high trading volume enough to prove liquidity? No. Promotional activity can temporarily inflate volume. Check typical dollar volume, bid-ask spreads and market depth, then consider how those conditions might change during a selloff.
Can profitable penny stocks still need financing? Yes. Accounting profit does not guarantee available cash. Receivables, inventory, capital spending and debt repayments can create funding needs. Compare earnings with cash flow and contractual obligations.
How often should I rescreen a candidate? Update the analysis after material filings, financings, debt changes or missed milestones. The best upside penny stocks can move off your shortlist when new information changes runway, dilution or exit capacity.
Compare portfolio context after the stock passes your checks
Once a candidate clears your disclosure, funding and liquidity review, use Upside Invest to compare verified holdings and portfolio allocations. Treat community data as additional context for a documented decision, not a replacement for issuer research or a reason to accept risks you cannot afford.