High Upside Stocks Need a Better Sell Discipline
High upside stocks can create the most exciting gains in a portfolio, but they also punish vague thinking. Buying is often the easy part because the story is fresh, the potential looks large and the market has not fully agreed with you yet. Selling is harder because every move feels like a referendum on your judgment. If the stock rises, you fear selling too early. If it falls, you tell yourself the thesis simply needs more time.
That emotional gap is why the sell decision deserves its own process. A good exit plan does not mean you lack conviction. It means you know the difference between a stock that is still mispriced and a stock that is now being held mostly because it once had a compelling story.
Why high upside stocks need sell discipline before you buy
A sell plan should exist before the position starts moving because your objectivity declines once real money and real gains are involved. Investors often define upside as a price target, but the actual decision is broader: What must happen for the thesis to remain valid, what would prove it wrong and what price would make the remaining return unattractive?
The danger with high upside stocks is that the original reason for buying can quietly change. You may start with a view on revenue acceleration, margin expansion or a new product cycle, then end up justifying the position because other investors are still excited. That shift matters. A stock can remain popular long after the risk and reward have deteriorated.
Sell discipline is not the same as pessimism. It is a way to keep the position tied to evidence, not hope.
The sell problem: upside is not static
Upside changes every day because price, fundamentals and expectations change. A stock that offered a potential double at $20 may be far less attractive at $42, even if the company is executing well. The business may be better than it was, but the stock may no longer be cheap relative to the new expectations.
For high upside stocks, the key question is not whether the company is still good. The question is whether the remaining upside still compensates you for volatility, dilution risk, competitive risk and the opportunity cost of capital. If the answer has changed, your position size should probably change too.
A practical way to avoid stale thinking is to update the bull, base and bear case after major price moves or earnings reports. Upside is a live estimate, not a number you set once and defend forever. If you want a deeper framework, Upside has a separate guide on measuring investment upside with better context instead of relying on a single target price.
Thesis drift is the silent risk
Thesis drift happens when the reason you own a stock evolves without an explicit decision. Maybe the original catalyst failed, but a new narrative emerged. Maybe the company missed margins, but revenue was strong enough to keep investors engaged. Maybe the stock is down, but the community around it is still confident.
None of those facts is automatically bad. The problem is failing to rewrite the thesis honestly. If the investment case has changed, treat it as a new decision. Would you buy the same amount today at the current price, with the current information and the current risk profile? If not, holding the full position may be an accidental choice.
Build sell rules before the position works
A sell rule is useful only if it is specific enough to act on. “Sell when the thesis breaks” sounds disciplined, but it often leaves too much room for interpretation. A stronger rule connects the exit to observable evidence: valuation, fundamentals, position size, time or investor behavior.
A sell plan for high upside stocks should also separate partial trims from full exits. Not every risk requires abandoning the position. Sometimes the right move is reducing exposure after a large run, especially when the stock has become a larger share of your portfolio than intended.
Good sell discipline has a similar mindset to industrial engineering: define the operating limits before the system is under pressure. Technical service providers like BKL Engineering describe engineering as a process that runs from definition through commissioning, with safety and efficiency built in rather than patched on later. Investors can borrow that idea by defining failure points before volatility tests their judgment.
| Sell trigger | What it means | Possible action |
|---|---|---|
| Valuation reset | The stock price has risen faster than earnings power or cash flow expectations | Trim to restore expected return |
| Thesis break | A core assumption is contradicted by results, guidance or industry data | Exit or reduce until the thesis is rebuilt |
| Catalyst exhaustion | The event you expected has happened and is now reflected in price | Reassess upside instead of holding by default |
| Position creep | The stock has grown beyond your intended portfolio weight | Trim to manage concentration risk |
| Time failure | The thesis needed progress by a certain date and progress did not appear | Reduce or move capital to stronger opportunities |
| Crowding signal | Ownership or sentiment becomes stretched relative to fundamentals | Tighten risk controls and avoid adding late |
Size, trim or exit: not every sell decision is binary
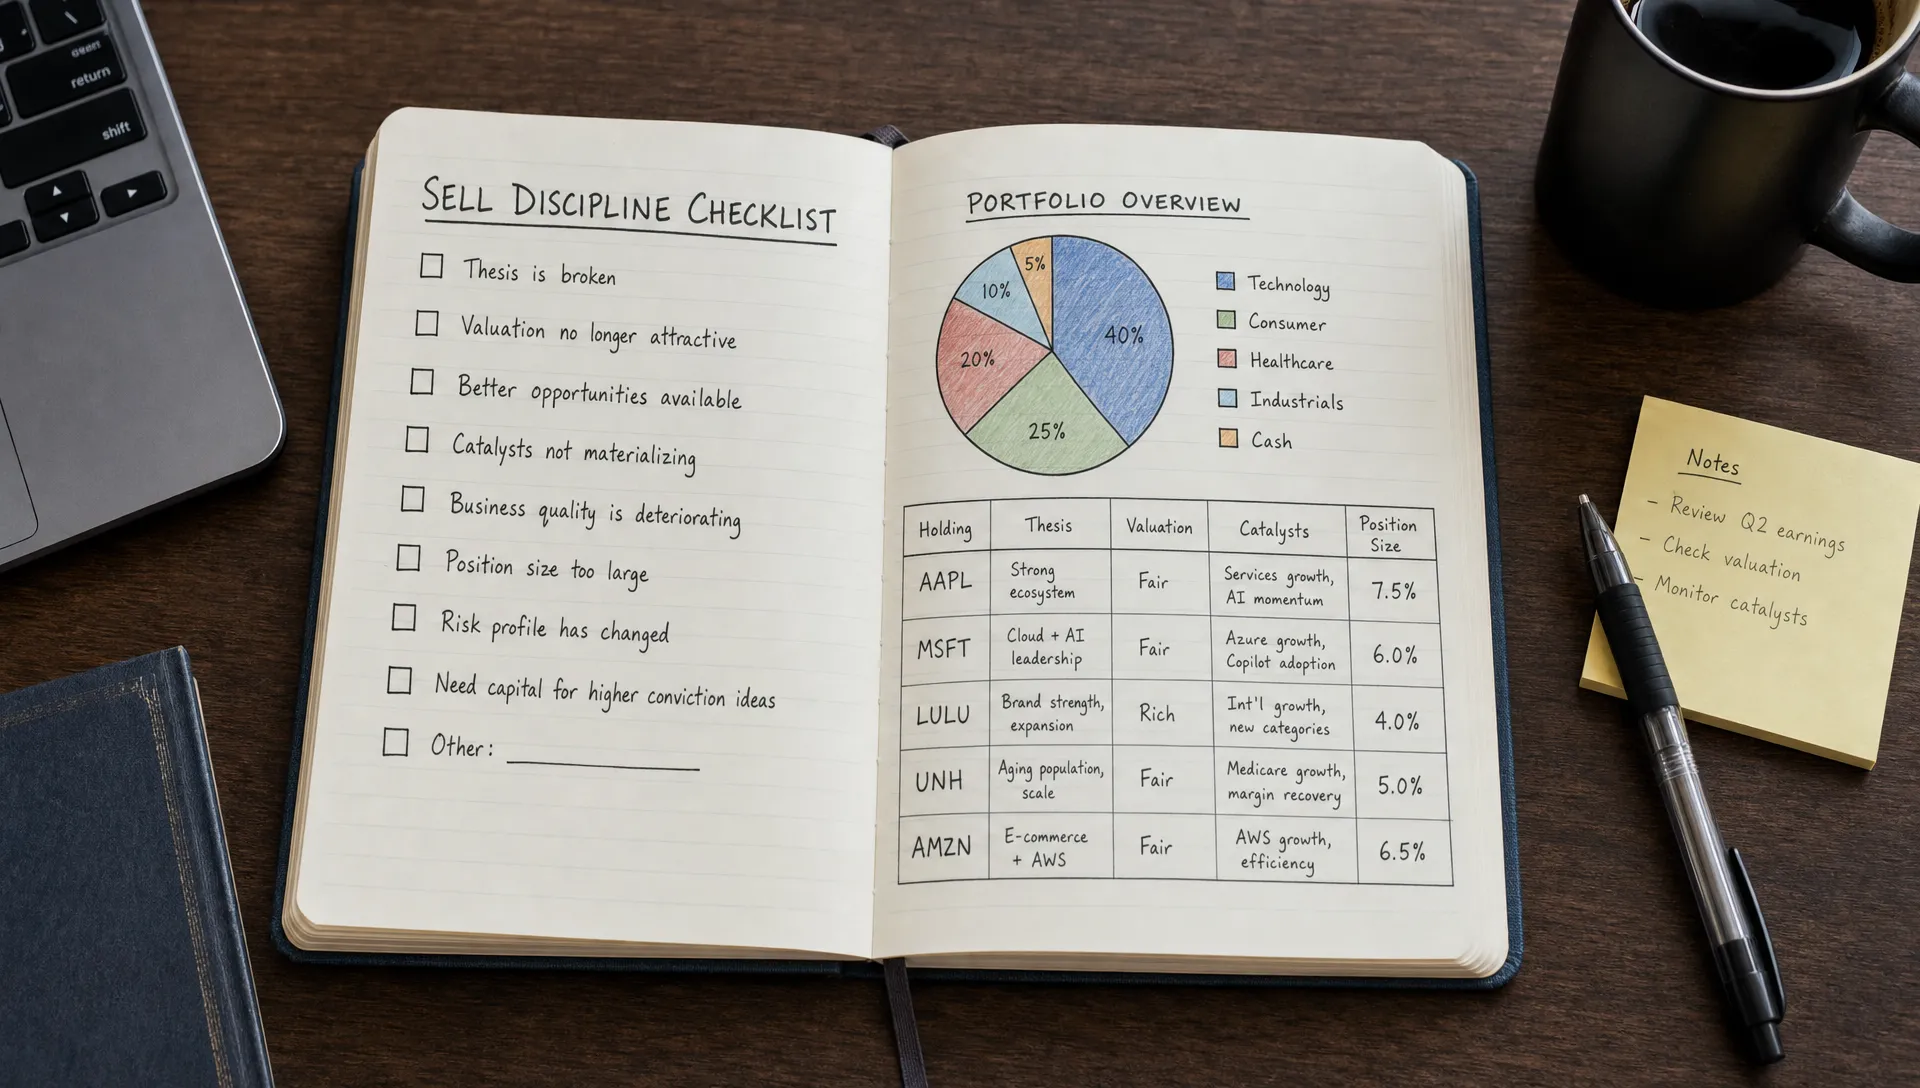
Many investors struggle with selling because they frame it as all or nothing. That framing is too blunt. A better sell discipline uses three actions: hold when the thesis and expected return remain strong, trim when the stock is still attractive but the risk and reward have narrowed, exit when the reason for owning has broken.
With high upside stocks, trimming can protect both capital and psychology. If a position has tripled and now dominates your portfolio, a partial sale can lock in gains while leaving room for the thesis to keep working. This is especially useful when the stock’s volatility could force a bad decision later.
Position size should reflect both conviction and fragility. A small biotech awaiting trial data, an early-stage software company and a profitable industrial compounder may all have upside, but their downside paths look different. Sell discipline should respect that difference. The more binary the outcome, the more valuable it is to decide in advance how much loss or volatility you are willing to tolerate.
When a winner deserves to stay
A stock does not become a sell just because it has gone up. Great investments often look expensive during the early part of a long compounding period. Selling every winner at the first sign of success can leave a portfolio full of slow ideas and missed optionality.
The better approach is to ask whether the company has grown into a larger opportunity. If the addressable market is expanding, execution is improving and the valuation is still reasonable relative to future cash flows, holding can be rational. The point is not to sell mechanically. The point is to re-underwrite the position with fresh evidence.
Before buying, it helps to define what would make you add, hold, trim or exit. Upside’s guide on testing the bull, base and bear case before buying is useful because strong exit decisions often start with a clearer entry thesis.
Use real investor behavior without copying it
Portfolio behavior can reveal information that headlines miss. If verified investors are increasing exposure to a stock after a strong quarter, that may signal growing conviction. If top performers are reducing a once-popular name despite bullish commentary, that may be worth investigating. The signal is not that you should copy them. The signal is that you should ask why behavior and narrative may be diverging.
The better question for high upside stocks is whether other investors’ actions confirm your thesis, challenge it or show crowding risk. A stock can become more dangerous when everyone who might buy has already bought. Momentum may continue, but the margin for disappointment shrinks.
This is where tools built around real portfolio data can help. Upside Invest emphasizes anonymous verified holdings, portfolio comparison, return and Sharpe metrics, trend tracking and alerts on investor moves. Those signals can support a sell discipline by showing how ownership behavior changes around catalysts, not just how loud the public narrative has become.
A practical sell discipline for high upside stocks
A simple sell framework is easier to follow than a complex one. The goal is to create rules that you can use under stress, when the stock is moving quickly and social proof is pulling you in several directions.
Start by writing the thesis in plain language. Include the business driver, the expected catalyst, the valuation case and the risk that would make you wrong. Then assign an intended position size. A 2 percent position and a 12 percent position should not have the same tolerance for uncertainty.
Next, define your review points. Earnings reports, major product updates, regulatory decisions, debt refinancing and competitive launches are all natural moments to revisit the position. If you only review after large price moves, price action will dominate your thinking.
Use this checklist when reviewing a position:
- Has the original thesis improved, weakened or merely changed?
- Is the remaining upside still attractive after the latest price move?
- Did the expected catalyst happen, fail or get pushed further out?
- Has the position become too large relative to your portfolio risk?
- Are stronger opportunities now available with better risk and reward?
- Are verified investor behaviors confirming conviction or signaling crowding?
The final step is documenting the decision. If you hold, write why. If you trim, write what would make you sell more or buy back. If you exit, write what evidence would change your mind. This short record reduces hindsight bias and helps you improve across future trades.
Frequently Asked Questions
When should I sell a high-upside stock? Sell when the thesis is broken, the remaining upside no longer compensates for the risk or the position has become too large for your portfolio. A trim can be more appropriate than a full exit when the company is still executing but valuation has become less attractive.
Should I use stop losses for high upside stocks? Stop losses can help control downside, but they should match the stock’s volatility and the reason you own it. A tight stop on a naturally volatile company can force you out for noise, while no exit rule can leave you exposed to a real thesis break.
Is taking profits too early a mistake? It can be, especially if the business is compounding faster than the market expected. The better question is whether the remaining expected return still justifies the risk. Taking partial profits can balance regret risk with portfolio protection.
How can portfolio data improve sell decisions? Verified portfolio data can show whether informed or high-performing investors are adding, holding or reducing exposure. It should not replace your own analysis, but it can reveal changes in conviction, crowding and momentum that price charts alone may miss.
Make upside work with downside control
High-upside investing does not fail only because investors pick the wrong stocks. It also fails when they pick promising stocks, then lack the discipline to adjust as facts change. The sell decision is where valuation, psychology and portfolio construction meet.
If you want to compare your portfolio against verified investors, track trends and understand how top performers are positioning, Upside Invest can help you turn anonymous real portfolio behavior into a more informed process. Use it as another layer of evidence, then make the final decision through your own sell discipline.
This article is for educational purposes only and is not financial advice.