How Interest Rate Expectations Shape Forex Market Direction
Interest rate expectations can change forex market direction before a central bank announces anything. A currency may strengthen while its central bank is cutting rates or weaken immediately after a hike. The apparent contradiction disappears when you compare the decision with what investors had already priced in, then examine how expectations changed relative to the other currency in the pair.
For retail investors, the useful question is not simply which country has the highest interest rate. It is whether the expected return from holding one currency is becoming more or less attractive after accounting for inflation, financing costs and risk. That comparison can shift after an inflation report, a jobs release or a few sentences from a central bank governor.
The core principle: Currencies often respond to changes in the expected policy gap between two economies, rather than the direction of either country’s latest rate decision. That is a starting point for analysis, not a reliable trading rule by itself.
How interest rate expectations influence forex market direction
Interest rates affect the return available on cash and short-term investments denominated in a currency. When investors revise one country’s expected rates upward relative to another’s, that can support demand for its currency through unhedged investment flows and changes in positioning.
Exchange rates are forward-looking. Markets price a range of possible policy paths, including the timing of the next move, the number of subsequent cuts or hikes and where rates might eventually settle. A change expected to persist can matter more than a temporary adjustment.
The comparison is always relative. EUR/USD measures the dollar price of one euro. A rise means the euro strengthens against the dollar; a fall means it weakens. If expectations become more favorable for US interest rates but equally more favorable for euro-area rates, the relative advantage may barely change.
Why a rate hike can weaken a currency
Suppose investors anticipate a large hike followed by several more increases. The central bank delivers a smaller hike and signals that tightening is nearly finished. The policy rate has risen, but the expected future path has fallen relative to prior assumptions.
That repricing can push forex market direction against the currency receiving the hike. Conversely, a widely expected rate cut can accompany currency strength if policymakers imply fewer additional cuts than investors had anticipated.
This distinction separates the announcement from the surprise. Headlines describe what happened; prices respond to what changed compared with expectations. The accompanying statement, press conference and economic projections can therefore outweigh the announced decision.
The Federal Reserve’s meeting calendar provides statements, minutes and projections when available. Projections describe policymakers’ assessments under their assumptions, not a binding promise about future rates.
A hypothetical EUR/USD repricing example
Consider the following simplified expectations for overnight policy rates 12 months ahead. All figures are hypothetical, not current market quotes. The comparison uses a representative US policy rate and the European Central Bank’s deposit facility rate.
| Scenario | Expected US rate | Expected euro-area rate | US rate advantage |
|---|---|---|---|
| Starting expectations | 3.50% | 2.50% | 1.00 percentage point |
| Softer US outlook, euro-area path unchanged | 3.00% | 2.50% | 0.50 percentage points |
| Firmer US outlook, euro-area path unchanged | 4.00% | 2.50% | 1.50 percentage points |
In the second scenario, the expected US rate advantage narrows by 50 basis points. All else equal, that removes some support for the dollar and can favor a higher EUR/USD exchange rate.
In the third scenario, the advantage widens. That can favor the dollar and a lower EUR/USD rate. Neither scenario produces a mechanical exchange-rate target.
The lesson for forex market direction is to track changes in the expected gap, not compare two policy rates in isolation. If European expectations fall even faster than US expectations, the dollar’s relative advantage could widen despite anticipated Federal Reserve cuts.
The size of the exchange-rate response also depends on positioning, uncertainty and the reason for the repricing. A modest surprise can move a crowded market sharply, while a large but well-anticipated adjustment may generate little lasting movement.
Where to find evidence of changing expectations
No single instrument reveals a perfectly clean forecast. Use a consistent set of sources and understand what each measures before drawing conclusions.
Rate futures and overnight index swaps
Interest rate futures and overnight index swaps, commonly called OIS, help investors infer expected short-term interest rates across future dates. OIS contracts exchange a fixed rate against a floating rate linked to an overnight benchmark.
For US policy, CME FedWatch translates federal funds futures pricing into model-based probabilities for Federal Reserve outcomes. These probabilities depend on market prices and calculation assumptions. They are not survey results or guarantees.
When assessing forex market direction, compare expectations for both currencies over the same horizon. Comparing one country’s next meeting with another country’s year-end outlook can create a misleading divergence.
Record when the data were captured. A futures snapshot taken before an inflation release cannot fairly be compared with a foreign rate curve captured afterward. Also distinguish the expected rate at a future date from a contract’s average rate over an accrual period.
Two-year government yields and real yields
Two-year sovereign yields offer a widely followed cross-check because they are sensitive to the near-term policy outlook. A widening US-German two-year yield spread, for example, can indicate changing relative support for the dollar against the euro.
However, a government bond yield is not a pure policy forecast. Term premiums, sovereign credit considerations, liquidity and bond-specific demand can affect it. German government bonds also serve as a reference for euro-area markets without representing every member country’s borrowing conditions.
Real yields add another perspective by adjusting nominal yields for inflation expectations. A rise in nominal yields caused mainly by higher expected inflation may send a different currency signal from a rise associated with tighter expected monetary policy.
For forex market direction, treat yield spreads as supporting evidence rather than a substitute for identifying the underlying policy surprise. The Bank of England’s yield-curve data illustrates the distinction between government bond curves, real yield curves and OIS curves.
Do not compare unlike measures casually. A long-term inflation-linked yield in one country and a short-term nominal yield in another answer different questions.
A practical routine for interpreting the next catalyst
A repeatable process helps separate an actionable change in expectations from a plausible explanation applied after prices have already moved.
1. Establish the starting expectations
Choose one currency pair and one horizon, such as the next three central bank meetings. Record each side’s expected policy path using comparable instruments where possible. Add the current exchange rate, the relevant two-year yield spread and the next scheduled economic releases.
Your starting view should describe a relative change that could occur. For example: “Markets may reduce expected US easing more than expected euro-area easing if US inflation remains persistent.” That is more testable than “the dollar looks strong.”
Write down the evidence that would contradict the view. This keeps your interpretation of forex market direction tied to observable developments rather than a preferred trade. It also prevents you from treating every new headline as confirmation.
2. Separate the data surprise from the policy response
Compare a release with consensus expectations, its prior reading and any revisions. Then check whether the rate market actually repriced. Above-consensus inflation does not automatically imply a more restrictive policy path if the details look temporary or growth deteriorates sharply.
Identify which part of the path changed. Traders might postpone the first cut without changing their expected year-end rate. Alternatively, they might leave the next meeting unchanged but raise the expected longer-run policy rate.
Those outcomes need not produce the same currency response. Check both sides of the pair: domestic news can be overshadowed by a larger surprise abroad.
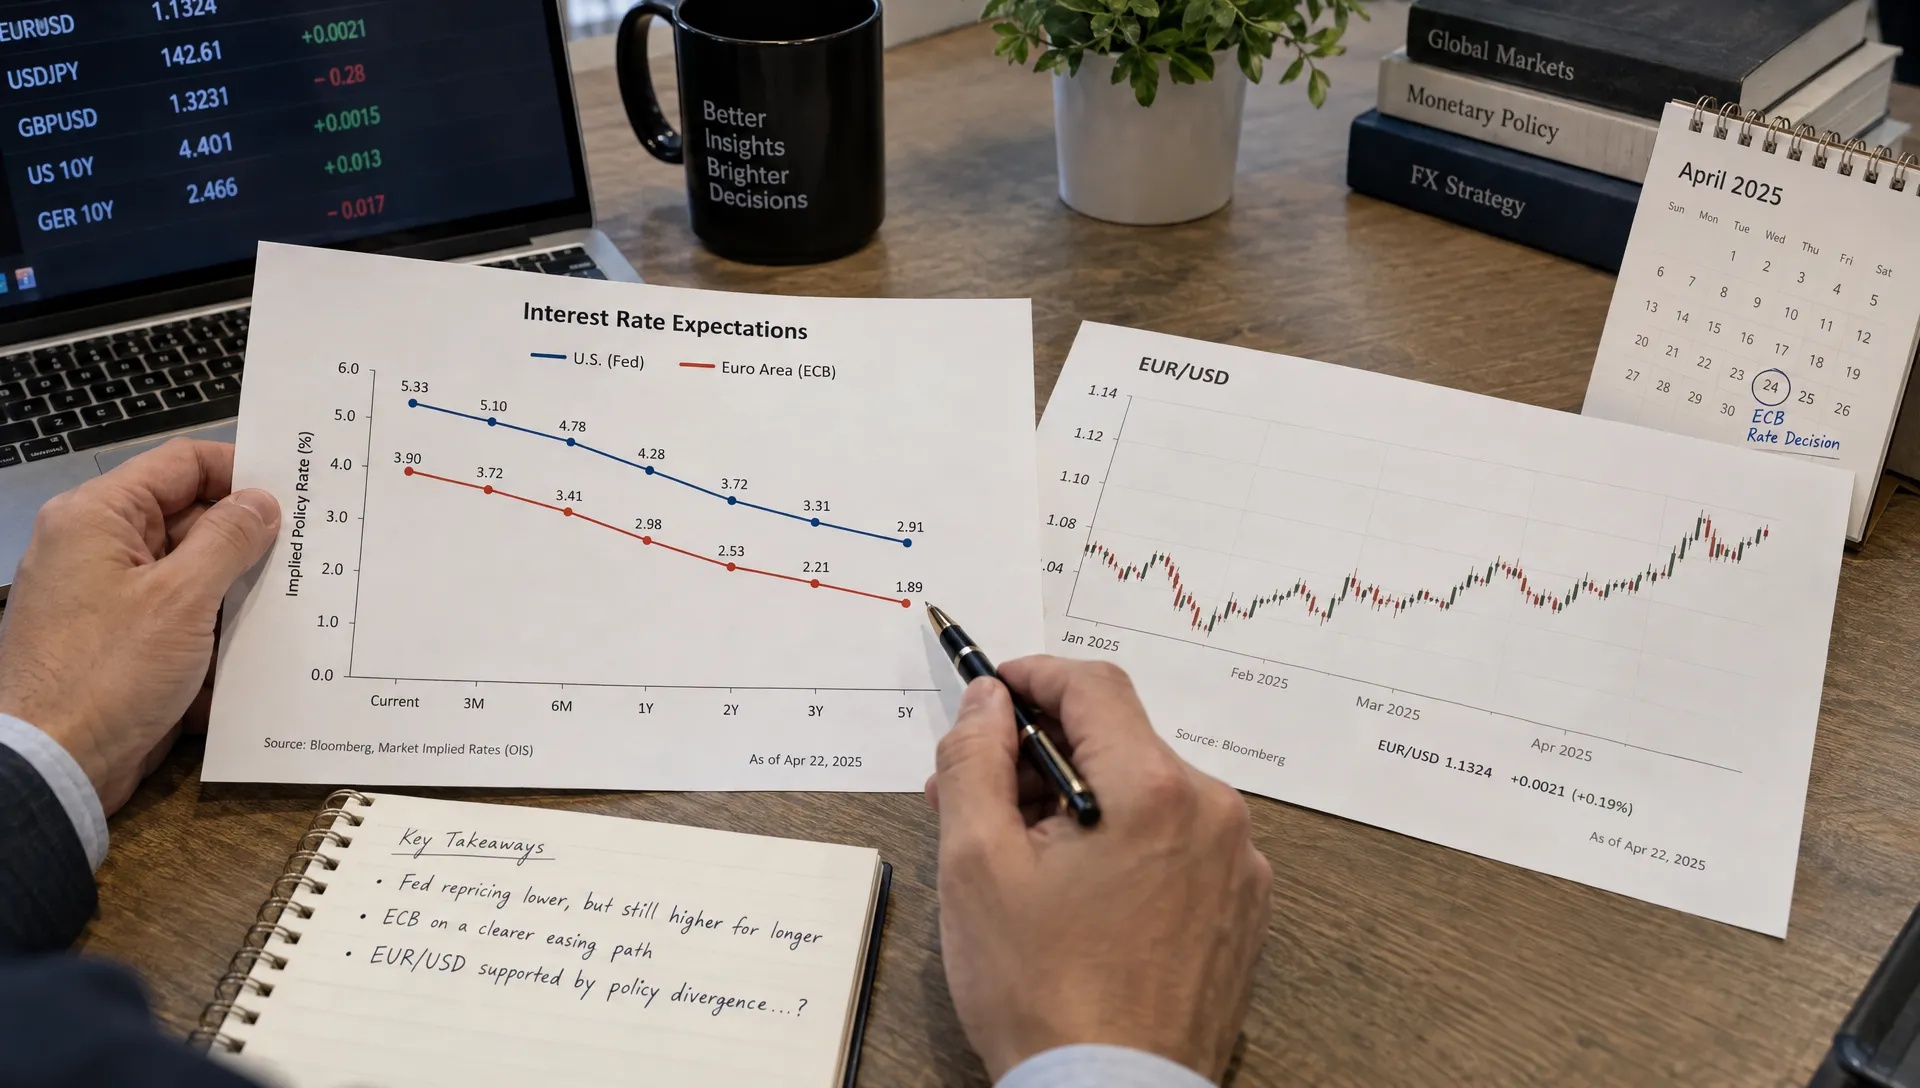
3. Check whether the exchange rate confirms the repricing
Compare the currency’s response with its recent price structure rather than relying on the first move after a release. An initial dollar rally that reverses despite higher US yields may indicate that the policy surprise was insufficient, positioning was crowded or another force dominated.
Use timeframes that fit your decision. A five-minute reaction can run against a daily trend without invalidating it. For a multiweek view, sustained daily behavior usually deserves more weight than an isolated intraday spike.
When price action and rate expectations disagree, reduce confidence rather than forcing a conclusion about forex market direction. Waiting is a valid outcome. Upside’s guide to identifying a trending forex market explains how price structure can provide a separate confirmation layer.
Keep the distinction clear: a chart can confirm that buying pressure persists, but it cannot prove why buyers are acting.
4. Define invalidation before considering exposure
A policy-based thesis needs both an economic invalidation point and a risk limit. The economic thesis might fail if the relative rate repricing reverses. A position can still require an earlier exit because its predefined loss limit has been reached.
Position size should reflect potential loss, not confidence in the economic narrative. With leveraged forex exposure, a relatively small exchange-rate move can create a large account loss. Spreads can widen and orders can execute away from intended levels around announcements.
Avoid increasing exposure simply because several positions share the same favorable story. Long dollar positions against three currencies may behave like one concentrated dollar bet.
A sound interpretation of forex market direction is therefore only one input. Execution costs, portfolio concentration and the possibility of a false initial move remain separate decisions. Being right about the eventual policy path does not ensure that a particular trade survives the route there.
When the rate signal becomes less reliable
Risk aversion and country-specific stress
During a market shock, demand for liquidity or perceived safety can outweigh a narrowing rate advantage. The US dollar may strengthen even as investors price Federal Reserve cuts. Other currencies can also benefit from defensive flows, but those responses depend on the nature of the shock.
Higher yields can be a warning rather than an attraction when they reflect inflation instability, fiscal concerns or rising credit risk. Investors care about the quality and accessibility of returns, not just their headline level.
This is why the same yield increase can accompany different forex market direction in different environments. Identify whether yields are rising because of stronger growth, tighter expected policy or a larger risk premium before interpreting the move.
Carry, hedging and crowded positioning
A higher-yielding currency does not offer a free return. An unhedged carry trade earns an interest differential while remaining exposed to exchange-rate losses. Those losses can overwhelm the income received.
For a currency-hedged investment, forward pricing generally reflects the interest rate differential, subject to market frictions and cross-currency basis effects. A forward exchange rate is therefore not a straightforward prediction of future spot prices.
Positioning creates another limit. If many investors already hold the same rate-divergence trade, favorable news may attract few additional buyers. Upside’s explanation of why trending trades can reverse explores how crowding and priced-in catalysts can undermine an otherwise coherent thesis.
Frequently asked questions
Do higher interest rates always strengthen a currency? No. Higher expected rates can support a currency, but the outcome depends on what was already priced in, the other currency’s outlook and the reason rates are rising. Inflation or financial stress can weaken a currency even as yields rise.
Can a currency rise after an interest rate cut? Yes. A cut can be less dovish than expected, particularly if investors anticipated a larger reduction or more follow-up cuts. The currency can also benefit when the other central bank’s expected easing path becomes more aggressive.
What is the best indicator of forex market direction? No single indicator is consistently sufficient. For an interest-rate-based view, combine relative policy expectations, comparable yield spreads and exchange-rate behavior. Agreement strengthens the interpretation, but it does not establish a certain outcome or remove trading risk.
How quickly do rate expectations affect exchange rates? Liquid currency pairs can react within seconds of major news. The interpretation may keep changing through the press conference, subsequent trading sessions and later data releases. A longer-term policy thesis should not be confused with a precise forecast for the next few minutes.
Put the currency view in portfolio context
Interest rate analysis is most useful when it changes a specific decision: reducing a concentrated currency exposure, testing an investment assumption or deciding that the evidence is too mixed to act.
For a broader perspective, Upside Invest offers anonymous portfolio sharing and comparison using verified investor holdings. That can complement your assessment of portfolio allocations and concentration, but it does not replace current rate-market data or turn a macroeconomic view into a guaranteed return.