How to Turn Private Equity Insight Into Better Research
A buyout announcement can tell you where a sophisticated buyer sees opportunity, but it cannot tell you whether a stock belongs in your portfolio. The most useful private equity insight is a testable claim about a business: where cash comes from, what could improve and which assumptions must hold for the investment to work.
For retail investors, that means looking past the sponsor’s reputation and the transaction headline. A buyer may have control rights, financing terms or access to information that you do not. Its investment horizon and tolerance for illiquidity may also be very different.
The goal is not to copy a private equity firm’s purchase. It is to use the deal to identify better questions, gather stronger evidence and build a valuation that survives less favorable conditions. This approach works whether you are studying a public-market competitor, a listed investment vehicle or an industry undergoing consolidation.
What private equity insight can and cannot tell you
Private equity firms generally invest in privately held businesses, although they may also acquire public companies and take them private. Their investment plans can involve operational changes, acquisitions, debt repayment and an eventual sale or public offering.
A transaction therefore contains several possible signals. The buyer might see durable demand, opportunities to improve margins or a fragmented market where smaller businesses can be combined. Alternatively, the investment may depend heavily on favorable financing or an optimistic exit valuation.
A purchase establishes that a buyer accepted a particular set of terms, not that the asset was objectively cheap. Without knowing those terms and the underlying assumptions, the headline provides limited valuation evidence.
Treat private equity insight as a starting hypothesis rather than a conclusion, especially when applying a private transaction to a publicly traded company.
Build an evidence trail before building a model
Start with the original transaction announcement, then separate confirmed facts from the buyer’s interpretation. Record the announcement date, expected closing date, ownership stake and whether the transaction actually closed.
Terms matter. A reported transaction value may describe enterprise value, equity value or a figure that includes contingent payments. Those amounts are not interchangeable. If the release does not explain the basis, mark it as unresolved rather than filling the gap with an assumption.
For public companies involved in a deal, use SEC EDGAR filings to locate financial statements, merger documents and material agreements where available. A merger proxy may provide projections or a financial adviser’s analysis, but those materials still need context about their purpose and assumptions.
A compact evidence log keeps the research honest:
| Research item | Evidence to capture | Remaining uncertainty |
|---|---|---|
| Transaction status | Announcement and closing disclosure | Whether conditions remain outstanding |
| Purchase price | Disclosed value and its definition | Debt treatment, earnouts or adjustments |
| Operating thesis | Specific improvements described by the buyer | Execution cost and achievable timing |
| Financial baseline | Revenue, earnings and cash flow disclosures | Missing or unaudited information |
| Financing | Available debt terms and maturity information | Refinancing exposure or undisclosed conditions |
Private equity insight becomes more actionable when every important claim has a source, a date and a clearly labeled information gap. Missing financial data should lower your confidence, not encourage a more elaborate spreadsheet.
Translate the deal thesis into operating questions
A useful thesis names the mechanism that could create value. “Attractive sector” is too broad. “Improving capacity utilization without a proportionate increase in fixed costs” gives you something to investigate.
Separate demand growth from acquisition growth
If a business is expanding through add-on acquisitions, distinguish purchased revenue from growth in existing operations. Ask whether acquired customers stay, whether integration costs are visible and whether the combined organization can deliver services more efficiently.
For a public-market comparison, look for organic revenue disclosures, segment results and acquisition-related adjustments. Rapid headline growth can coexist with weak underlying demand.
Test margins against cash conversion
EBITDA, earnings before interest, taxes, depreciation and amortization, is commonly used in deal analysis. It does not measure cash available to shareholders after capital spending, interest and other obligations.
Compare operating profit with operating cash flow and necessary reinvestment. Examine working capital, maintenance capital expenditures and recurring costs excluded from adjusted earnings. A business that reports improving EBITDA while absorbing more cash may require a different valuation than the headline suggests.
The strongest private equity insight identifies an improvement you can measure, such as customer retention or cash conversion, rather than relying on the buyer’s confidence alone.
Before moving to valuation, write down the evidence that would contradict the thesis. Rising customer losses, persistent integration charges or deteriorating cash conversion should trigger a review even when reported revenue continues to grow.
Stress-test leverage and the exit valuation
Buyout returns can come from business growth, debt repayment and a change in the valuation multiple. Separating those drivers helps you identify whether the investment depends on operational progress or a favorable future market.
Use a simple equity-value bridge
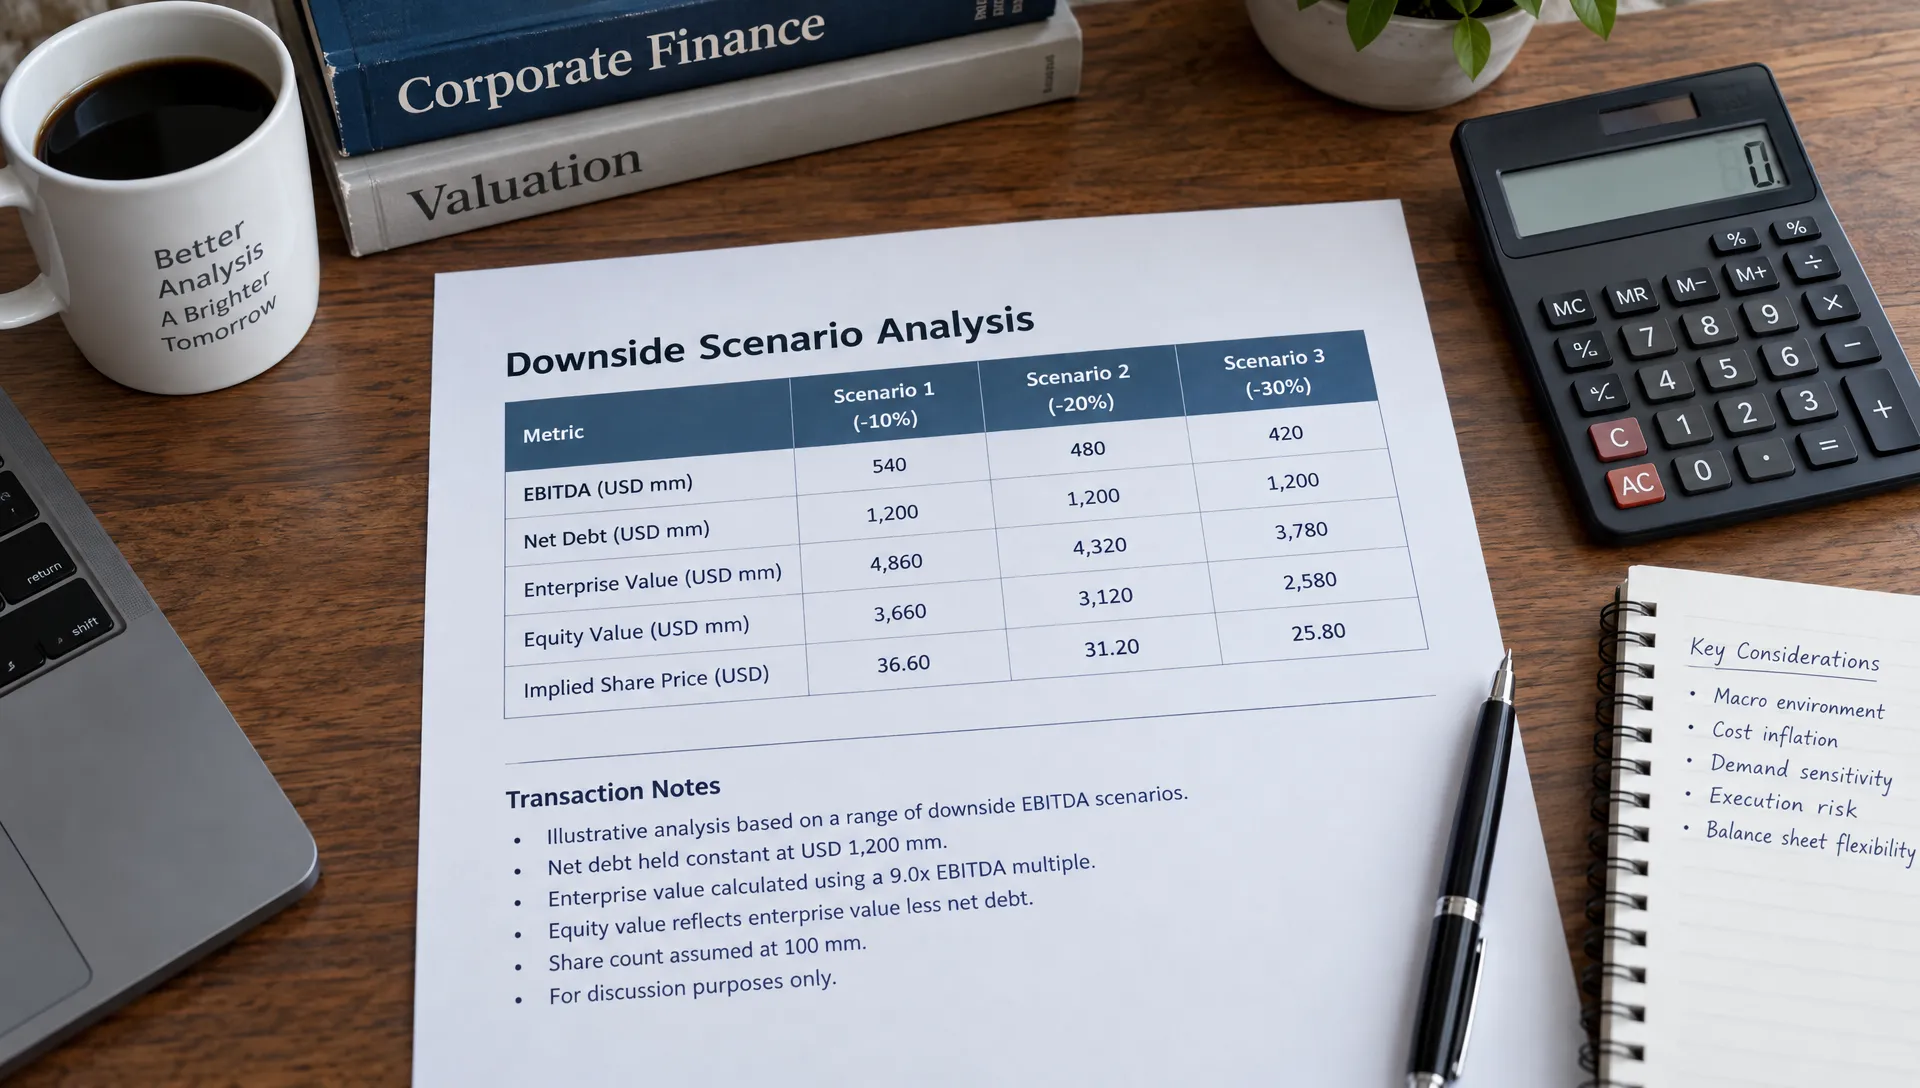
Consider a hypothetical acquisition with an enterprise value of $100 million, EBITDA of $10 million and net debt of $60 million. The entry enterprise-value-to-EBITDA multiple is 10 times and the simplified entry equity value is $40 million.
The following scenarios are arithmetic examples, not forecasts:
| Exit scenario | EBITDA | Exit multiple | Enterprise value | Net debt | Equity value | Gross equity multiple |
|---|---|---|---|---|---|---|
| Growth with debt repayment | $12 million | 10x | $120 million | $50 million | $70 million | 1.75x |
| Growth with multiple compression | $12 million | 8x | $96 million | $50 million | $46 million | 1.15x |
| Earnings decline with no debt repayment | $9 million | 8x | $72 million | $60 million | $12 million | 0.30x |
Equity value here equals enterprise value minus net debt. The calculation excludes fees, taxes, distributions, additional equity contributions and other claims on value. It also omits the holding period, so it is not an annualized return.
Identify assumptions that work against each other
Private equity insight should sharpen your downside analysis: higher earnings do not guarantee strong equity returns if valuation multiples fall or debt remains elevated.
Check interest costs, maturities, floating-rate exposure and refinancing needs. Then test a scenario where earnings weaken while financing becomes less favorable. Do not assume a company can simultaneously fund acquisitions, maintain investment and repay debt without examining its cash flow.
Validate the operating story with a sector example
Healthcare services illustrate why an industry label is not enough. A consolidation thesis might cite local fragmentation, repeated patient demand or shared administrative costs. Each claim needs business-level evidence.
For an initial service-mix exercise, Move Well MD’s overview of chiropractic, acupuncture, physical therapy and pain-management services provides a concrete example of the different services a practice may offer. Its website is a source for describing the business, not evidence of private equity ownership, profitability or investment suitability.
That distinction determines what you research next. Multiple services may create opportunities to coordinate care, but they do not establish attractive unit economics. Investigate reimbursement arrangements, clinician capacity, staffing costs and the cash required to operate each service line.
Similarly, repeated visits are not the same as contracted recurring revenue. Patient retention, collection timing and payer concentration can materially change the financial picture. Website descriptions alone cannot answer those questions.
A sector-specific private equity insight becomes useful only after you connect the broad thesis to measurable economics and relevant constraints. In this example, you would also examine professional ownership rules, reimbursement compliance and whether expansion affects care delivery or quality.
The same method applies elsewhere: identify the operating unit, understand who pays and determine which costs rise as the business grows.
Translate the findings into public-market research
A private acquisition can help you discover public companies worth studying, but the connection should be operational rather than superficial. Two businesses in the same sector may have very different customers, margins and capital requirements.
Compare revenue mix, geographic exposure, customer concentration and growth sources before comparing valuation multiples. Normalize financial definitions where possible. A multiple based on adjusted EBITDA is not directly comparable with one based on unadjusted operating earnings.
Also distinguish control economics from minority-shareholder economics. A sponsor may be able to replace management, sell assets or change capital allocation. Buying a small position in a public company does not give you those powers.
Ownership research can help clarify those differences. Upside’s guide to building a stock ownership profile explains how to examine insiders and major holders rather than treating ownership as a single percentage.
The purpose of private equity insight in this stage is to improve your comparable-company analysis, not to transplant a transaction multiple into a stock price target.
Before sizing a position, connect the thesis to your existing exposures. Several seemingly different holdings may depend on the same financing conditions, acquisition strategy or customer budget. Upside’s framework for measuring investment upside with better context can help separate potential return from the assumptions required to achieve it.
Create a one-page research memo
Keep the finished output short enough to revisit after the next earnings report or transaction update. A useful memo records the claim, supporting evidence and conditions that would change your view.
Use these fields:
- Investment question: The specific uncertainty you are trying to resolve.
- Operating mechanism: How the business could increase sustainable cash generation.
- Evidence: Primary documents, reporting dates and relevant financial definitions.
- Valuation range: Base and downside assumptions, including debt and exit multiples.
- Disconfirming evidence: Developments that would weaken or invalidate the thesis.
- Portfolio relevance: Existing exposures the investment would increase or diversify.
Label each major input as disclosed, calculated or assumed. That small distinction prevents an unsupported estimate from gradually becoming an accepted fact.
For example, “integration improves margins” remains an assumption until results support it. “Net debt declined during the reporting period” can be a disclosed fact, but you still need to determine whether repayment came from operating cash, asset sales or new equity.
Private equity insight earns its place in the memo only when it changes a research question, a valuation assumption or a risk judgment. If it merely adds a recognizable investor’s name, it has not improved the analysis.
Set review triggers tied to evidence, such as an acquisition closing, a debt refinancing or the next cash-flow statement. A trigger-based review is more useful than repeatedly checking whether market sentiment agrees with you.
Frequently asked questions
Does a private equity acquisition mean similar public stocks are undervalued? No. The purchase price may reflect control rights, buyer-specific synergies or financing arrangements unavailable to public shareholders. Comparable transactions can inform a valuation range, but they do not establish fair value for another business.
How should retail investors interpret reported private equity returns? First identify whether the figure describes a deal or a fund, whether it is gross or net of fees and whether it includes unrealized valuations. Internal rate of return incorporates cash-flow timing, while a multiple on invested capital compares value with invested capital. Neither metric alone fully explains risk or realized proceeds.
What if the target company does not disclose financial statements? Narrow the conclusion. You can study the sector, transaction structure and stated operating thesis, but you cannot reliably calculate valuation or debt capacity without adequate financial inputs. Record the missing information instead of substituting a confident estimate.
Can verified investor portfolios validate a private-market thesis? They can show how participating investors allocate capital and reveal related public-market exposures. They cannot establish a private company’s finances or prove an investment thesis. Use private equity insight alongside those signals, keeping business evidence separate from investor behavior.
Put the research into portfolio context
Once the thesis survives your evidence checks, examine what it would change in your portfolio. Upside Invest offers verified investor holdings, portfolio comparison tools and private anonymous profiles to help you explore allocations and community benchmarks.
Use that context to identify concentration and competing investment approaches. The decision should still rest on the business economics, the price you would pay and the downside you can tolerate.