Momentum Trend Trading and How It Differs From Mean Reversion
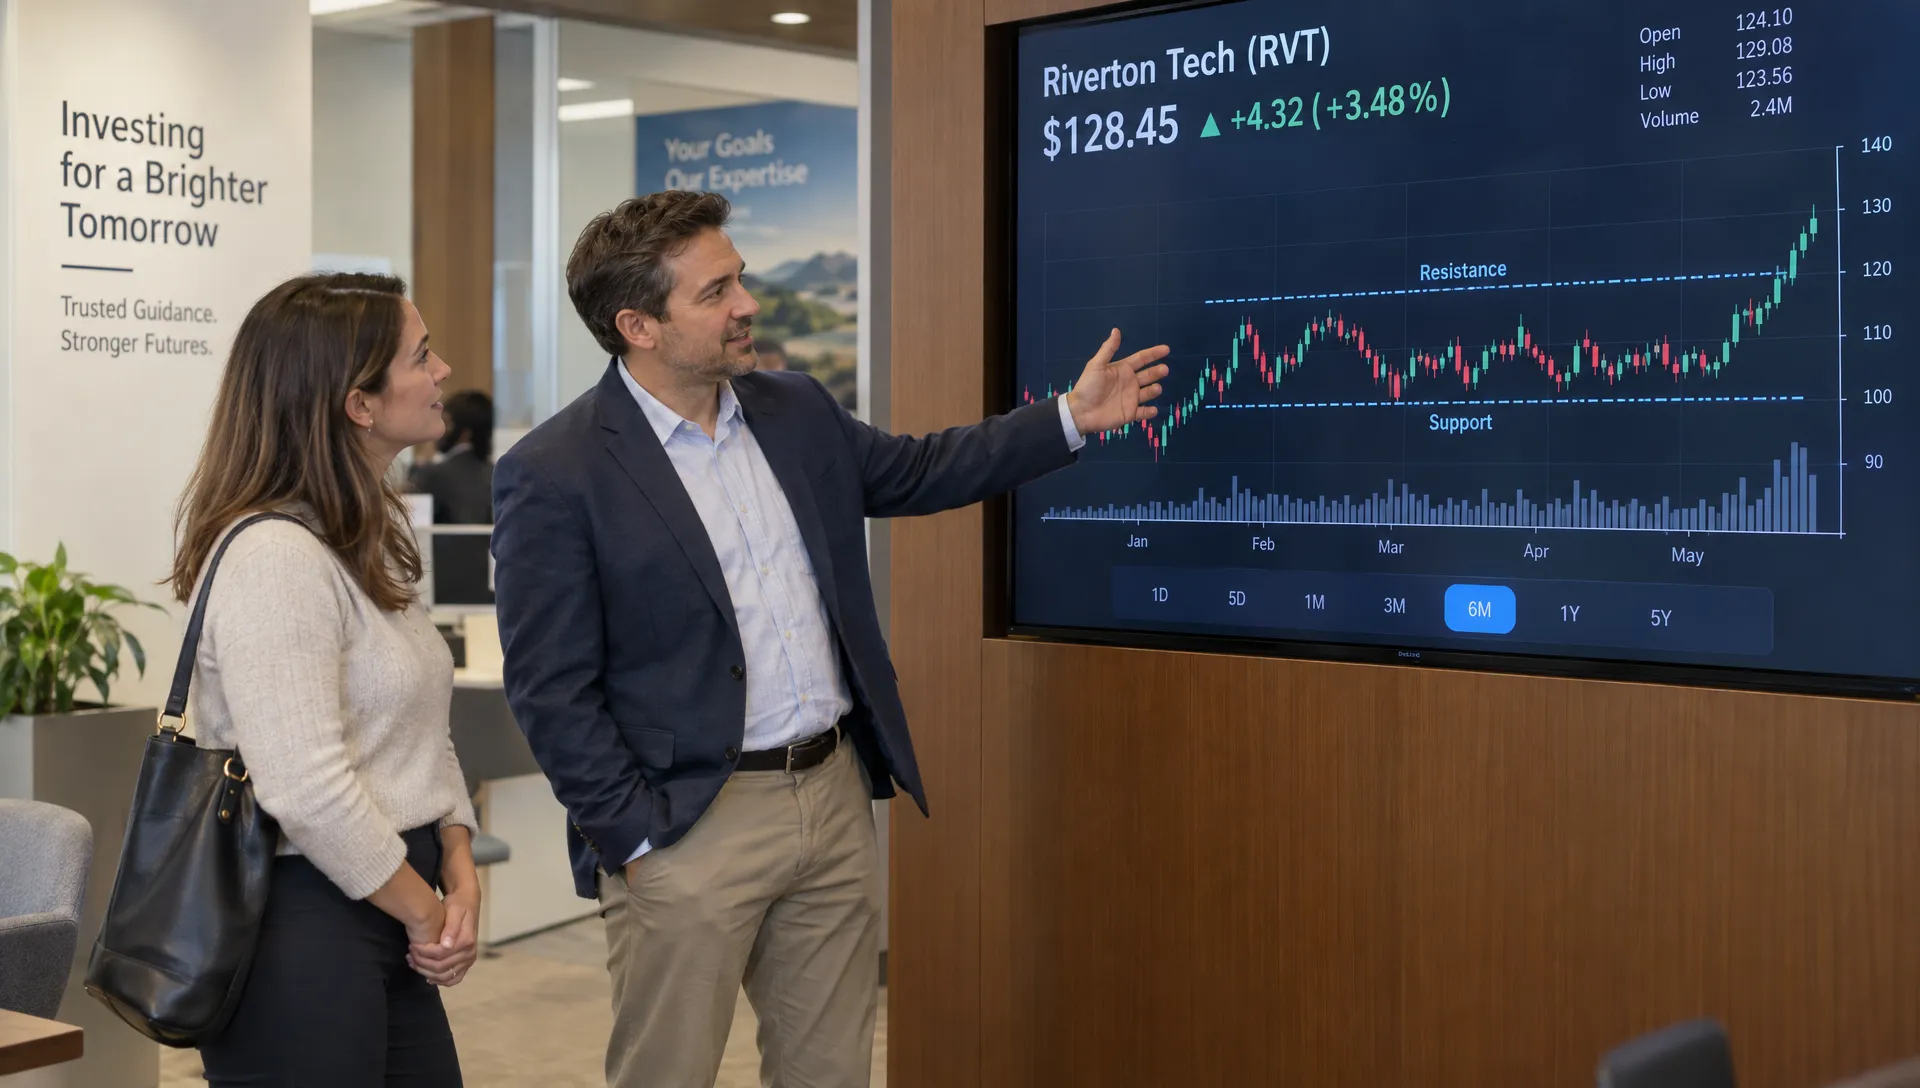
Momentum trend trading and mean reversion start with opposite expectations: one looks for a price move to continue, while the other looks for a stretched price to move back toward a reference level. That difference affects far more than entry timing. It changes what counts as confirmation, where a trade becomes invalid and how profits are taken.
Neither approach is automatically better. The useful question is whether your entry, exit and risk rules express the same hypothesis. Buying a breakout and then calling it a mean-reversion investment after it falls is not a strategy change supported by evidence. It is an unplanned change in the trade.
Continuation versus a return to normal
Momentum describes persistence in returns or price movement. Trend following is a way to trade persistent direction, often using breakouts, moving averages or other systematic rules. The concepts overlap, but they are not identical.
Time-series momentum compares an asset with its own past performance. Cross-sectional momentum compares assets with one another, looking for relative strength among recent winners and losers. A stock can outperform its peers while still declining, so relative strength does not necessarily mean an upward price trend.
Historical research on time-series momentum by Moskowitz, Ooi and Pedersen documents return persistence across a futures-market sample. That finding does not establish that any particular stock breakout or intraday setup will be profitable.
Mean reversion starts with a different hypothesis: a deviation from a chosen reference is likely to narrow. That reference might be a moving average, the middle of an established range or a statistically estimated relationship between assets.
The reference needs justification. A stock is not obliged to return to its historical average, especially after new information changes its earnings outlook or perceived risk.
How does momentum trend trading differ from mean reversion?
The clearest comparison is what each strategy expects to happen after an entry.
| Decision | Continuation approach | Mean-reversion approach |
|---|---|---|
| Core hypothesis | Directional persistence will continue | A deviation from a reference will narrow |
| Typical long setup | Breakout or pullback within an established uptrend | Decline below a justified reference, followed by evidence of stabilization |
| Supporting conditions | Sustained directional movement | Repeated two-way movement around a relatively stable reference |
| Invalidation | The expected continuation fails | The deviation expands beyond the strategy's tolerance or the reference stops being credible |
| Profit-taking logic | Stay invested while the trend remains valid | Exit as the price approaches the reference or target |
| Common failure | Repeated false breakouts | A supposed temporary deviation becomes a lasting repricing |
These are tendencies, not universal rules. Some continuation systems use fixed profit targets, while some convergence strategies use dynamic exits.
Holding period alone does not distinguish the approaches. Both can operate over minutes, days or months. Nor does the order type settle the question: buying a dip could be an attempt to catch a rebound within a range or an entry into a larger uptrend. The expected path after entry is what matters.
One price move, two different trade hypotheses
For momentum trend trading, a breakout is useful only if it supports an expectation of further movement, not simply because the price has reached a new high.
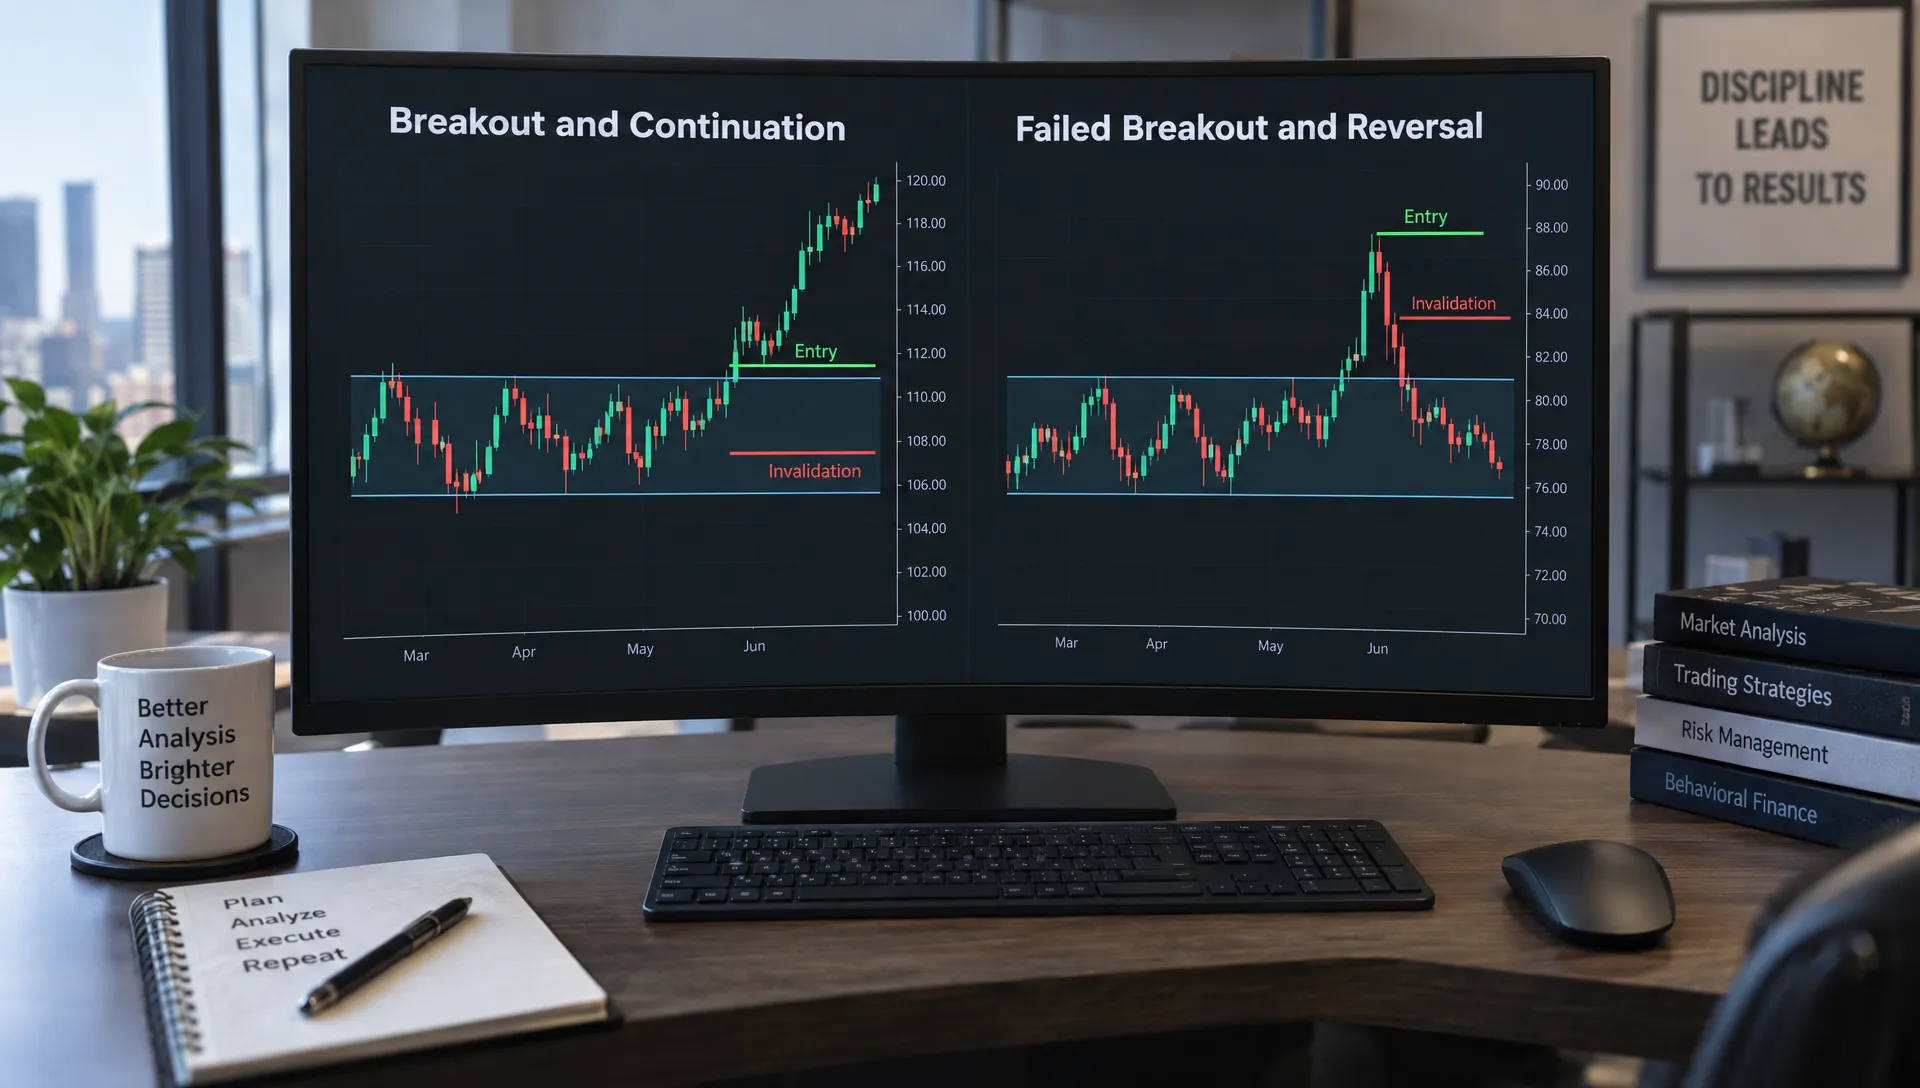
Consider a hypothetical stock that has traded between $100 and $110 for several weeks. It rises through $110 and reaches $112.
A continuation trader might buy at $112 after a predefined confirmation signal, with an invalidation level at $108. The hypothesis is that demand can sustain prices above the old range. A return below the breakout area would weaken that case. The trader might then use a trailing exit rather than assume $115 or $120 must be the final destination.
A mean-reversion trader does not have to sell the same breakout immediately. They might wait until it fails and the stock returns to $109, then consider a short position targeting the range midpoint near $105. In this example, a move back above $113 could invalidate the failed-breakout hypothesis.
All prices are illustrative, and neither setup guarantees an advantageous trade. Short selling also introduces borrowing costs and potentially unlimited losses. A long-only investor could simply avoid buying the breakout rather than take the opposite position.
The distinction is confirmation: one trader wants acceptance above the range, while the other wants evidence that acceptance failed. Our guide to when countertrend trades may be worth the risk explores that second decision in more detail.
Market regime and timeframe change the interpretation
The relevant question in momentum trend trading is whether directional persistence remains supported on the timeframe being traded. A strong daily uptrend can contain an hourly selloff, and an hourly rebound can occur inside a persistent daily downtrend.
That creates room for both approaches without making them interchangeable. A trader might buy a short-term overshoot below a moving average while restricting purchases to stocks in longer-term uptrends. The entry seeks local mean reversion; the broader filter seeks trend alignment.
Directional markets generally create more opportunities for continuation rules. Sideways markets can produce repeated breakouts that quickly fail. Conversely, an established trading range can support convergence trades until a genuine repricing breaks it.
Indicators cannot identify these conditions with certainty. A high relative strength index, or RSI, can indicate persistent buying pressure rather than an imminent decline. Likewise, a price far below its moving average may reflect deteriorating fundamentals rather than a bargain.
Momentum also has risks beyond ordinary sideways-market losses. Daniel and Moskowitz's research on momentum crashes examines severe losses in momentum portfolios around certain market rebounds. Those findings concern the portfolios studied, not every directional strategy, but they underline why recent persistence should not be treated as permanent.
Define the regime using information available before the trade. Calling a market “obviously trending” after a large move does not make the signal usable in real time.
Exits create different payoff profiles
Momentum trend trading generally needs an exit that gives continuation enough room to develop. Taking every small profit while allowing failed positions to keep falling can undermine the original hypothesis.
Some trend systems accept frequent small losses in exchange for occasional larger gains. Their challenge is staying consistent through false starts without assuming the next large winner is guaranteed. Tighter stops reduce the distance to an exit, but they can also increase the number of trades stopped out by ordinary fluctuations.
A convergence trade usually has a more explicit destination. If the thesis is a return from $95 to a reference near $100, reaching that reference may exhaust the reason for holding. Continuing to hold for $110 introduces a new hypothesis.
Mean-reversion systems can produce frequent small gains while retaining exposure to an unusually large loss when the reference breaks down. That is a possible payoff pattern, not an unavoidable property of every such system.
For either approach, position size should reflect the distance to invalidation and the loss the portfolio can tolerate. A stop order does not guarantee its execution price, especially around earnings announcements, overnight gaps or thin liquidity. These risk-management rules for technical trend trading explain how sizing and invalidation work together.
Compare net expectancy, not just the win rate
A strategy that wins often can still lose money. A strategy that loses more often than it wins can still have positive expectancy if its average gain sufficiently exceeds its average loss.
A simple trade-level calculation is:
Expected result = (win rate × average win) - (loss rate × average loss) - average costs.
The following hypothetical examples express results in units of planned initial risk, called R. They are arithmetic illustrations, not performance estimates for either strategy.
| Illustrative trade profile | Win rate | Average win | Average loss | Expectancy before costs | After assumed costs of 0.05R per trade |
|---|---|---|---|---|---|
| Lower win rate, larger winners | 40% | 2R | 1R | +0.20R | +0.15R |
| Higher win rate, larger losses | 70% | 0.5R | 1.5R | -0.10R | -0.15R |
Actual results can be less stable than these averages imply. Slippage, borrowing fees and occasional losses beyond the planned stop can change the calculation materially.
Evaluating momentum trend trading also requires attention to drawdowns, exposure and holding periods. Two systems with the same average result per trade may require very different amounts of capital or time in the market.
Sharpe ratios add useful risk-adjusted context, but they do not replace inspection of large losses, leverage or concentrated exposure. Compare strategies over the same dates and against a relevant benchmark rather than selecting whichever summary statistic looks strongest.
Test the hypothesis before combining strategies
Write each strategy as a separate, testable decision rule. Specify the eligible assets, signal timeframe, entry condition, invalidation point and exit logic before examining results. For a convergence strategy, also define why the reference should remain meaningful.
A backtest should use information that would actually have been available at each decision. Selecting today's surviving stocks and testing only their past prices can introduce survivorship bias. Using a closing price to generate a signal and assuming an execution at that same close can create unrealistic fills unless the implementation supports that timing.
Transaction costs matter particularly when expected moves are small or turnover is high. Test realistic spreads and slippage, then examine performance across different market conditions and an untouched out-of-sample period. A rule that works only at one precisely optimized setting deserves skepticism.
Combining mean reversion with momentum trend trading should be a deliberate portfolio decision, not a rescue plan for losing positions. Different labels do not guarantee diversification: both strategies may lose during the same volatility shock or depend on the same sector exposure.
Keep separate records for each hypothesis. If you change a position's purpose, treat that as a new decision with a new risk assessment, not a reason to erase the original stop.
Frequently asked questions
Which approach is more profitable? Neither is universally more profitable. Results depend on the rules, market conditions, implementation costs and risk taken. Compare net returns, drawdowns and exposure over consistent periods. A historical result from one market or timeframe does not establish an advantage elsewhere.
Is an EMA better than an SMA? An exponential moving average gives greater weight to recent prices and responds faster than a simple moving average of the same length. Faster response can reduce lag but also increase sensitivity to noise. Neither moving average makes momentum trend trading inherently profitable, and neither proves that a stretched price must reverse.
Are there three indicators every trader needs? There is no mandatory set. A practical analysis can separate direction, strength and volatility, using measures such as a moving average, rate of change and average true range. Several indicators derived from the same prices may provide overlapping information rather than independent confirmation.
Can a pullback trade belong to either strategy? Yes. Buying a pullback to capture a rebound toward a nearby average is a convergence hypothesis. Buying it because you expect the larger uptrend to resume is a continuation hypothesis. A strategy can combine those ideas, but its exit and invalidation rules should state exactly what is being tested.
Use portfolio comparisons as context, not an entry signal
Price action explains what the market has done. Portfolio data can add context about what other investors hold, how allocations differ and where exposure is concentrated.
Upside Invest combines verified investor holdings, portfolio comparison tools and trend tracking with private, anonymous profiles. Those features can help you compare your own exposures and investigate investment themes without treating another investor's position as an instruction to trade.
A holding alone does not reveal its owner's complete thesis, intended holding period or willingness to absorb losses. Strong historical returns also do not establish that a portfolio's future risk matches yours.
Whether you use momentum trend trading or mean reversion, keep the sequence clear: define the hypothesis, identify what would invalidate it and size the position accordingly. Use community and portfolio insights to inform that process, not replace it.